
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AST SpaceMobile (ASTS) Stock Looks Rich After Its Huge Three Year Run
AST SpaceMobile stock has logged a very large three year gain, yet current valuation checks now lean toward an expensive read based on market multiples and a middling overall value score. The recent pullback over shorter time frames gives you a cheaper entry point than a few months ago, but the question is whether that discount is meaningful or just noise after such a steep climb.
- Over the past three years, AST SpaceMobile has returned roughly 14.6x, which puts its recent short term weakness in the context of an unusually strong longer term move.
- The recently announced preliminary US$1b Japanese government backed BlueBird expansion deal can support higher revenue expectations. At the same time, ongoing legal disputes and execution risk around scaling the constellation may cap how much valuation investors are comfortable paying.
- The broader checks paint a mixed picture rather than a clear bargain or clear overvaluation. The value score of 3 suggests the stock screens neither clearly cheap nor clearly rich on balance.
For investors, the debate is whether AST SpaceMobile's very large past gains and rich multiple verdict already reflect the Japanese deal and growth hopes, or if the recent weakness has moved the price closer to a level that fairly compensates for the risks around execution and legal issues.
Broaden your watchlist beyond AST SpaceMobile by scanning our screener containing 16 high quality undiscovered gems that have flown under the radar while still showing solid underlying fundamentals.
Has AST SpaceMobile Run Too Far on Book Value?
P/B is often the cleanest yardstick for AST SpaceMobile because the story is still pre profit and anchored more to assets and capital than to earnings.
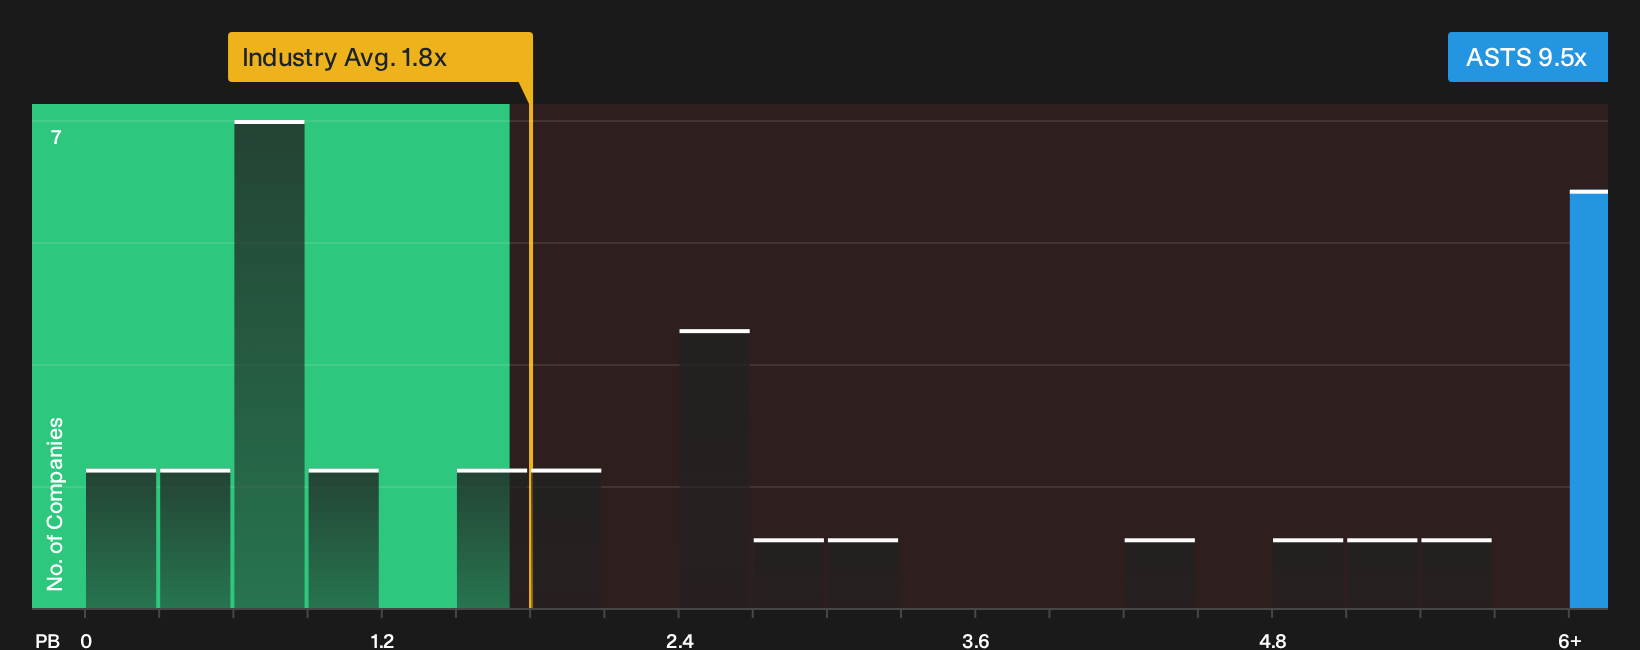
The stock trades around 9.5x P/B, compared with a telecom sector average near 1.8x and a peer group reference closer to 13.3x. That leaves AST SpaceMobile priced at a steep premium to the broader industry, even if it screens cheaper than some higher beta peers that investors may use as a comparison set.
Despite the recent US$1b Japanese backed BlueBird award adding support to the balance sheet, the market is still paying a rich price for every dollar of equity on this P/B yardstick. The model framework, which heavily penalises current losses and execution risk, treats this wide gap as a warning sign rather than a precise mispricing.
On the P/B multiple alone, AST SpaceMobile screens as clearly expensive relative to the wider telecom group, even after the pullback.
See what the numbers say about this price — find out in our valuation breakdown.
The AST SpaceMobile Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the AST SpaceMobile valuation puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to play out for the shares to be worth meaningfully more or less than today. Each narrative sets out its own fair value assumptions in plain terms, so you can later compare those expectations with how AST SpaceMobile's actual results and execution progress show up on the Community page.
The community split on AST SpaceMobile could hardly be wider, with one camp treating it as a moonshot opportunity and the other as a crowded trade.
Bull case: 65% undervalued
"AST SpaceMobile is one of the most ambitious infrastructure stories in the market, and is trying to build a space-based cellular broadband network that connects directly to standard, unmodified smartphones using spectrum from mobile network operators..."
Read the full Bull Case to see why AST SpaceMobile could be undervalued
Bear case: 50% overvalued
"At $90.94, ASTS is a victim of its own success, priced for a flawless future that ignores a $1.2B annual burn and a newly aggressive Amazon..."
Read the full Bear Case to see why AST SpaceMobile could be overvalued
Do you think there's more to the story for AST SpaceMobile? Head over to our Community to see what others are saying!
The Bottom Line
AST SpaceMobile now looks overvalued on traditional market multiples, especially on P/B, which embeds a lot of optimism into the current tag. The valuation debate no longer hinges on whether it is cheap, but on how much you are willing to pay for a complex build out that still carries execution and legal risk. Everything circles back to one question: Can AST SpaceMobile convert its technical promise and headline contracts into a scaled, capital efficient network that justifies paying such a premium for its equity base?
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com