
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
WEX (WEX) Leans On AI And Buybacks, Is The Stock Getting Pricey?
WEX (WEX) is back on investor radar after broad-based momentum across its Mobility, Benefits, and Corporate Payments segments, where AI tools and productivity programs are helping support margins, cash generation, and ongoing share buybacks.
Recent trading has been choppy, with a 1-day share price return of 0.78% and a 7-day share price return that declined 1.23%. However, WEX still carries a 90-day share price return of 41.34% and a 1-year total shareholder return of 12.84%, which points to momentum that has been building rather than fading despite some shorter term pullbacks.
Scan for other payment and fintech stocks showing similar AI driven momentum and cash generation in our curated 16 high quality undiscovered gems list.
Bulls see WEX as an AI powered cash engine that justifies the sharp move higher, while bears point to choppy returns and past three year underperformance. Which side does the current valuation actually support?
Most Popular Narrative: 2.3% Overvalued
The most followed narrative pegs WEX at a fair value of $187.30, slightly below the last close of $191.52. This frames the stock as a modest premium story.
Expanding investments in product innovation (AI-powered claims processing, enhanced payment platforms, and API integrations) and significant sales force increases, especially in Corporate Payments and Mobility, indicate a forward pipeline of new customer wins and greater share of digital payment transactions. This positions WEX to benefit from higher transaction volume, improved margins through operating leverage, and increased cross-sell of value-added services.
Read the complete narrative. Read the complete narrative.
It will be useful to see what kind of revenue trajectory and margin build this story is aligned with. The valuation depends on how far those earnings and future multiples are assumed to extend. It is also important to understand which assumptions carry the most weight in that $187.30 fair value estimate.
Result: Fair Value of $187.30 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the WEX story can be knocked off course if fuel card reliance collides with faster EV adoption, or if rising fintech competition pressures pricing power.
Find out about the key risks to this WEX narrative.
Another View: WEX Through A Cash Flow Lens
The market may be treating WEX as a modest premium story at $191.52, yet our DCF model points in a very different direction. On that framework, the ticker screens as materially undervalued, with an estimated future cash flow value of $491.34. That kind of gap raises a simple question. Is the current price missing the compounding effect of WEX's cash generation and buybacks, or is the cash flow model leaning too far into optimistic assumptions?
For readers who want to see how those long term cash assumptions are built and discounted in practice, the SWS DCF model lays out every step in full detail. Look into how the SWS DCF model arrives at its fair value.
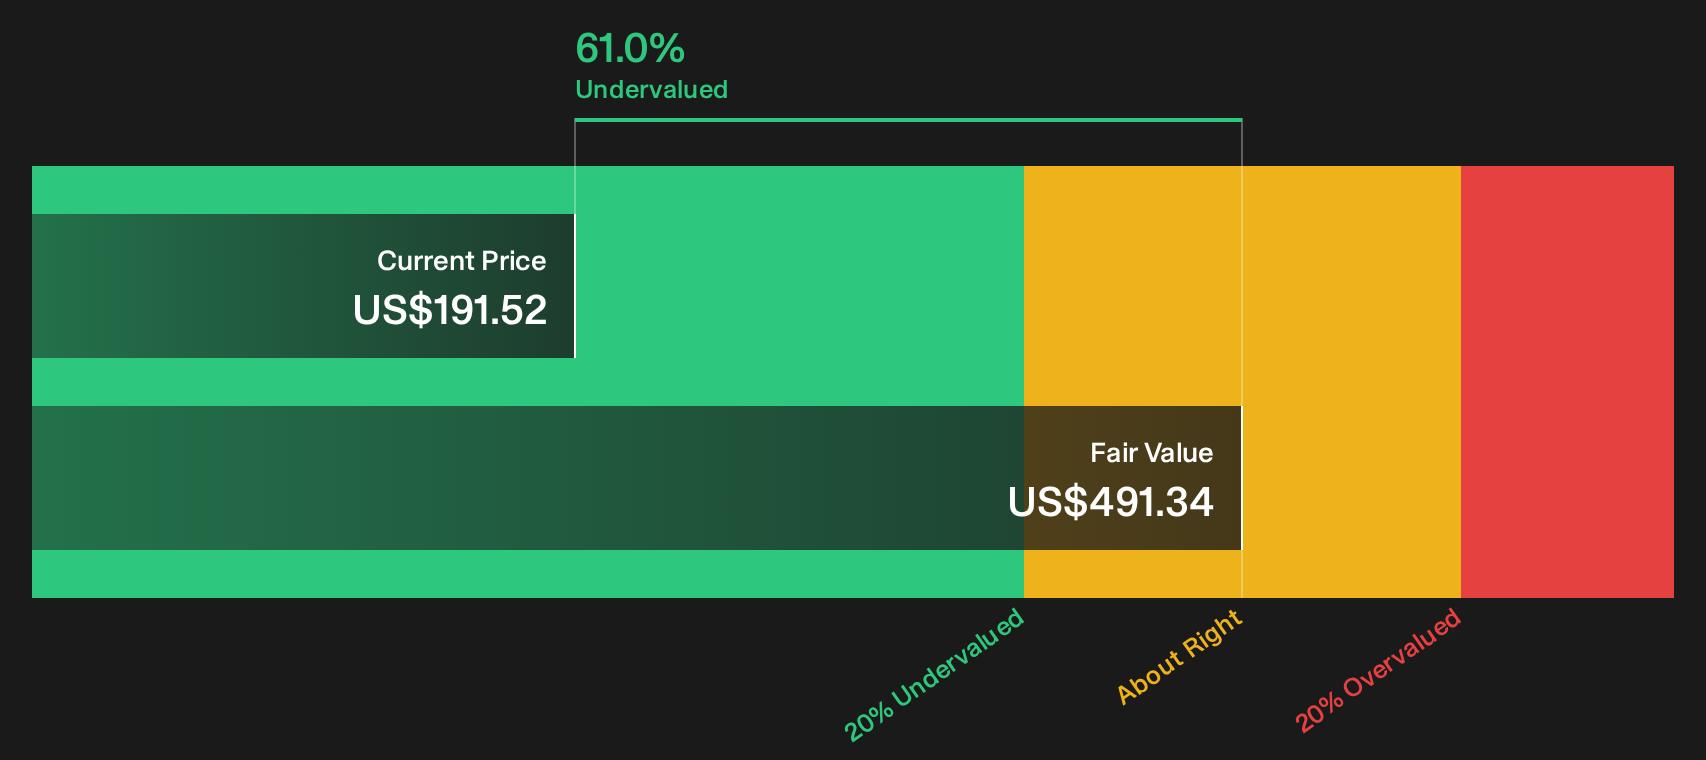
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out WEX for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages across WEX's valuation, cash flows, and recent returns mean sentiment is far from settled. Move fast, review the data, and weigh both sides using the 3 key rewards and 2 important warning signs.
Looking for more WEX sized opportunities?
Do not stop with WEX. Broaden your watchlist using targeted stock ideas that line up with the kind of risk, value, and income profile you actually want.
- Target stronger value by scanning for companies that combine solid fundamentals with appealing valuations through our 31 high quality undervalued stocks.
- Prioritize resilience by reviewing businesses that score well on financial strength using the focused list of solid balance sheet and fundamentals (23 results).
- Turn income potential into a plan by zeroing in on higher yielding payers via our curated 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com