
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
MercadoLibre (MELI) Could Be 48% Undervalued After Its $1b Debt Raise
MercadoLibre (MELI) just raised US$1.0b through new senior unsecured notes maturing in 2036. This funding move adds liquidity as the Latin American e-commerce and fintech heavyweight keeps pushing its expansion plans.
Over the past year, MercadoLibre has seen its share price slip 3.9% year to date and its 1 year total shareholder return decline 18.9%, even as a 19.4% 3 month share price gain and this week’s US$1.0b note issuance signal renewed momentum and shifting views on funding risk.
Spot 16 high quality undiscovered gems that, like MercadoLibre, are using fresh funding and strong top-line momentum to push ambitious growth plans across their core markets.MercadoLibre just pulled in US$1.0b of fresh debt at 5.850% while its share price performance over 1 year has been weak. Is that move a vote of confidence in the business, or mainly a swing in sentiment, and what does the current valuation imply?
Most Popular Narrative: 48.4% Undervalued
On the main narrative, MercadoLibre’s fair value of $3,675.71 sits well above the recent $1,897.37 close, which raises questions about how investors view its debt-funded expansion and credit-heavy fintech push.
MercadoLibre is the dominant e-commerce and fintech platform across Brazil, Mexico, and Argentina; it is often compared to a combination of Amazon and PayPal in a single company, operating in a region where the average shopper makes 7 online purchases a year versus 41 in the US. Revenue grew 49% last quarter, the fastest pace since 2022. Unique buyers reached 84.1 million, up 26%. Brazil alone added 17 million new buyers in twelve months, roughly the population of the Netherlands deciding to start shopping on one app in a single year.
Want to see why this valuation is so high for MercadoLibre? The narrative emphasizes rapid top-line gains, expanding fintech reach, and a very ambitious earnings curve that connects those elements.
Result: Fair Value of $3,675.71 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, MercadoLibre’s case can break if rapid credit expansion sours into heavier losses, or if ongoing logistics investment keeps margins under pressure for longer than investors expect.
Find out about the key risks to this MercadoLibre narrative.
Another View: MercadoLibre Looks Expensive On Earnings
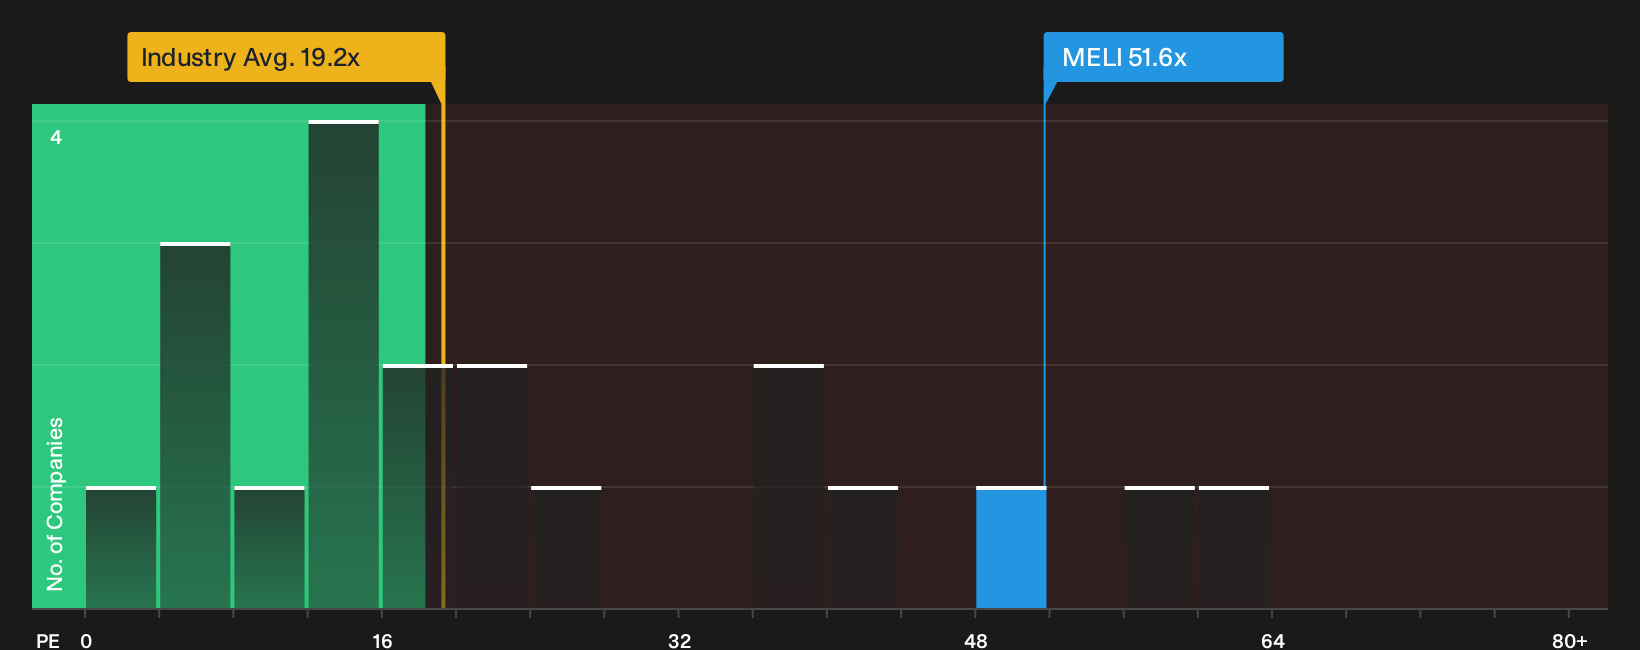
The DCF workup paints MercadoLibre as attractively priced, yet the earnings multiple tells a very different story. The stock trades on a P/E of 51.6x compared with a peer average of 21.5x and a fair ratio of 36.4x, which points to rich expectations and valuation risk if profits disappoint. Which signal do you treat as more important right now?
See what the numbers say about this price in our valuation breakdown, starting with the earnings multiple gap: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings about MercadoLibre’s risk and reward balance so far. Move quickly from headline impressions to your own view by checking the 2 key rewards and 2 important warning signs.
Looking for more MercadoLibre style investment ideas?
Do not stop with MercadoLibre. Use the same structured approach across a wider watchlist so fresh ideas reach you before they feel obvious to everyone else.
- Target quality at a discount by scanning a curated set of underappreciated opportunities through the 31 high quality undervalued stocks.
- Strengthen your downside protection by focusing on businesses with cleaner finances using the list of solid balance sheet and fundamentals (23 results).
- Stalk future winners early by tracking a hand picked pool of lesser known prospects inside the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com