
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Gilead Sciences (GILD) Just Gave Investors Something To Think About
Gilead Sciences (GILD) just saw its herpes simplex virus collaboration with Assembly Biosciences deepen, as Assembly opted into a 40% U.S. cost and profit share on the HSV helicase primase program.
The Gilead Sciences share price has climbed 18.19% year to date and 14.44% over the past 90 days, while the 1-year total shareholder return of 28.73% and 3-year total shareholder return above 2x suggest momentum has been building as investors weigh recent product approvals, legal wins and expanded research commitments against the latest HSV tie up with Assembly.
Scan 31 high quality undervalued stocks that share Gilead Sciences’ mix of large-cap scale, active pipelines, and recent catalyst-driven momentum in biotech and healthcare.After a near 30% 1 year total return and a share price near US$144, Gilead Sciences now sits at a different entry point. Does the current valuation still leave enough upside to justify fresh risk?
Most Popular Narrative: 11.9% Overvalued
The most widely followed narrative on Gilead Sciences pegs fair value at $128.38, which sits below the recent $143.72 close and frames the current rally as rich against that lens.
Gilead is transitioning from a “single-franchise HIV company” into a multi-platform biopharma with high-probability growth drivers like lenacapavir and Trodelvy. At the same time, temporary earnings headwinds from acquisitions and pipeline build-out are masking what could be long-run value creation as these assets mature and new launches come through.
Want to see what sits behind that $128 fair value for Gilead Sciences? The narrative focuses on potential future profitability, healthier margins, and a richer earnings multiple than the recent history would suggest.
Result: Fair Value of $128.38 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Gilead Sciences faces real pressure if recent acquisitions fail to translate into profitable products or if key oncology and HIV trials deliver weaker than expected data.
Find out about the key risks to this Gilead Sciences narrative.
Another View on Gilead Sciences Valuation
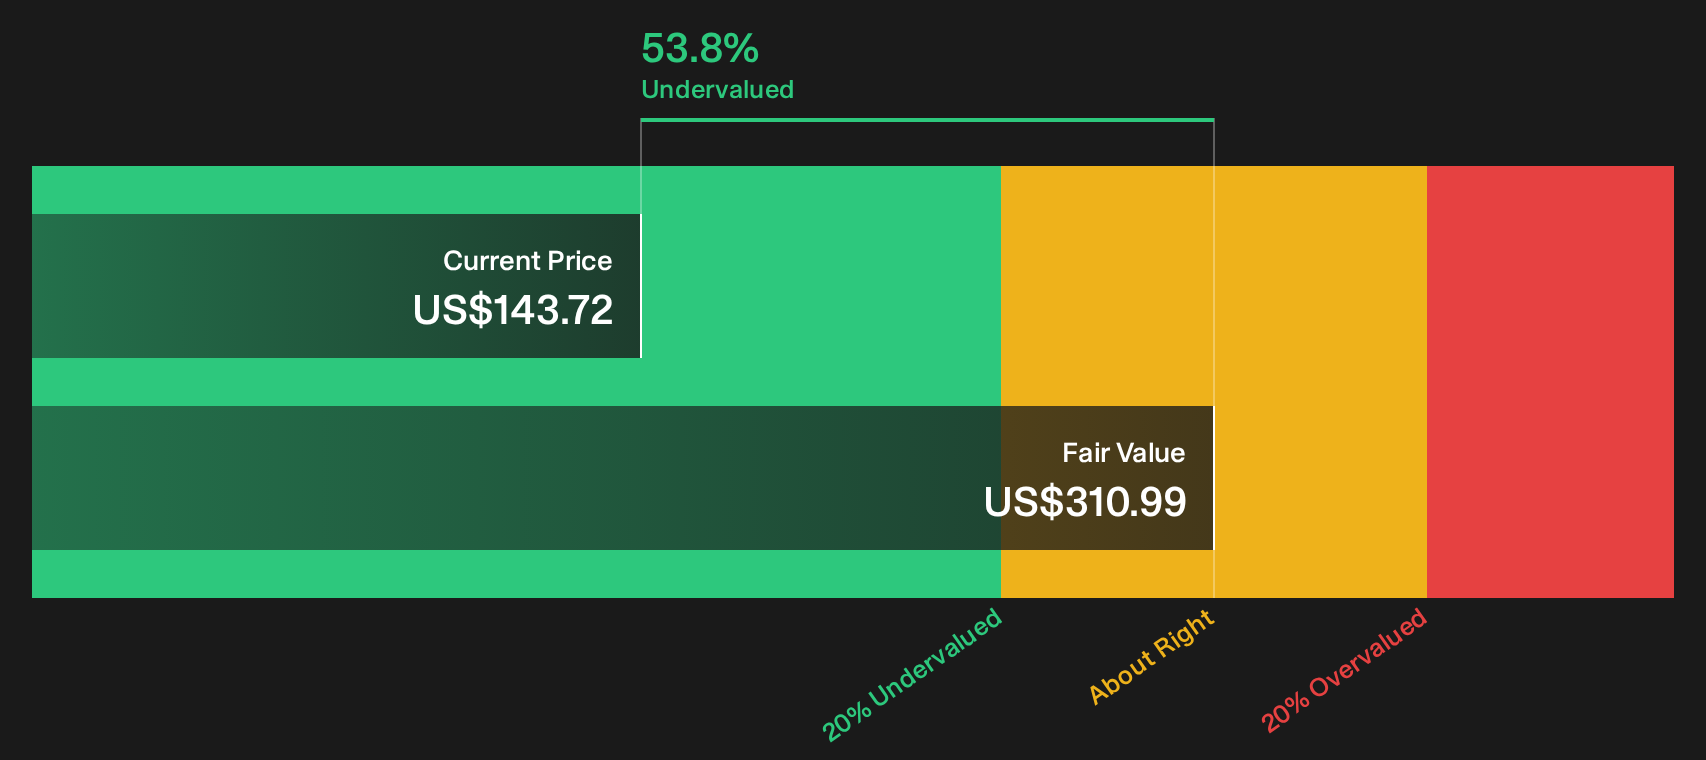
The user narrative calls Gilead Sciences about 11.9% overvalued at $143.72 versus a $128.38 fair value. Our DCF model presents a different perspective. It assigns a future cash flow value of $310.99 per share, which implies GILD trades at a steep discount.
That kind of gap between a narrative-based fair value and the SWS DCF model raises a simple question for investors: Which set of assumptions feels closer to how Gilead Sciences will actually convert its pipeline into cash flows over time, and which one do you trust more?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on Gilead Sciences so far? If the split between risk and upside looks tight, move quickly and weigh the full picture for yourself with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Gilead Sciences?
If Gilead Sciences has sharpened your focus on quality opportunities, do not stop here. Use the Simply Wall Street Screener to quickly spot other clear, data backed ideas.
- Target resilient cash flows by scanning companies with robust payouts and balance sheets using 6 dividend fortresses.
- Hunt for mispriced quality by filtering for financially strong opportunities through 16 high quality undiscovered gems.
- Dial down portfolio stress by zeroing in on sturdier candidates with 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com