
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Flotek Industries (FTK) Stock Looks Overvalued After A 7x Run
Flotek Industries has delivered a very large 3 year return, yet its current valuation checks lean expensive, so anyone looking at the stock today has to weigh strong recent gains against a weaker value score.
- Over the past 3 years, Flotek Industries has returned roughly 7x, which puts recent enthusiasm in sharp contrast with the cautious read from broader valuation metrics.
- Stronger expectations around international chemistry sales can support the current share price, while any disappointment in those overseas volumes may pressure how much investors are willing to pay for the business.
- The broader valuation framework gives Flotek Industries a low value score of 1 out of 6, which points to a stock that leans expensive rather than a clear bargain.
The issue now is whether the recent share price level for Flotek Industries still offers enough valuation support after such a strong multi year run.
Spot our screener containing 16 high quality undiscovered gems that have strong multi year returns like Flotek Industries, while still scoring better on valuation checks.Does Flotek Industries Look Pricey on Earnings?
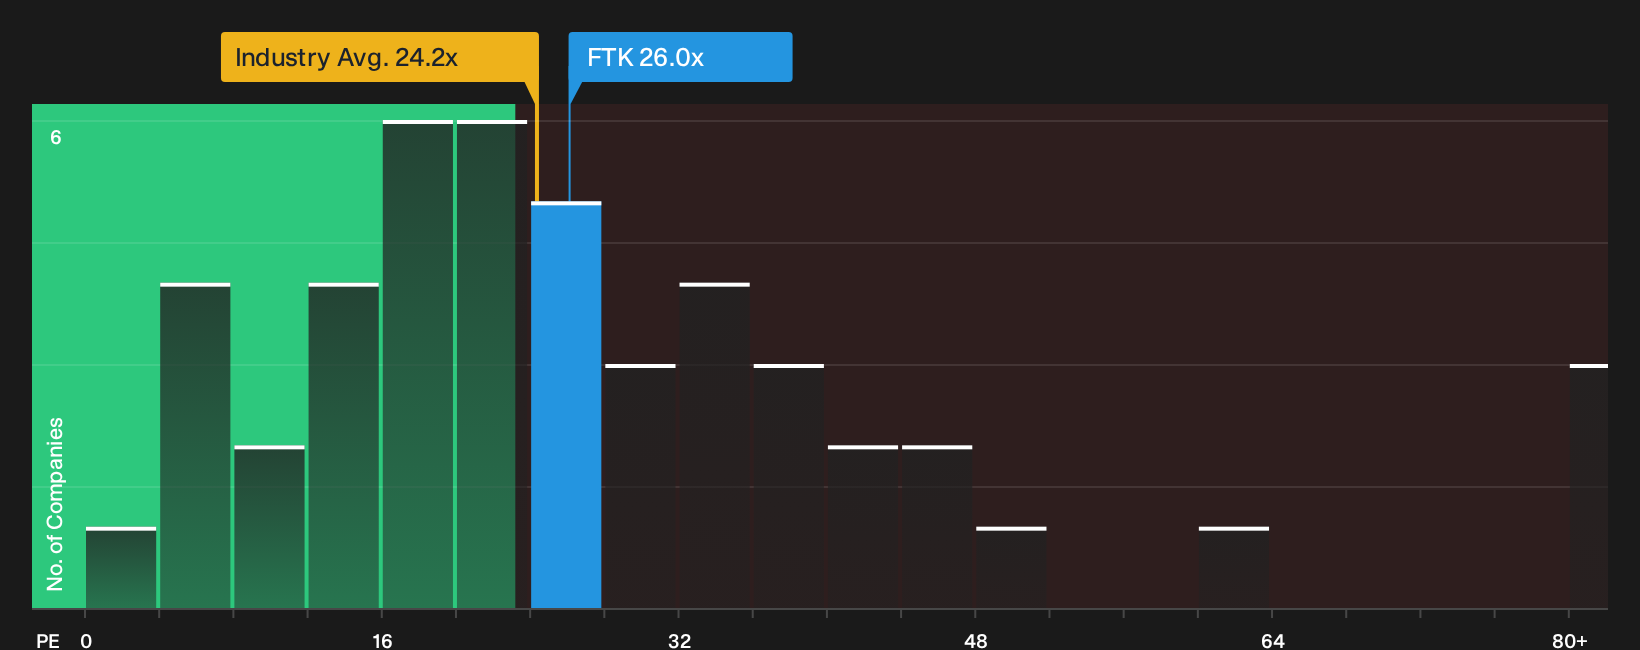
The P/E ratio fits Flotek Industries because earnings are a key reference point for many investors in established chemicals businesses. Flotek trades on a P/E of about 26.0x, above the broader chemicals sector average of roughly 24.2x. Compared with a peer group average of about 16.8x, that premium is even wider, which already suggests investors are paying a high price for each dollar of current profit.
A more tailored fair P/E multiple for Flotek Industries, which blends its sector, size and risk profile, sits nearer 16.0x. That is well below the market price of roughly 26.0x, so the shares trade at a hefty premium to what this framework flags as a more grounded level. Despite the raised 2026 guidance around international chemistry sales and higher expected Adjusted EBITDA, the current earnings multiple still implies a rich valuation versus both peers and the fair ratio.
On the P/E test alone, Flotek Industries stock looks overvalued.
See what the numbers say about this price — find out in our valuation breakdown.
The Flotek Industries Narrative: What Would Justify Today's Price?
Flotek Industries' valuation puzzle raises an obvious question for you as an investor, which is what kind of future would need to unfold for the current share price to look either restrained or stretched. Simply Wall St Narratives on the Community page take that question and spell out the earnings, margin and growth paths that would need to line up for very different outcomes, with each scenario tying a fair value to a particular mix of potential catalysts and key risks so you can track which version of events starts to line up with reality over time.
Community views on Flotek Industries sit far apart, with one camp focused on digital chemistry upside and the other on long term energy transition risk.
Bull case: 29% undervalued
"Multi-year contracts and a growing customer base for high-margin Data Analytics offerings provide significant revenue visibility and margin expansion potential…"
Read the full Bull Case to see why Flotek Industries could be undervalued
Bear case: 44% overvalued
"Flotek remains highly exposed to concentrated customer risk, especially with the majority of new data analytics assets currently serving one major client, ProFrac…"
Read the full Bear Case to see why Flotek Industries could be overvalued
Do you think there's more to the story for Flotek Industries? Head over to our Community to see what others are saying!
The Bottom Line
Flotek Industries now screens as overvalued on the market-multiple view, with investors already paying up relative to sector and peer benchmarks. That gap can make sense if international chemistry demand and data analytics traction hold up strongly, because the current price leans on those expectations being met. The real hinge from here is whether the business can translate its contract base and product mix into earnings that justify a premium multiple rather than leave the stock exposed to a reset in sentiment.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com