
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Companies Like Winson Holdings Hong Kong (HKG:6812) Are In A Position To Invest In Growth
There's no doubt that money can be made by owning shares of unprofitable businesses. For example, although software-as-a-service business Salesforce.com lost money for years while it grew recurring revenue, if you held shares since 2005, you'd have done very well indeed. But the harsh reality is that very many loss making companies burn through all their cash and go bankrupt.
So should Winson Holdings Hong Kong (HKG:6812) shareholders be worried about its cash burn? In this article, we define cash burn as its annual (negative) free cash flow, which is the amount of money a company spends each year to fund its growth. The first step is to compare its cash burn with its cash reserves, to give us its 'cash runway'.
When Might Winson Holdings Hong Kong Run Out Of Money?
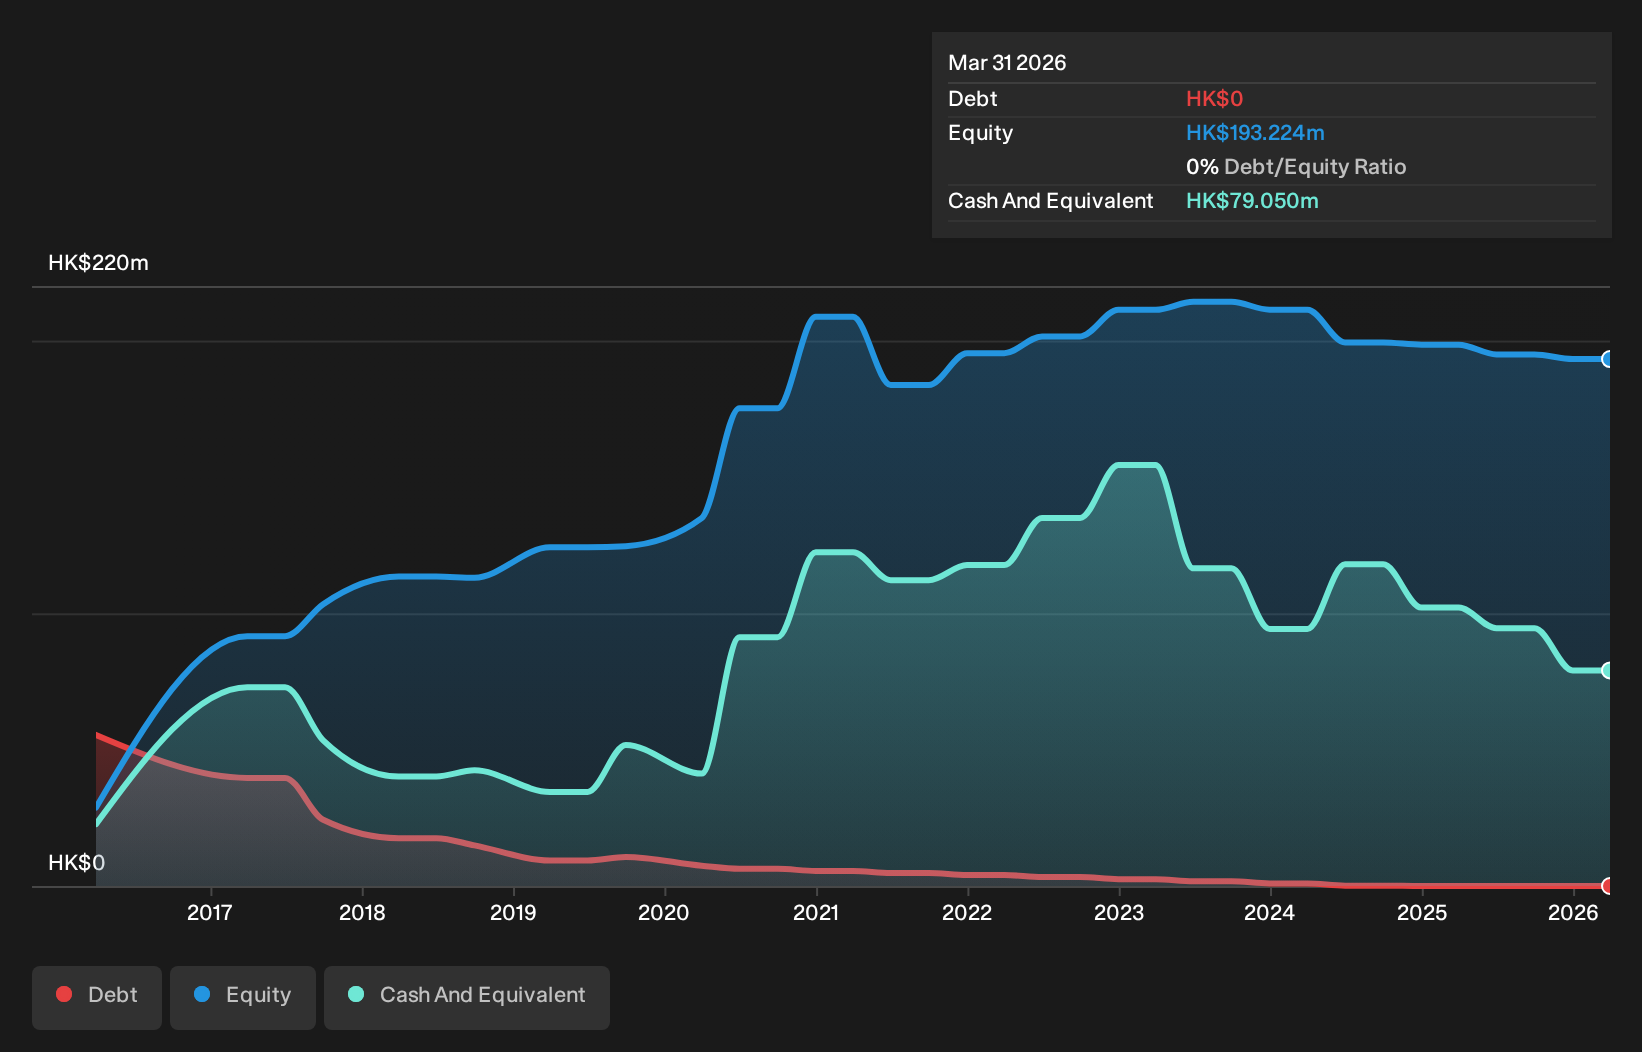
A company's cash runway is the amount of time it would take to burn through its cash reserves at its current cash burn rate. When Winson Holdings Hong Kong last reported its March 2026 balance sheet in June 2026, it had zero debt and cash worth HK$79m. Importantly, its cash burn was HK$20m over the trailing twelve months. So it had a cash runway of about 4.1 years from March 2026. A runway of this length affords the company the time and space it needs to develop the business. You can see how its cash balance has changed over time in the image below.
View our latest analysis for Winson Holdings Hong Kong
Is Winson Holdings Hong Kong's Revenue Growing?
Given that Winson Holdings Hong Kong actually had positive free cash flow last year, before burning cash this year, we'll focus on its operating revenue to get a measure of the business trajectory. Although it's hardly brilliant growth, it's good to see the company grew revenue by 7.7% in the last year. Of course, we've only taken a quick look at the stock's growth metrics, here. You can take a look at how Winson Holdings Hong Kong has developed its business over time by checking this visualization of its revenue and earnings history.
Can Winson Holdings Hong Kong Raise More Cash Easily?
Notwithstanding Winson Holdings Hong Kong's revenue growth, it is still important to consider how it could raise more money, if it needs to. Issuing new shares, or taking on debt, are the most common ways for a listed company to raise more money for its business. One of the main advantages held by publicly listed companies is that they can sell shares to investors to raise cash and fund growth. By comparing a company's annual cash burn to its total market capitalisation, we can estimate roughly how many shares it would have to issue in order to run the company for another year (at the same burn rate).
Winson Holdings Hong Kong has a market capitalisation of HK$168m and burnt through HK$20m last year, which is 12% of the company's market value. Given that situation, it's fair to say the company wouldn't have much trouble raising more cash for growth, but shareholders would be somewhat diluted.
How Risky Is Winson Holdings Hong Kong's Cash Burn Situation?
It may already be apparent to you that we're relatively comfortable with the way Winson Holdings Hong Kong is burning through its cash. In particular, we think its cash runway stands out as evidence that the company is well on top of its spending. Its weak point is its revenue growth, but even that wasn't too bad! After taking into account the various metrics mentioned in this report, we're pretty comfortable with how the company is spending its cash, as it seems on track to meet its needs over the medium term. On another note, Winson Holdings Hong Kong has 2 warning signs (and 1 which shouldn't be ignored) we think you should know about.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of interesting companies, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.