
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Rising NII and Softer Earnings Just Recast Ameris Bancorp's (ABCB) Risk‑Reward Balance?
- Ameris Bancorp recently reported past second-quarter 2026 results, with net interest income rising to US$252.48 million while net income dropped to US$51.45 million and diluted EPS from continuing operations fell to US$0.77 compared with the prior year.
- Alongside higher net charge-offs of US$11.06 million and continued share buybacks totaling 3,884,987 shares since 2019, the earnings highlight a mix of credit cost pressure and capital return at Ameris Bancorp.
- We will now examine how weaker net income despite higher net interest income affects Ameris Bancorp’s existing investment narrative and assumptions.
Uncover the next big thing with 20 elite penny stocks that balance risk and reward.
Ameris Bancorp Investment Narrative Recap
To own Ameris Bancorp, you need to be comfortable with a regional bank story built on net interest income and concentrated Southeastern exposure, while accepting that credit costs can quickly alter earnings. The latest quarter showed exactly that tension: higher net interest income but sharply lower net income as credit losses rose. For now, this weak earnings print does not appear to fundamentally change the key near term catalyst of loan growth potential or the main risk of margin and credit pressure.
The most relevant recent development alongside these results is the ongoing share repurchase program, which has now retired 3,884,987 shares since 2019 at a cost of US$234.58 million. While buybacks can support per share metrics, they sit against a backdrop of rising net charge offs and competitive pressure for deposits and loans, which remain central to how investors may rethink their assumptions about earnings resilience.
Yet, investors should be aware that rising net charge offs and tougher loan competition could quickly challenge any simple “higher net interest income is enough” story...
Read the full narrative on Ameris Bancorp (it's free!)
Ameris Bancorp's narrative projects $1.6 billion revenue and $504.2 million earnings by 2029. This requires 9.9% yearly revenue growth and about a $69.5 million earnings increase from $434.7 million today.
Uncover how Ameris Bancorp's forecasts yield a $93.86 fair value, a 7% upside to its current price.
Exploring Other Perspectives
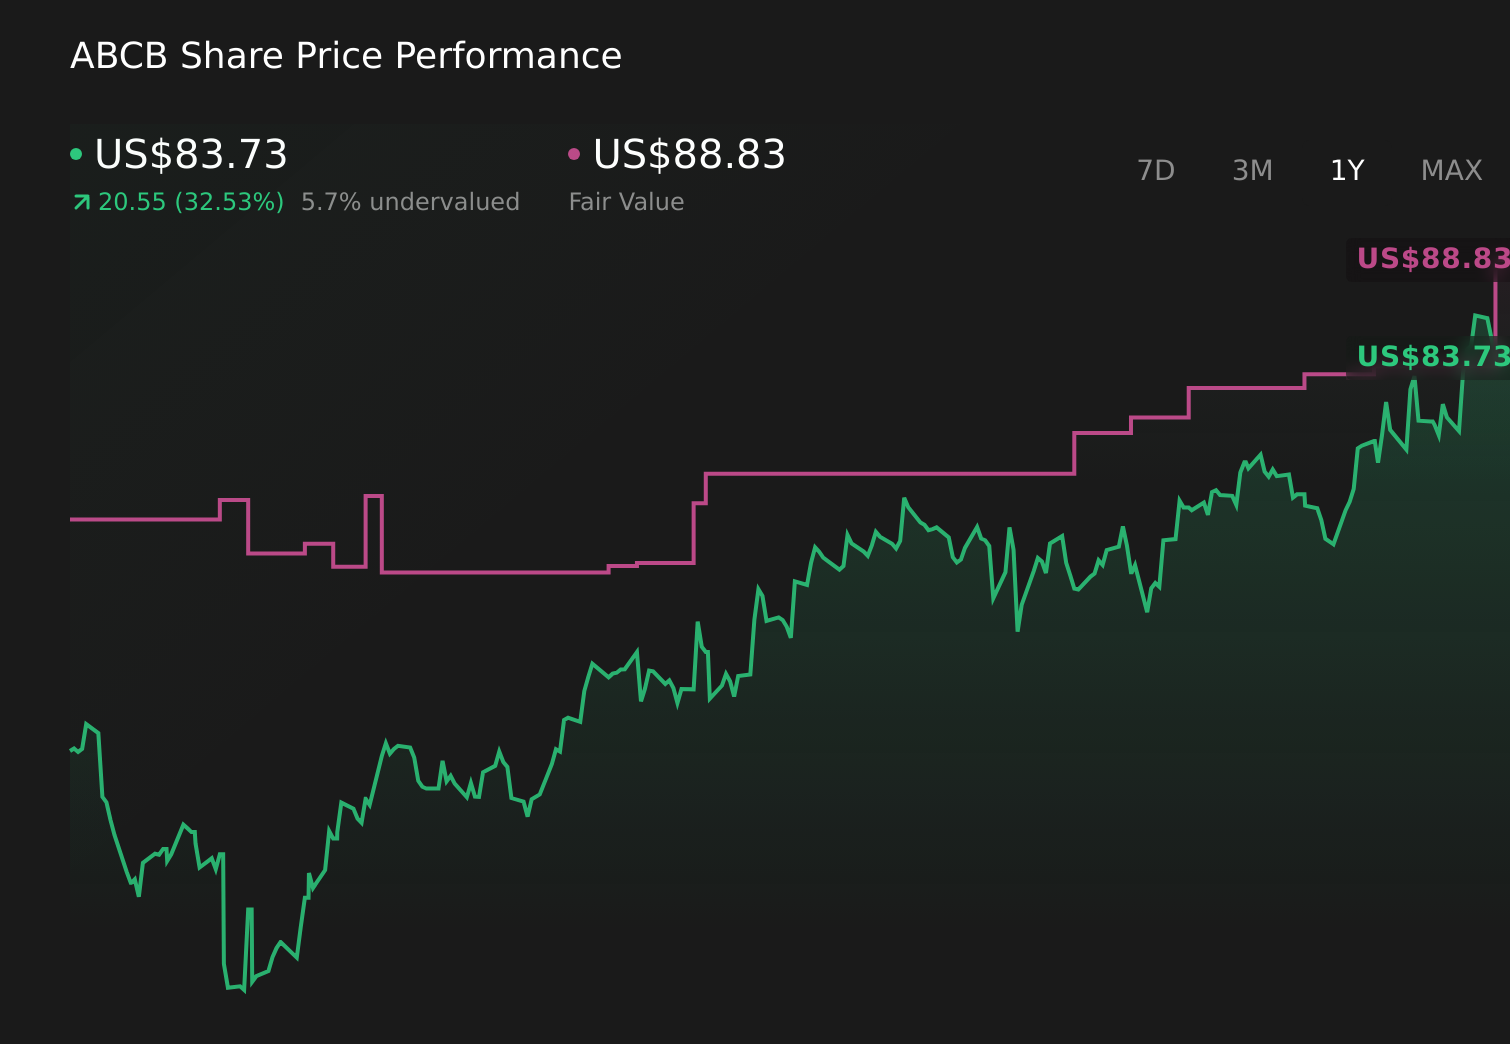
The single fair value estimate from the Simply Wall St Community sits at US$93.86, showing one retail view of Ameris Bancorp’s potential. Readers should weigh this against rising credit costs and competitive pressure on margins, and explore several contrasting viewpoints before forming their own view.
Explore another fair value estimate on Ameris Bancorp - why the stock might be worth as much as 7% more than the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ameris Bancorp research is our analysis highlighting 2 key rewards that could impact your investment decision.
- Our free Ameris Bancorp research report provides a comprehensive fundamental analysis summarized in a single visual - the Snowflake - making it easy to evaluate Ameris Bancorp's overall financial health at a glance.
Contemplating Other Strategies?
Right now could be the best entry point. These picks are fresh from our daily scans. Don't delay:
- Find 49 companies with promising cash flow potential yet trading below their fair value.
- The future of work is here. Discover the 34 top robotics and automation stocks leading the charge in AI-driven automation and industrial transformation.
- Invest in the nuclear renaissance through our list of 90 elite nuclear energy infrastructure plays powering the global AI revolution.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com