' fill='white'%3e %3cg id='%e7%bc%96%e7%bb%84-7' transform='translate(0.000000%2c 86.000000)'%3e %3cg id='%e7%bc%96%e7%bb%84-2' transform='translate(80.533981%2c 22.000000)'%3e %3cpath d='M41.7832962%2c0 C41.9459106%2c0 42.0882746%2c0.0866854658 42.1666825%2c0.216359069 C43.8289923%2c2.66540836 44.7676281%2c5.46271319 44.7676281%2c8.43208061 C44.7676281%2c18.1345746 34.7460532%2c26 22.383814%2c26 C10.0215749%2c26 0%2c18.1345746 0%2c8.43208061 C0%2c5.46716016 0.935826425%2c2.67378733 2.58829888%2c0.223985685 C2.67109477%2c0.0916264068 2.81687473%2c0 2.9840593%2c0 C3.23130408%2c0 3.43173558%2c0.200393004 3.43173558%2c0.447590303 C3.43173558%2c0.475056669 3.42926112%2c0.501945205 3.42452292%2c0.528045226 L3.41810883%2c0.550292077 C3.37800671%2c0.861741908 3.3575721%2c1.17661276 3.3575721%2c1.49443092 C3.3575721%2c7.98336 11.2132389%2c12.5742305 22.383814%2c12.5742305 C33.5543891%2c12.5742305 41.410056%2c7.98336 41.410056%2c1.49443092 C41.410056%2c1.17865223 41.3898828%2c0.865783153 41.3502888%2c0.556288325 C41.3402868%2c0.521941442 41.3356199%2c0.48531078 41.3356199%2c0.447590303 C41.3356199%2c0.200393004 41.5360514%2c0 41.7832962%2c0 Z' id='logo%e5%a4%87%e4%bb%bd-6'%3e%3c/path%3e %3cpath d='M75.1559425%2c3.74404927 C75.7071421%2c3.74404927 76.2394493%2c3.66184338 76.7416414%2c3.50883715 L74.281987%2c20.8666902 C74.0430787%2c22.5662954 73.2732628%2c23.0518969 71.8929033%2c23.0518969 L70.459453%2c23.0518969 C69.2649111%2c23.0518969 68.6278221%2c22.458384 68.2561868%2c20.893668 L66.1591022%2c11.9909739 C66.1060114%2c11.7481731 66.1060114%2c11.6942174 65.9998299%2c11.6942174 C65.8936484%2c11.6942174 65.867103%2c11.7481731 65.8140123%2c11.9909739 L63.7169276%2c20.893668 C63.3452924%2c22.458384 62.7082033%2c23.0518969 61.5136614%2c23.0518969 L60.0802112%2c23.0518969 C58.6998516%2c23.0518969 57.9300358%2c22.5662954 57.6911274%2c20.8666902 L55.2123917%2c3.37406084 C55.8253692%2c3.61307396 56.491017%2c3.74404927 57.1867652%2c3.74404927 C57.7974457%2c3.74404927 58.3849364%2c3.64314414 58.9339751%2c3.4568446 L60.8234817%2c19.3829078 C60.8500271%2c19.6257086 60.8500271%2c19.7875757 60.9562086%2c19.7875757 C61.0623901%2c19.7875757 61.0623901%2c19.6257086 61.1154808%2c19.3829078 L63.3983831%2c9.91367858 C63.5576554%2c9.26620991 63.9292906%2c8.69967483 65.0707418%2c8.69967483 L66.9023727%2c8.69967483 C68.0438238%2c8.69967483 68.4154591%2c9.26620991 68.5747313%2c9.91367858 L70.8576336%2c19.3829078 C70.9107244%2c19.6257086 70.9107244%2c19.7875757 71.0169059%2c19.7875757 C71.1230874%2c19.7875757 71.1230874%2c19.6257086 71.1496327%2c19.3829078 L73.0551401%2c3.32292288 C73.7026096%2c3.59432921 74.4120718%2c3.74404927 75.1559425%2c3.74404927 Z' id='Combined-Shape'%3e%3c/path%3e %3cpath d='M85.0594095%2c7.43171536 C89.1473973%2c7.43171536 91.3772089%2c10.2643908 91.3772089%2c14.2840921 L91.3772089%2c15.7948523 C91.3772089%2c16.2264981 91.2179366%2c16.4692988 90.8463013%2c16.4692988 L82.1925089%2c16.4692988 L82.1925089%2c16.5502324 C82.1925089%2c18.1149484 82.829598%2c19.9764208 85.377954%2c19.9764208 C87.3157664%2c19.9764208 89.1473973%2c19.8145536 90.2623031%2c19.7066422 L90.3419392%2c19.7066422 C90.607393%2c19.7066422 90.819756%2c19.8415315 90.819756%2c20.1113101 L90.819756%2c21.8918489 C90.819756%2c22.3234947 90.7401198%2c22.5123397 90.2623031%2c22.5932733 C88.5368537%2c22.9170076 87.501584%2c23.0518969 85.1125002%2c23.0518969 C82.4579627%2c23.0518969 78.6885194%2c21.5950924 78.6885194%2c16.2804538 L78.6885194%2c14.2840921 C78.6885194%2c10.0755457 80.997967%2c7.43171536 85.0594095%2c7.43171536 Z M85.0594095%2c10.5071915 C83.4135962%2c10.5071915 82.2190543%2c11.6942174 82.2190543%2c13.8254684 L82.2190543%2c13.9333799 L87.8466739%2c13.9333799 L87.8466739%2c13.8254684 C87.8466739%2c11.7211953 86.7052228%2c10.5071915 85.0594095%2c10.5071915 Z' id='Combined-Shape'%3e%3c/path%3e %3cpath d='M97.88151%2c2.98826245 L97.8808258%2c7.62056039 C98.8630047%2c7.48567108 99.7920929%2c7.43171536 100.429182%2c7.43171536 C104.702987%2c7.43171536 106.773527%2c9.99461216 106.773527%2c14.2031585 L106.773527%2c16.2804538 C106.773527%2c20.4890001 104.702987%2c23.0518969 100.429182%2c23.0518969 C98.7302779%2c23.0518969 96.7393747%2c22.7821183 95.0935614%2c22.3504725 C94.4830178%2c22.1886054 94.3768363%2c22.0267382 94.3768363%2c21.6220703 L94.3758373%2c3.08694115 C94.884566%2c3.24434375 95.4244809%2c3.32900525 95.9838525%2c3.32900525 C96.6506785%2c3.32900525 97.2898545%2c3.20869291 97.88151%2c2.98826245 Z M100.429182%2c10.3453244 C99.7920929%2c10.3453244 98.6240964%2c10.4262579 97.8808258%2c10.5341694 L97.8808258%2c19.9494429 C98.385188%2c20.0573544 99.4735484%2c20.1382879 100.429182%2c20.1382879 C102.712084%2c20.1382879 103.269537%2c18.4926384 103.269537%2c16.2804538 L103.269537%2c14.2031585 C103.269537%2c11.9909739 102.712084%2c10.3453244 100.429182%2c10.3453244 Z' id='Combined-Shape'%3e%3c/path%3e %3cpath d='M111.502687%2c8.72457747 C112.045508%2c8.72457747 112.570006%2c8.64485191 113.065463%2c8.49629404 L113.064781%2c16.5232546 C113.064781%2c19.3289521 114.073505%2c19.9764208 115.613137%2c19.9764208 L115.772409%2c19.9764208 C117.312041%2c19.9764208 118.320765%2c19.3289521 118.320765%2c16.5232546 L118.320226%2c8.4334735 C118.872544%2c8.62226395 119.463958%2c8.72457747 120.078886%2c8.72457747 C120.689352%2c8.72457747 121.276644%2c8.62374317 121.825517%2c8.43756894 L121.824755%2c16.5232546 C121.824755%2c22.4044283 117.338586%2c23.0518969 115.772409%2c23.0518969 L115.526483%2c23.0512514 C113.88817%2c23.0271041 109.560791%2c22.2994073 109.560791%2c16.5232546 L109.560465%2c8.36700801 C110.164542%2c8.59813531 110.819085%2c8.72457747 111.502687%2c8.72457747 Z' id='Combined-Shape'%3e%3c/path%3e %3cpath d='M128.780182%2c3.03790128 L128.779643%2c22.269539 C128.779643%2c22.5662954 128.56728%2c22.836074 128.275281%2c22.836074 L125.806561%2c22.836074 C125.514562%2c22.836074 125.275653%2c22.5662954 125.275653%2c22.269539 L125.275475%2c3.04219481 C125.82418%2c3.22824247 126.411273%2c3.32900525 127.021522%2c3.32900525 C127.63645%2c3.32900525 128.227864%2c3.22669173 128.780182%2c3.03790128 Z' id='Combined-Shape'%3e%3c/path%3e %3cpath d='M134.372549%2c3.32900525 C134.939348%2c3.32900525 135.48617%2c3.24208064 136.000812%2c3.08063296 L135.999985%2c22.269539 C135.999985%2c22.5662954 135.787622%2c22.836074 135.495623%2c22.836074 L133.026903%2c22.836074 C132.734904%2c22.836074 132.495995%2c22.5662954 132.495995%2c22.269539 L132.495929%2c2.99605058 C133.081688%2c3.21152525 133.713619%2c3.32900525 134.372549%2c3.32900525 Z' id='Combined-Shape'%3e%3c/path%3e %3c/g%3e %3c/g%3e %3c/g%3e %3c/g%3e%3c/svg%3e)




A self-directed RRSP gives Canadian investors direct control over the assets held within their Registered Retirement Savings Plan. Rather than relying solely on a financial institution to manage a limited menu of products, account holders can build a diversified portfolio across multiple asset classes. If you're exploring how to open a self-directed RRSP in Canada, this guide covers eligibility, qualified investments, fees, and regulatory protections.
Key Takeaways
A self-directed RRSP lets you hold US and Canadian stocks, ETFs, and US options contracts.
You must be a Canadian resident with earned income and a valid SIN; the account must be converted by December 31 of the year you turn 71.
Platforms such as Webull Canada offer self-directed RRSP accounts with access to Canadian and U.S. markets.
CIRO membership and CIPF coverage (subject to limits and conditions) provide a layer of regulatory oversight.
Part 1. What Is a Self-Directed RRSP and How Does It Work?
1.1 Definition and Core Concept
A self-directed RRSP, is a type of Registered Retirement Savings Plan that places investment decision-making in the hands of the account holder. Instead of a financial institution automatically allocating contributions into a preset product, you select and manage the individual assets yourself.
The issuer, such as a bank, brokerage, credit union, or trust company, still handles administrative responsibilities. These include registering the plan, receiving contributions, and executing trades.
Canada Revenue Agency — https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans/contributing-a-rrsp-prpp/self-directed-rrsps.html
1.2 RRSP vs. Self-Directed RRSP: Key Differences
Feature | Standard RRSP | Self-Directed RRSP |
|---|---|---|
Investment control | Institution-managed | Account holder-directed |
Asset variety | Limited to the provider's menu: cash, GICs, and mutual funds | Broad: stocks, ETFs, and other exchange-traded securities |
Management style | Hands-off | Self-directed only (no active management or robo-advisory) |
Complexity | Lower | Higher — requires investment knowledge |
Fees | Varies | May include trading, administrative, regulatory, and exchange fees, plus MERs on ETFs and mutual funds |
1.3 Who Manages a self-directed RRSP?
With a self-directed RRSP, you manage the investments yourself through a DIY online brokerage. You select and trade investments independently through a platform, with no active management or robo-advisory service.
Part 2. Eligibility and Qualified Investments for a Canadian SDRSP
2.1 Who Can Open a Self-Directed RRSP in Canada?
To open an RRSP account at Webull Canada, you must meet the following criteria:
Be at the age of majority in your province of residence, up to the end of the year you reach age 71.
Hold a valid Social Insurance Number (SIN).
Be a Canadian resident for purposes of filing an income tax return in Canada with earned income to contribute.
Webull Canada — https://www.webull.ca/tfsa-rrsp
2.2 Qualified Investments Permitted in a self-directed RRSP
The CRA defines which assets may be held in a registered plan. Common qualified investments for an RRSP trust include:
Most securities listed on a designated stock exchange (including Canadian and U.S. equities and ETFs, and options contracts)
Holding non-qualified investments in an RRSP may carry regulatory and financial consequences. Always verify an asset's eligibility before purchasing it within a registered account.
Canada Revenue Agency — https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans/contributing-a-rrsp-prpp/self-directed-rrsps.html
2.3 Contribution Limits to Know
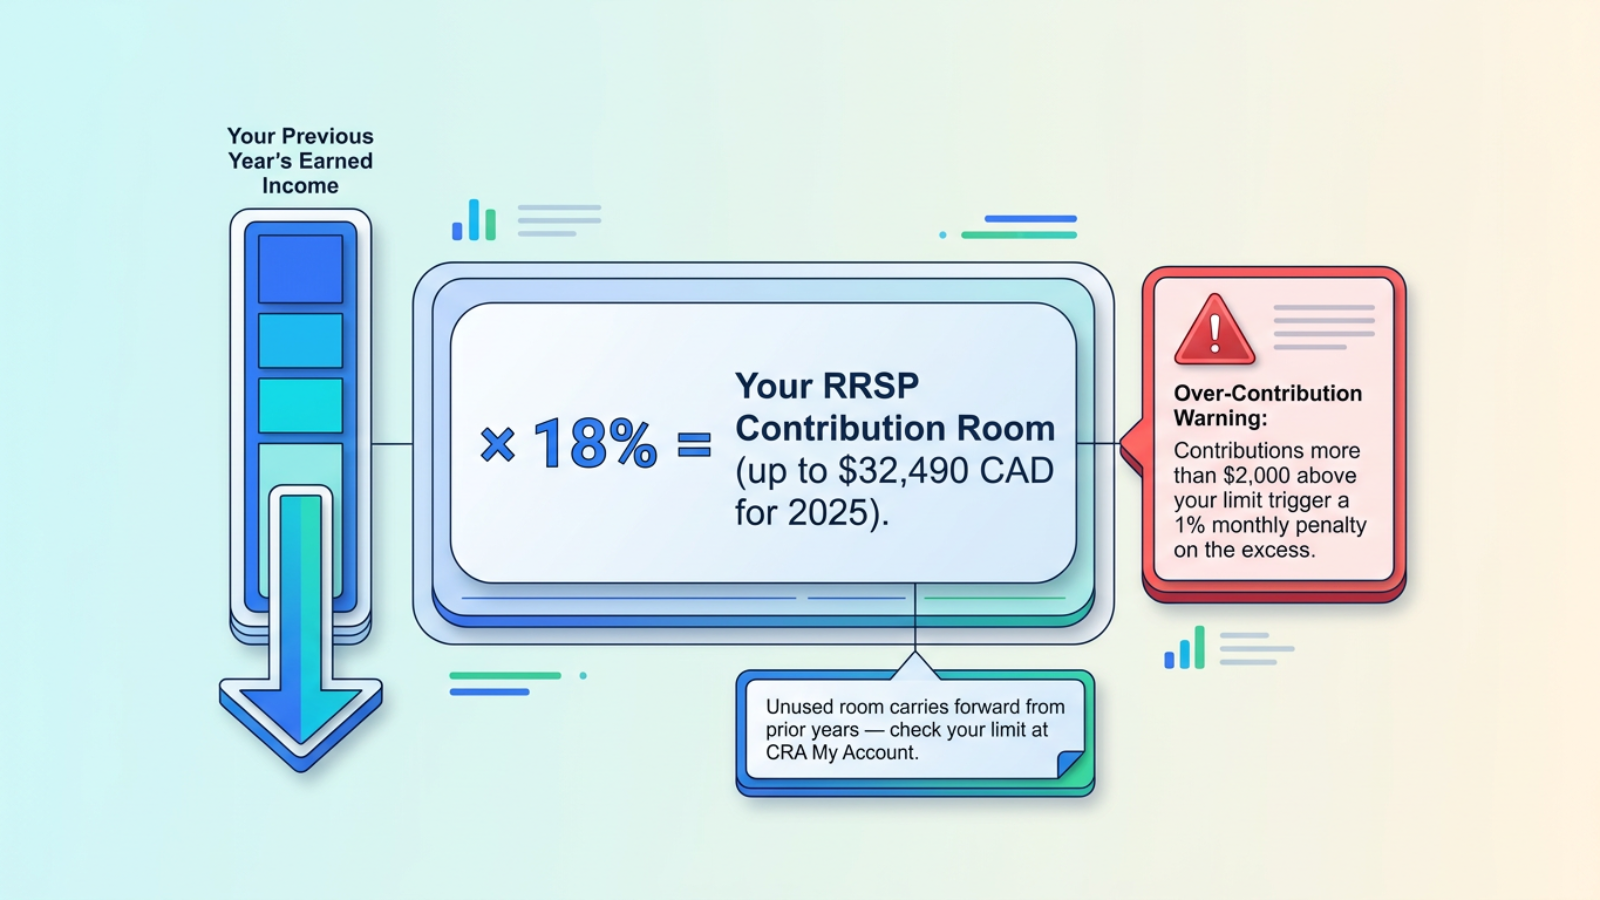
RRSP contribution room is calculated as 18% of your previous year's earned income, up to an annual dollar cap. For the 2026 tax year, that cap is $33,810 CAD (rising to $35,390 CAD for 2027). Unused contribution room from prior years carries forward.
If you over-contribute to your RRSP by more than $2,000, a penalty of 1% per month applies to the excess amount for each month it remains in the plan. Confirm your available room through your CRA My Account before making large deposits.
Part 3. Opening a Self-Directed RRSP on Webull Canada
Webull Securities (Canada) Limited is a CIRO investment dealer member, offering self-directed RRSP accounts alongside TFSA and non-registered accounts. The platform is designed for investors who want direct market access with a digital-first experience.
3.1 Step-by-Step: How to Open an RRSP on Webull Canada
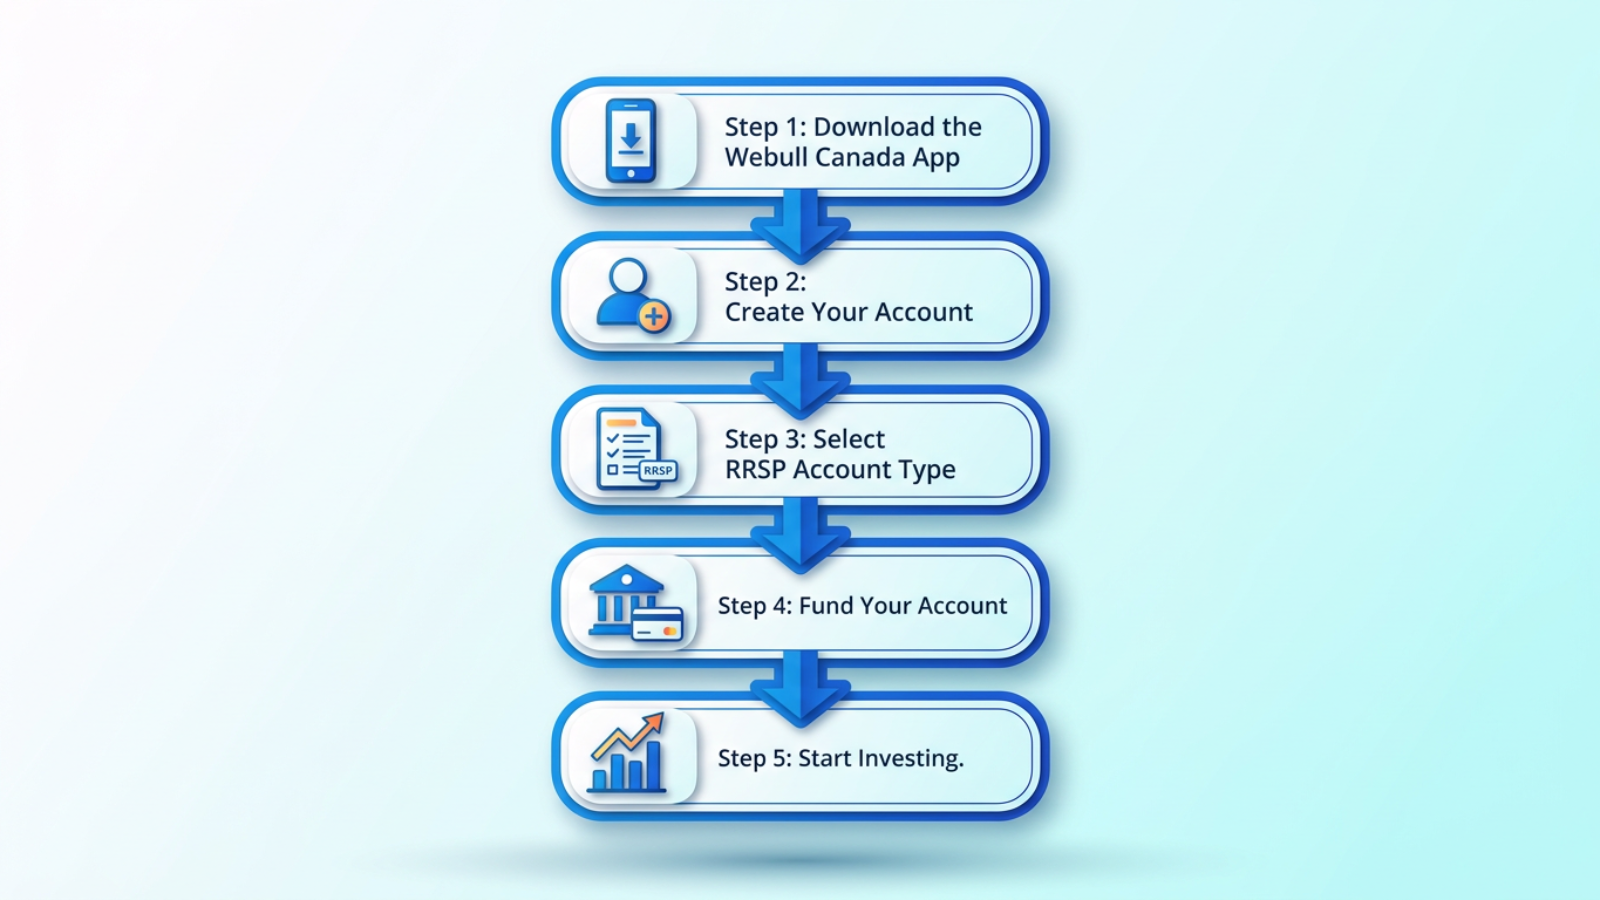
Step 1 — Download the Webull Canada app or visit the official website at webull.ca.
Step 2 — Create your account. Provide your full legal name, date of birth, SIN, and Canadian residential address for identity verification, along with other regulatory details such as your employment, financial situation, and investment objectives.
Step 3 — Select RRSP as your account type during the account setup process.
Step 4 — Fund your account by linking an external Canadian bank account and initiating a deposit in CAD.
Step 5 — Begin investing. Once funded, you can search for and purchase qualified investments, including Canadian and U.S.-listed equities and ETFs.
3.2 Webull Canada Platform Features for RRSP Investors
Webull Canada offers a range of tools that may be useful for self-directed RRSP investors:
Real-time market data — Access live quotes for Canadian and U.S. markets.
Advanced charting tools — Technical analysis features to support equity research.
Mobile and desktop platforms — Seamless access across devices for on-the-go portfolio management.
Access to Canadian and U.S. markets — Trade equities and ETFs listed on major North American exchanges within a single registered account.
Rates vary by service provider; please refer to the latest pricings.
Webull Canada — https://www.webull.ca
3.3 Fees and Costs to Consider on Webull Canada
When evaluating any self-directed RRSP platform, fee transparency matters. Potential costs to review include:
Trading commissions — Confirm current commission structures directly with Webull Canada.
Foreign exchange conversion fees — Applicable when trading U.S.-listed securities in USD from a CAD-denominated account.
Regulatory and exchange fees — These may apply on top of any stated commission.
Always review the full fee schedule before opening an account. Rates vary by service provider; please refer to the latest pricings.
3.4 Regulatory Oversight and Investor Protection
Webull Securities (Canada) Limited is a member of the Canadian Investment Regulatory Organization (CIRO), Canada's national self-regulatory organization for investment dealers. Client accounts are generally within the scope of Canadian Investor Protection Fund (CIPF) coverage, subject to coverage limits and conditions.
Important: CIPF coverage does not protect against market losses or guarantee account value. Coverage applies to the insolvency of a CIRO member firm, not to investment performance. Certain products may fall outside standard CIPF coverage. Investors should review CIPF's coverage policy directly.
CIRO — https://www.ciro.ca
CIPF — https://www.cipf.ca
Part 4. Key Factors When Choosing a Self-Directed RRSP Platform in Canada
When selecting a platform for a self-directed RRSP, Canadian investors typically evaluate several factors. The following criteria provide a practical framework for making an informed decision, without relying on subjective comparisons between providers.
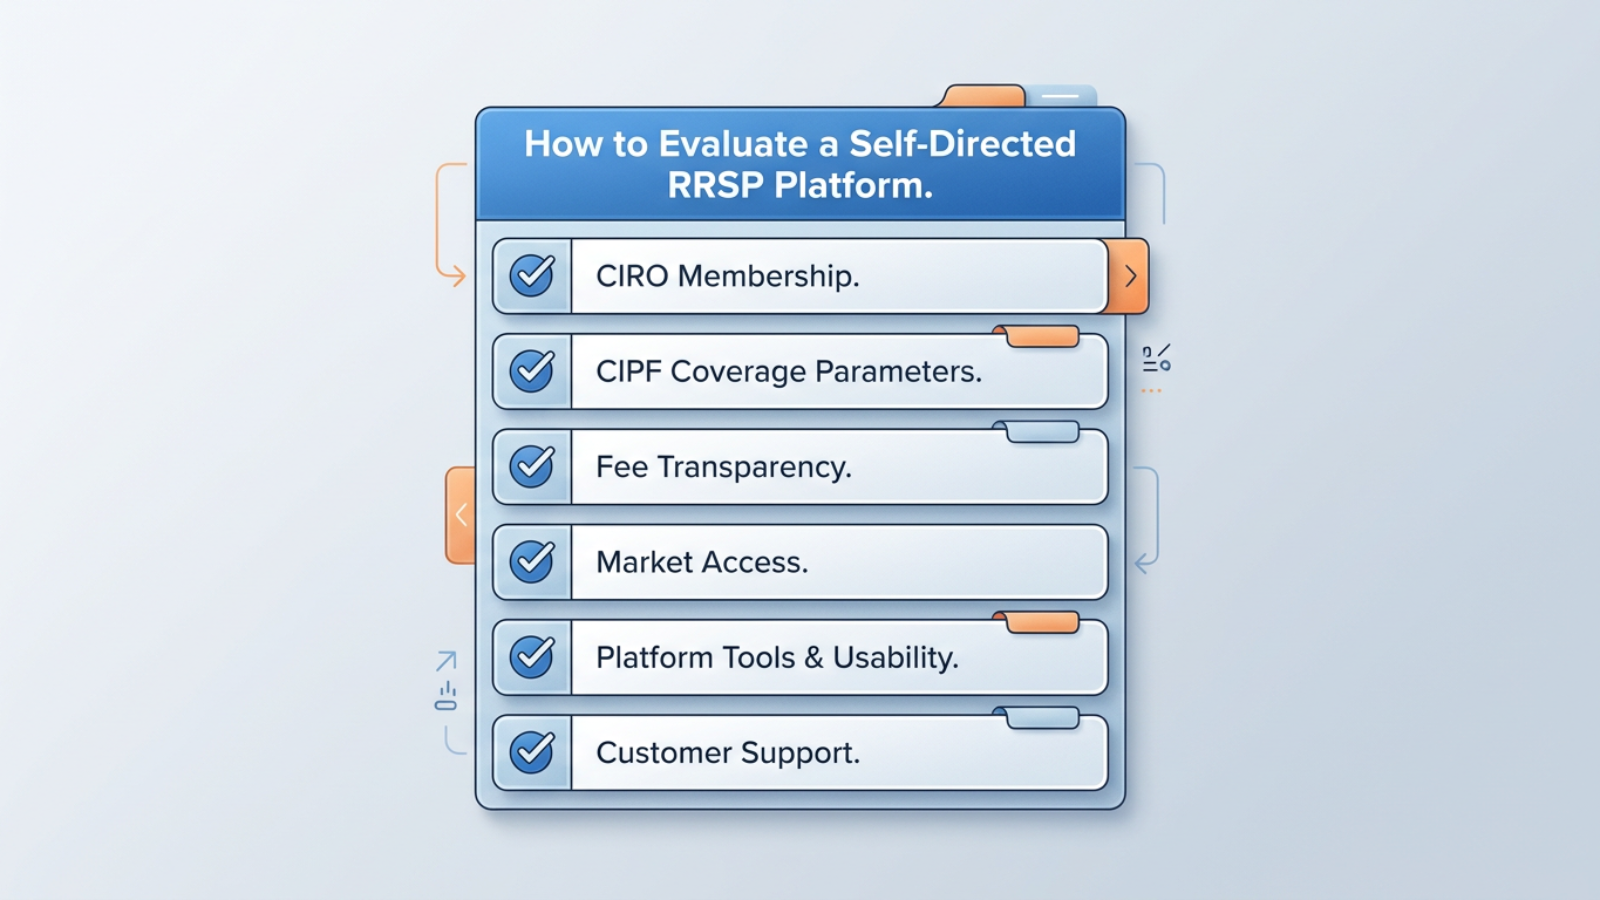
CIRO membership and regulatory standing — Confirm that any platform you consider is a registered CIRO investment dealer. This ensures the firm operates under Canada's national self-regulatory framework for investment dealers. Webull Securities (Canada) Limited holds CIRO investment dealer membership.
CIPF coverage parameters — Client accounts at CIRO member firms are generally within the scope of CIPF coverage, subject to limits and conditions. Coverage does not protect against market losses. Verify coverage details directly with CIPF before opening an account.
Fee transparency — Evaluate all-in costs, including trading commissions, foreign exchange conversion fees, account maintenance fees, and MERs on any funds held. Rates vary by service provider; please refer to the latest pricings.
Market access and account types — Consider whether the platform supports both Canadian and U.S. market access within a registered RRSP account, and whether it also offers TFSA and non-registered accounts for a consolidated portfolio view. Webull Canada supports all three account types, as well as margin accounts.
Platform tools and usability — Assess the quality of research tools, charting capabilities, real-time data access, and mobile platform functionality. Webull Canada provides real-time market data, advanced charting tools, and access to both Canadian and U.S. markets within a digital-first platform designed for self-directed investors.
Customer support and account services — Consider the availability and responsiveness of support channels, particularly for registered account inquiries.
Investors are encouraged to compare offerings directly and consult a qualified financial advisor before making a platform decision. Past performance is not indicative of future results. Actual results may vary by individual.
Part 5. Investment Strategy Considerations for a Self-Directed RRSP
5.1 Asset Placement: RRSP vs. TFSA
One consideration for investors holding both an RRSP and a TFSA is asset location — which investments to hold in which account. This is a structural consideration worth understanding.
U.S.-listed dividend-paying stocks and ETFs may be more efficiently held in an RRSP. Under the Canada-U.S. tax treaty, RRSPs are recognized as pension accounts, which may affect how certain withholding applies to U.S.-sourced income. TFSAs do not receive the same treaty recognition from U.S. authorities.
For growth-oriented U.S. equities that pay little or no dividends, the distinction may be less material. Investors should consult a qualified financial advisor for guidance specific to their situation.
5.2 Risk Awareness for Self-directed RRSP Investors
Self-directed investing carries meaningful risks that every investor should understand before opening an SDRSP:
Market risk — The value of equities, ETFs, and other securities can decline. There is no guarantee of capital preservation.
Concentration risk — Holding too few assets or sectors increases portfolio volatility.
Liquidity risk — Some investments may be harder to sell quickly at a fair price.
Over-contribution risk — Contributing more than $2,000 above your RRSP limit triggers a 1% monthly penalty on the excess amount until it is withdrawn.
Webull Securities (Canada) Ltd. is regulated by CIRO and a member of CIPF. Brochures are available at ciro.ca and cipf.ca. Options are risky and not appropriate for all investors.
Options trading entails significant risk and is not appropriate for all investors. Option investors can rapidly lose the value of their investment in a short period of time and incur permanent loss by expiration date. Losses can potentially exceed the initial required deposit. You need to complete an options trading application and get approval on eligible accounts. Please read the Derivatives Disclosure Document before trading options, available at www.webull.ca.
5.3 Pros and Cons of a Self-Directed RRSP
Pros:
Greater investment flexibility across multiple asset classes
Potential to build a more diversified portfolio than a standard RRSP
Access to Canadian and U.S. markets through a single registered account
Choice of management style
Cons:
Requires more investor knowledge and active involvement
Non-qualified investments may carry regulatory consequences
The Bottom Line
A self-directed RRSP may suit Canadian investors who want greater control over their retirement portfolio and access to a broader range of qualified investments. Webull Canada offers a CIRO-regulated platform with tools designed for self-directed investors. Before opening an account, compare fees, confirm eligibility, and consider consulting a qualified financial advisor to ensure the approach aligns with your individual goals and risk tolerance.
Disclosure:
Webull Securities (Canada) Ltd. is regulated by CIRO and a member of CIPF. Brochures are available at ciro.ca and cipf.ca. Options are risky and not appropriate for all investors.
Options trading entails significant risk and is not appropriate for all investors. Option investors can rapidly lose the value of their investment in a short period of time and incur permanent loss by expiration date. Losses can potentially exceed the initial required deposit. You need to complete an options trading application and get approval on eligible accounts. Please read the Derivatives Disclosure Document before trading options, available at www.webull.ca.
