


3 Eurozone Financial Stocks to Watch as ECB Policy Shifts
ECB politics just got real for your portfolio. A new leadership mix in Frankfurt, with inflation at 4% and questions swirling around high French debt, can reshape how eurozone banks and insurers are priced almost overnight. Periods of policy uncertainty often encourage investors to look past the headlines and focus on underlying fundamentals. This article walks through 3 eurozone financial stocks to illustrate how this new ECB era could matter for you.
The stocks in the list below are just a sample, and the full screen surfaced 13 more eurozone banks and insurers with equally compelling stories that are not covered here. To identify and analyze the highest conviction opportunities that are most sensitive to this ECB setup, head straight into the Eurozone Financials (Banks and Insurers) screener.
Allianz (XTRA:ALV)
Overview: Allianz is a large Munich based insurer and asset manager, offering property, life, health and investment products to clients worldwide.
Operations: Most revenue comes from Property Casualty at about €82.6b, with Life Health at roughly €25.8b and Asset Management contributing about €9.4b.
Market Cap: €168.9b
Allianz sits near the center of this eurozone financials theme because its insurance and investment engines are tightly linked to ECB rate decisions and bond markets. The analyst consensus Narrative on Simply Wall St describes how management aims to translate that rate exposure into a durable earnings profile.
"Ongoing digital transformation and AI driven operational efficiencies are set to drive sustained improvements in expense ratios and underwriting profitability, supporting higher net margins and overall earnings growth."
The key issue now is how a relatively quiet shift in the balance between fee income and traditional underwriting eventually affects margins.
As that mix of underwriting and fees keeps shifting, full narrative for Allianz shows how Allianz could turn this rate backdrop into accelerating cash generation while cushioning the policy cycle.

Banco Bilbao Vizcaya Argentaria (BME:BBVA)
Overview: Banco Bilbao Vizcaya Argentaria is a large Spanish bank that provides retail, corporate, investment and digital banking across Europe and key emerging markets, directly tying its earnings to ECB policy and eurozone funding conditions.
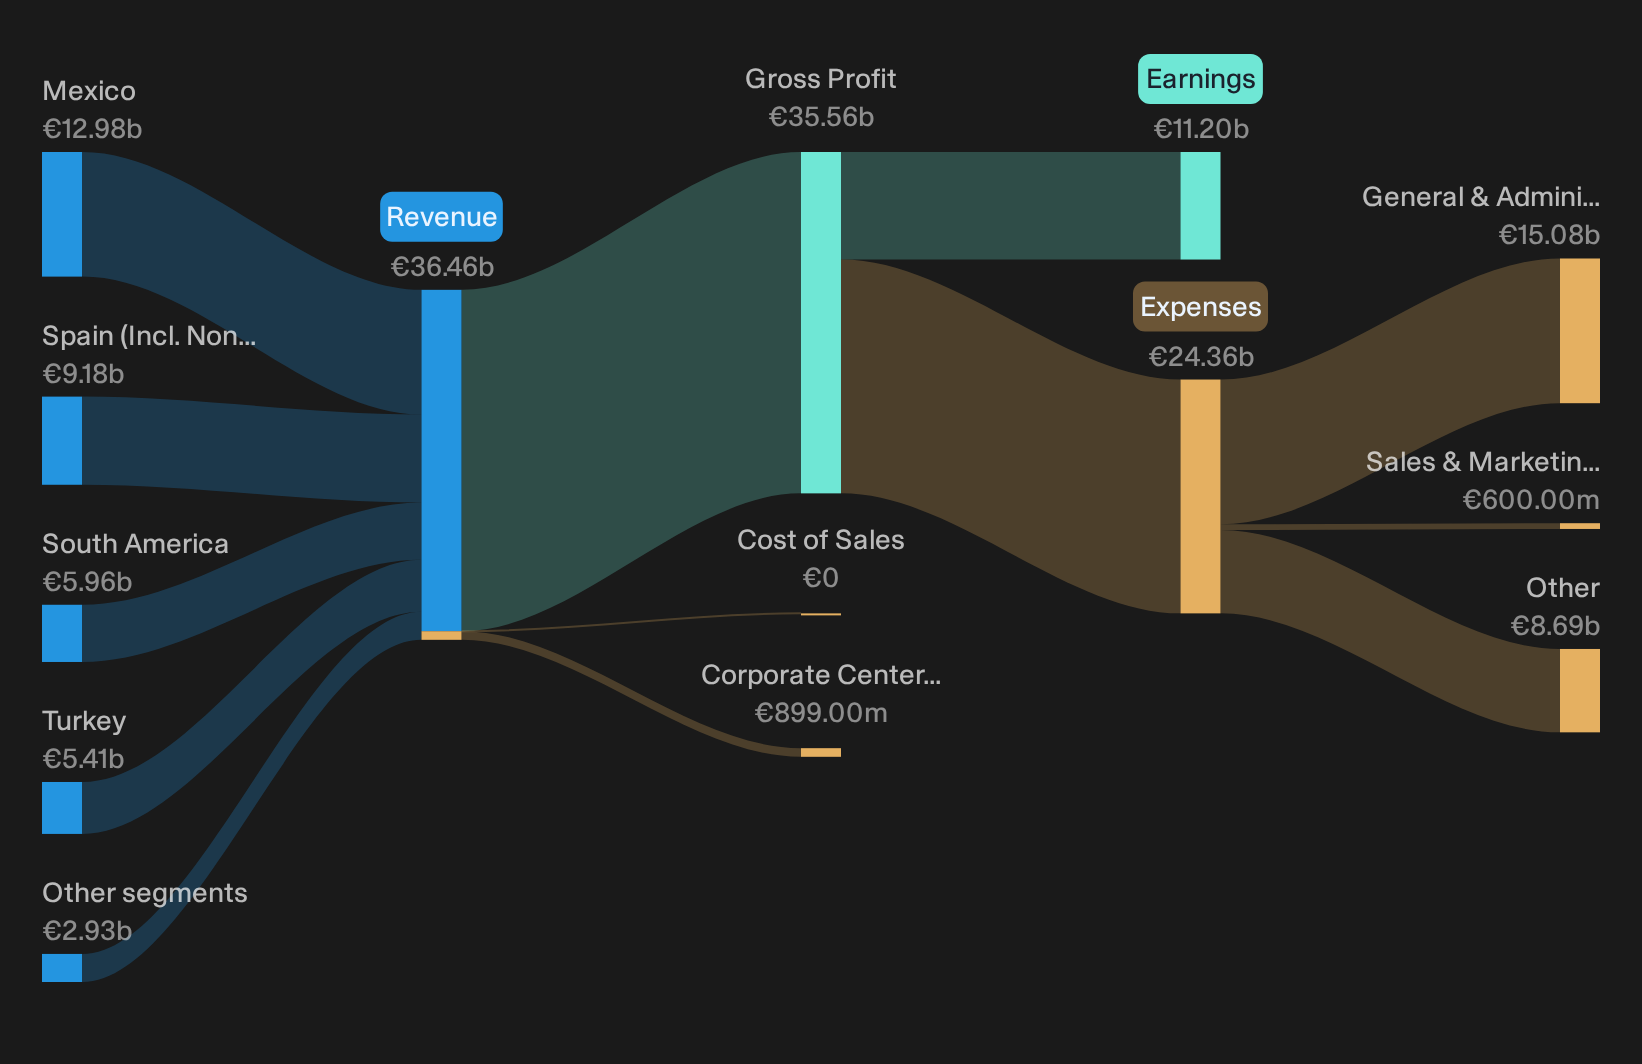
Operations: BBVA earns most of its revenue in Mexico at about €13b and Spain at roughly €9.2b, with sizeable contributions from Turkey and South America.
Market Cap: €118.9b
BBVA is one of the clearest ECB sensitive stories in this screener. Its Spanish and wider eurozone book turns policy decisions into real movements in net interest income and funding costs, a link the analyst consensus Narrative on Simply Wall St leans on heavily.
"Ongoing investment and leadership in digital transformation is now reinforced by concrete AI programs that already support contact centers, risk processes and software development."
The real test for Banco Bilbao Vizcaya Argentaria is how much of that efficiency push ends up in margins versus pricing pressure if one key macro assumption shifts.
If that balance tips the right way, full narrative for Banco Bilbao Vizcaya Argentaria maps how Banco Bilbao Vizcaya Argentaria could turn digital efficiency into accelerating earnings resilience and re rating potential.
Banco Santander (BME:SAN)
Overview: Banco Santander is a large Madrid based bank that provides retail, corporate, investment, wealth and payments services across global markets.
Operations: Retail and Commercial Banking generates about €27.9b, with Corporate and Investment Banking at roughly €9.1b and Openbank contributing about €9.0b.
Market Cap: €147.9b
For the Eurozone Financials screener, Banco Santander matters because its broad deposit base and loan book turn ECB rate and bond spread moves directly into shifts in earnings power. This is exactly what Bo_Shine, a Simply Wall St Community investor who wrote the Narrative, focuses on when assessing recent developments.
"Hausse du coût du risque : Le coût du risque (qui mesure les pertes potentielles sur les crédits) a bondi de 11 points de base par rapport au trimestre précédent pour s'établir à 4,25 %."
What happens if a single pressure on credit quality or funding costs moves further than expected will do a lot to shape future margins.
When that pressure builds, full narrative for Banco Santander shows how Banco Santander could turn shifting risk costs into accelerating earnings power and reveal what the headline numbers may be masking.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout themes can gain momentum while attention is still elsewhere and the best entry points get caught early. Scan what is flying under the radar for now and act now.
- Spot established payouts that could steady overall returns by reviewing the 245 dividend fortresses before yields drop and the crowd starts chasing the same income plays.
- Track the next wave of automation leaders by checking the curated 90 robotics and automation stocks while valuations still reflect early stage adoption rather than full market enthusiasm.
- Position ahead of potential infrastructure momentum by using the focused 41 power grid technology and infrastructure stocks and assess which suppliers might benefit if grid spending accelerates.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com