


ASML Holding (ENXTAM:ASML) Dropped, What Is Drawing Attention Now?
ASML Holding stock reacts to Nvidia leadership shake-up
Nvidia’s CEO exit pulled much of the chip sector lower, yet ASML Holding (ENXTAM:ASML) was little changed as traders weighed its role in semiconductor equipment against the broader selloff.
This muted move gives you a clear starting point to compare ASML’s recent price performance, business results, and ETF flows with the more volatile swings hitting many chip designers.
Over the past month the share price has slipped, with a 30 day share price return of down 12.39% and a 90 day move of down 15.24%. However, ASML Holding still shows stronger longer term momentum with a 35.74% year to date share price return and a 1 year total shareholder return of 54.10%.
Recent headlines around record quarterly results, tight supply into 2027 and 2028, and fresh buying from the SOXX ETF have kept attention on ASML Holding. At the same time, the sharp reaction to Nvidia’s leadership change highlights how quickly risk perceptions around AI exposed chip stocks can shift.
Spot similar AI hardware stories in motion by scanning the hand picked 53 AI infrastructure stocks that could sit alongside ASML Holding in the next leg of the semiconductor cycle.Bulls point to record results, scarce EUV supply and ETF buying. Bears argue the recent pullback barely dents a rich multiple. Which side do the current valuation markers back up for ASML Holding?
Most Popular Narrative: 25% Undervalued
Against a last close of €1,338.80, the leading narrative on ASML Holding puts fair value at €1,780. This points to a clear valuation gap and sets up a debate about how much risk is already in the price.
According to Ivoed, an investor in the Simply Wall St Community who wrote the narrative, the key question is whether that gap is justified by long term execution and China risk, or whether investors are overreacting in the short term.
The more important issue is therefore not whether China immediately replaces ASML. It is whether the probability of long-term substitution is now high enough to raise ASML’s required return and lower the terminal multiple investors are willing to pay. A DCF is particularly sensitive to that question because most of ASML’s value comes from cash flows expected after the explicit forecast period. In my base model, the terminal value represents about 85% of enterprise value. Small changes to the discount rate or terminal growth assumption therefore have a large effect on fair value.
See why 52 investors see ASML Holding as 25% undervalued.
The narrative uses a discount rate of 9.20% and arrives at a fair value of €1,780, which implies ASML Holding trades at a 24.8% discount based on that framework. The closing price of €1,338.80 therefore prices in a wider margin for execution, export control and competition risk than this view suggests, even though the same analysis also flags that a large share of estimated worth comes from cash flows far into the future.
In practical terms, that means this approach describes more upside than downside from today’s quote. It also leans heavily on ASML Holding maintaining high earnings quality, strong return on equity and sustained revenue growth. Any reset in those expectations, or a shift in how investors think about long dated cash flows, could move that fair value number meaningfully even if near term reported results stay solid.
Result: Fair Value of €1,780 (UNDERVALUED)
Still, the narrative could crack if export controls tighten further or Chinese lithography suppliers scale faster than expected and investors reset the multiple that ASML Holding commands.
Find out about the key risks to this ASML Holding narrative.
Another View: ASML Holding through a DCF lens
The Simply Wall St DCF model tells a very different story to the community narrative. On that framework, ASML Holding at €1,338.80 trades above an estimated future cash flow value of €1,019.57. This points to the shares looking expensive rather than undervalued. For investors, that gap raises a blunt question: Is the market correctly pricing long term cash generation, or are expectations running ahead of what the balance of cash flows can reasonably support?
Look into how the SWS DCF model arrives at its fair value.
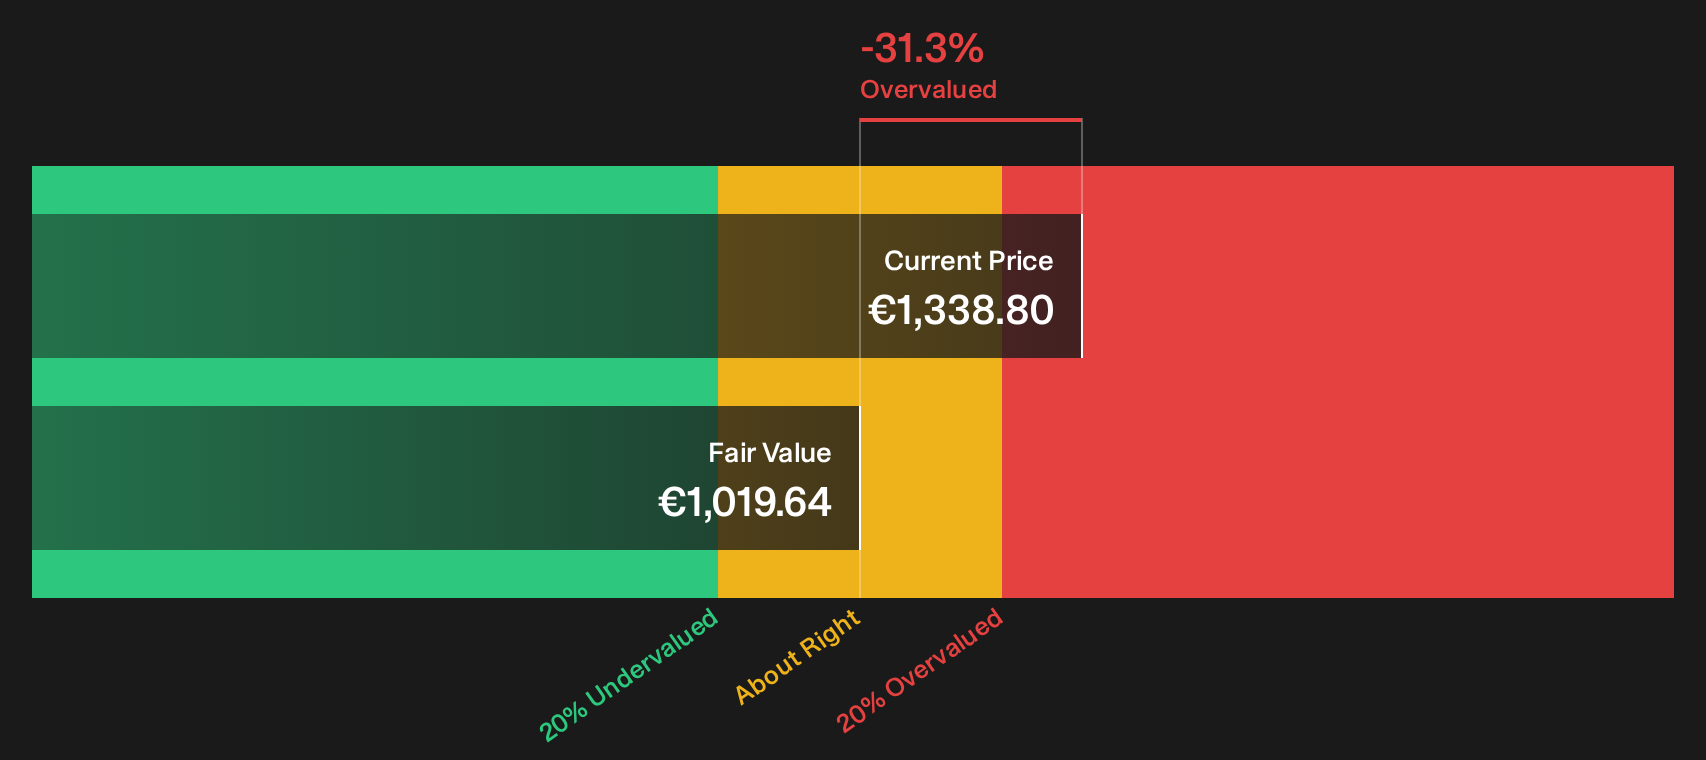
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ASML Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 196 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around ASML Holding and the wider chip trade create plenty of room for debate. Move quickly, pull up the data, and pressure test your own thesis against the 4 key rewards and 1 important warning sign.
Ready for more ASML Holding style ideas?
If you stop at ASML Holding, you risk missing other setups where quality, valuation, and risk all line up in your favor. Put fresh ideas on your radar now using focused screeners that surface stocks by strength, not hype.
- Target potential bargains early by scanning companies that combine solid fundamentals with attractive pricing through the 562 high quality undiscovered gems.
- Build staying power into your portfolio by using the 210 resilient stocks with low risk scores to narrow in on businesses with more resilient risk profiles.
- Fortify your income stream by filtering for higher yielding payers with durable fundamentals using the 220 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com