


What Is Drawing Fresh Attention To Planet Labs PBC (PL)?
Planet Labs PBC (PL) just released the first light image from its new Pelican-12 high resolution satellite, giving investors a fresh data point on how the earth-imaging fleet is evolving.
The recent Pelican-12 milestone lands at a tricky moment for Planet Labs PBC’s stock, with the share price down 16.94% over the past 30 days and 41.76% over 90 days, yet supported by a 1-year total shareholder return of 14.43% and a very large 3-year total shareholder return of roughly 5x. This suggests that earlier optimism is now being reassessed as investors weigh fresh defense contracts, launch agreements with Stoke Space, and the upcoming fiscal Q3 2027 earnings release against execution risk at a US$14.27 share price.
Spot 53 AI infrastructure stocks that, like Planet Labs PBC, are building the data and compute backbone behind defense, imaging, and AI workloads.So is Planet Labs PBC’s recent slide a verdict on the business, or just sentiment cooling after a very strong three year run and fresh contract news? And what does that imply for valuation next?
Most Popular Narrative: 54% Undervalued
Planet Labs PBC closed at $14.27 while the most followed narrative on Simply Wall St sets fair value at $31.00 using a 7.53% discount rate. This frames the recent pullback as a large gap between price and what some investors think the business could be worth. According to John_Eric, an investor in the Simply Wall St Community who wrote the narrative, the key question is what future this current quote already assumes.
The stock fell from $51.76 to roughly $16 in under four months, a 68% collapse that looks like it should come with wreckage. I went looking for the disaster. Instead I found something that changed how I think about what this company actually is.
See why 66 investors see Planet Labs PBC as 54% undervalued.
Result: Fair Value of $31.00 (UNDERVALUED)
Still, two pressure points hang over the Planet Labs PBC story: dependence on government contracts and the risk that AI platforms treat its imagery as a commodity feed.
Find out about the key risks to this Planet Labs PBC narrative.
Another View: SWS DCF Model Points The Other Way
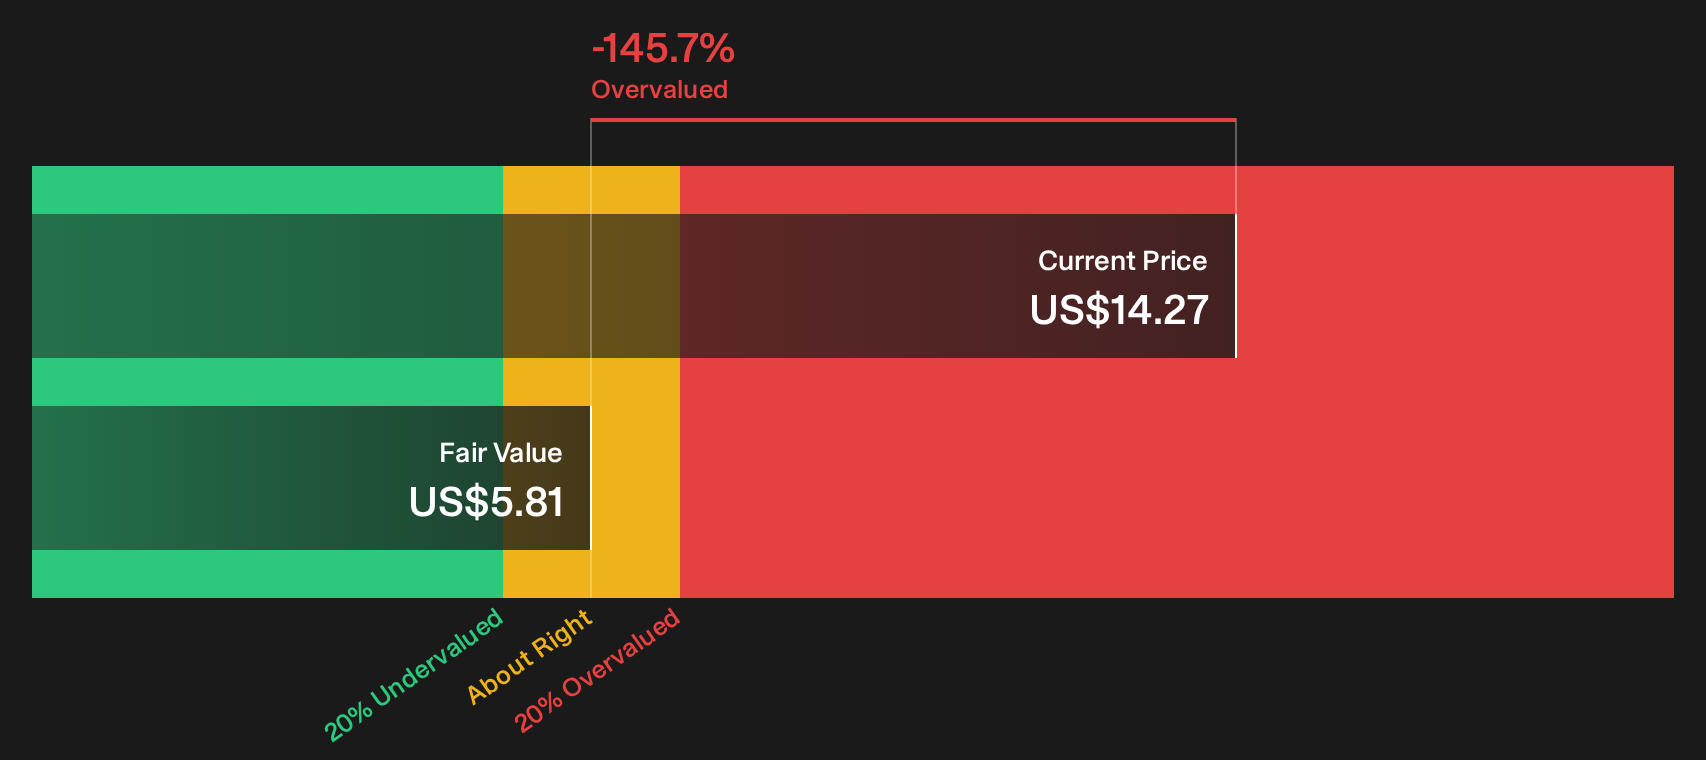
Planet Labs PBC may look cheap against a $31.00 community fair value, yet the SWS DCF model points in the opposite direction. It values future cash flows at $5.81 per share, well below the current $14.27 price, which leans more toward valuation risk than upside. Which story do you trust more: the narrative or the cash flow math?
To see how those assumptions stack up in detail, and what would need to change for that DCF view to shift, Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the mixed tone in this Planet Labs PBC story leaves you torn, move quickly, review the data, and weigh both sides for yourself using the 1 key reward and 2 important warning signs.
Hunting For More Ideas Beyond Planet Labs PBC?
Do not stop your research with one stock. Use the Simply Wall St screener to spot other opportunities that could fit your risk, return, and income goals.
- Target resilient income by reviewing 5 dividend fortresses that might add steadier cash flows alongside higher volatility holdings.
- Upgrade portfolio quality with a list of solid balance sheet and fundamentals (24 results) so you are not caught holding businesses with fragile finances when conditions change.
- Get ahead of the crowd by scanning 20 high quality undiscovered gems before attention and liquidity potentially shift toward them.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com