


Profit Jump Might Change The Case For Investing In Cathay Pacific Airways Shares
- Cathay Pacific Airways reported a 71% rise in half-year profit with net margin at 9.2%, achieved despite higher war driven fuel costs and ongoing geopolitical risks.
- The halted restart of Middle East cargo routes leaves a clear operational gap, yet current profitability suggests the airline is extracting more earnings from each available seat and tonne of freight.
- We will look at how Cathay Pacific Airways’ sharply higher half-year profit and 9.2% net margin reshape its investment narrative.
Cathay Pacific Airways Investment Narrative Recap
For Cathay Pacific Airways to make sense in a portfolio, you need to be comfortable with a business that is currently earning a 9.2% net margin while fuel costs are elevated and some routes are offline. The short term swing factor is how long that margin strength can coexist with war driven fuel prices and disrupted cargo corridors.
The biggest operational risk right now sits in that mix of fuel and route exposure. If hedging and surcharges do not fully offset high jet fuel, or if Middle East suspensions extend into wider cargo flows, the recent 71% half year profit uplift may prove less helpful as a guide to the next few reporting periods.
The analyst consensus Narrative on Simply Wall St highlights Cathay Pacific Airways’ plan to add 150 new aircraft and eventually ramp the network from 103 to 150 destinations. That investment case leans on capacity expansion and premium product upgrades as the engines of future earnings, even as current forecasts point to modest revenue growth and declining earnings over the next three years.
This latest margin print matters because it tests whether that large capital plan can sit alongside resilient profitability when fuel is expensive and some geographies are closed. For you as a shareholder, the question is whether a 9.2% net margin is compatible with long haul expansion, cargo fleet growth and HK Express losses without eroding the quality of those future cash flows.
Cathay Pacific Airways’ current analyst script points to HK$149.4b in revenue and HK$13.0b in earnings by 2029, based on 4.6% yearly revenue growth and an earnings decline of HK$0.4b from HK$13.4b today.
Uncover how Cathay Pacific Airways' fair value indicates a 3% potential upside to its current price, which could narrow quickly.
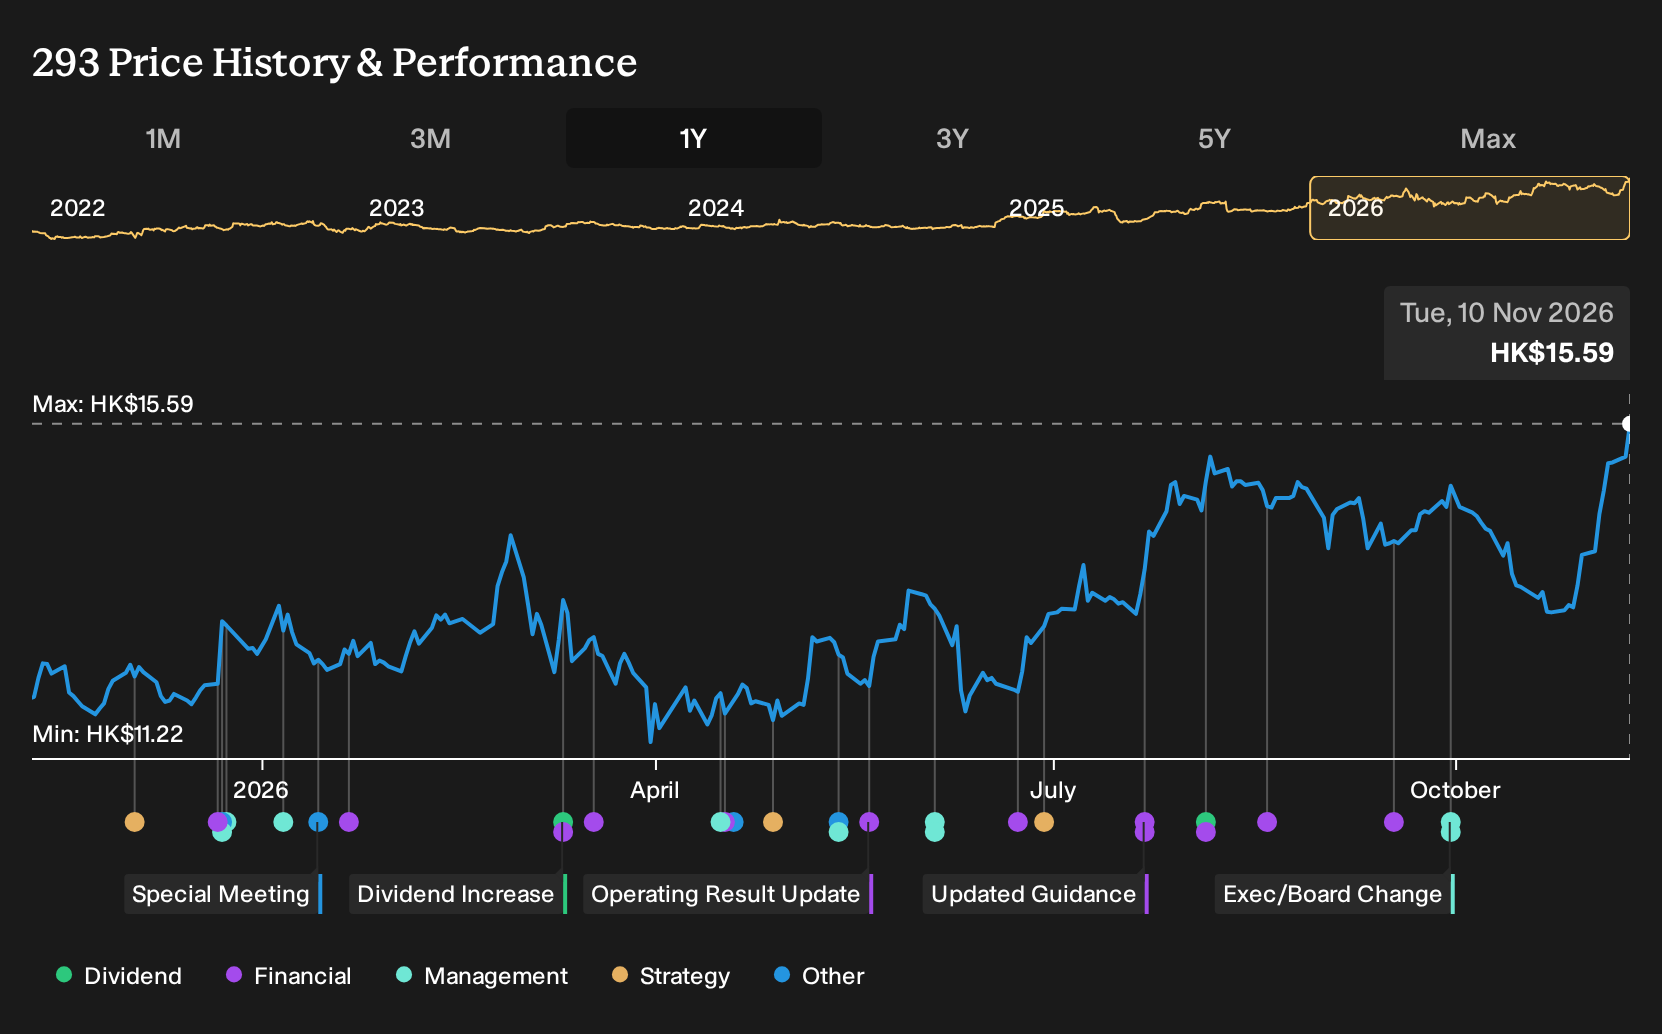
Exploring Other Perspectives
You are not the only one asking whether Cathay Pacific Airways’ higher jet fuel exposure is the real story. The most bearish analysts were already assuming revenue would slide to about HK$123.7b and earnings to HK$9.2b by 2029, well below consensus. Their harsher fuel and cost view may look different once this profit jump is fully digested.
Explore 4 other Cathay Pacific Airways fair value estimates, including one that suggests as much as 25% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cathay Pacific Airways research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cathay Pacific Airways. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cathay Pacific Airways' overall financial health at a glance.
Looking for more Cathay Pacific Airways sized investment ideas?
If Cathay Pacific Airways has sharpened your focus on margins, risk and cash generation, use that same checklist to scan a wider watchlist with the Simply Wall St Screener.
- If you want potential mispricing with quality fundamentals, start by reviewing 204 high quality undervalued stocks that may already be reflecting tougher fuel costs and route risk.
- If capital preservation matters more than headline returns, filter for 202 resilient stocks with low risk scores that combine sturdier balance sheets with less volatile profiles.
- If you prefer companies that quietly compound away from the market spotlight, look through 573 high quality undiscovered gems that still show strong underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com