


WEC Energy Group (WEC) Lifts Guidance As Fair Value Comes Back Into Focus
WEC Energy Group (WEC) just paired strong third quarter and year to date 2026 results with higher earnings guidance, a combination that tends to sharpen investor focus on the stock’s risk and return trade off.
Recent financial updates and capital markets activity have come alongside a strong 30 day share price return of 14.66% and an 11.13% year to date share price gain, while total shareholder return over 3 years sits at 65.42% and 56.42% over 5 years. This suggests momentum has been building rather than fading around WEC Energy Group despite the recent follow on equity and fixed income offerings.
Compare WEC Energy Group’s recent momentum with a curated 32 resilient stocks with low risk scores that shares a similar focus on regulated earnings and balance sheet resilience.
After this kind of run and with WEC Energy Group now trading almost level with the average analyst target, the real puzzle is where fair value sits within a broader range of intrinsic estimates.
Most Popular Narrative: Fairly Valued
WEC Energy Group closed at $118.32, almost in line with the most followed fair value estimate of $118.91 that uses a 7.24% discount rate and incorporates the long range earnings and dividend framework analysts are working from.
The capital investment plan at WEC Energy Group continues to grow, with a record US$37.5b program from 2026 to 2030 and an expectation of about US$1.1b of common equity issuance in 2026, along with a 50% equity content target for any incremental capital. This increases exposure to financing costs and share dilution and could weigh on earnings per share growth and net margins if market conditions or investor appetite weaken.
See why 16 investors see WEC Energy Group as 0% undervalued.
Result: Fair Value of $118.91 (ABOUT RIGHT)
Still, the WEC Energy Group story leans heavily on successful execution of its US$37.5b capital plan and on stable regulatory outcomes in Wisconsin and Illinois, both of which could shift.
Find out about the key risks to this WEC Energy Group narrative.
Another View: What WEC Energy Group’s P/E Is Telling You
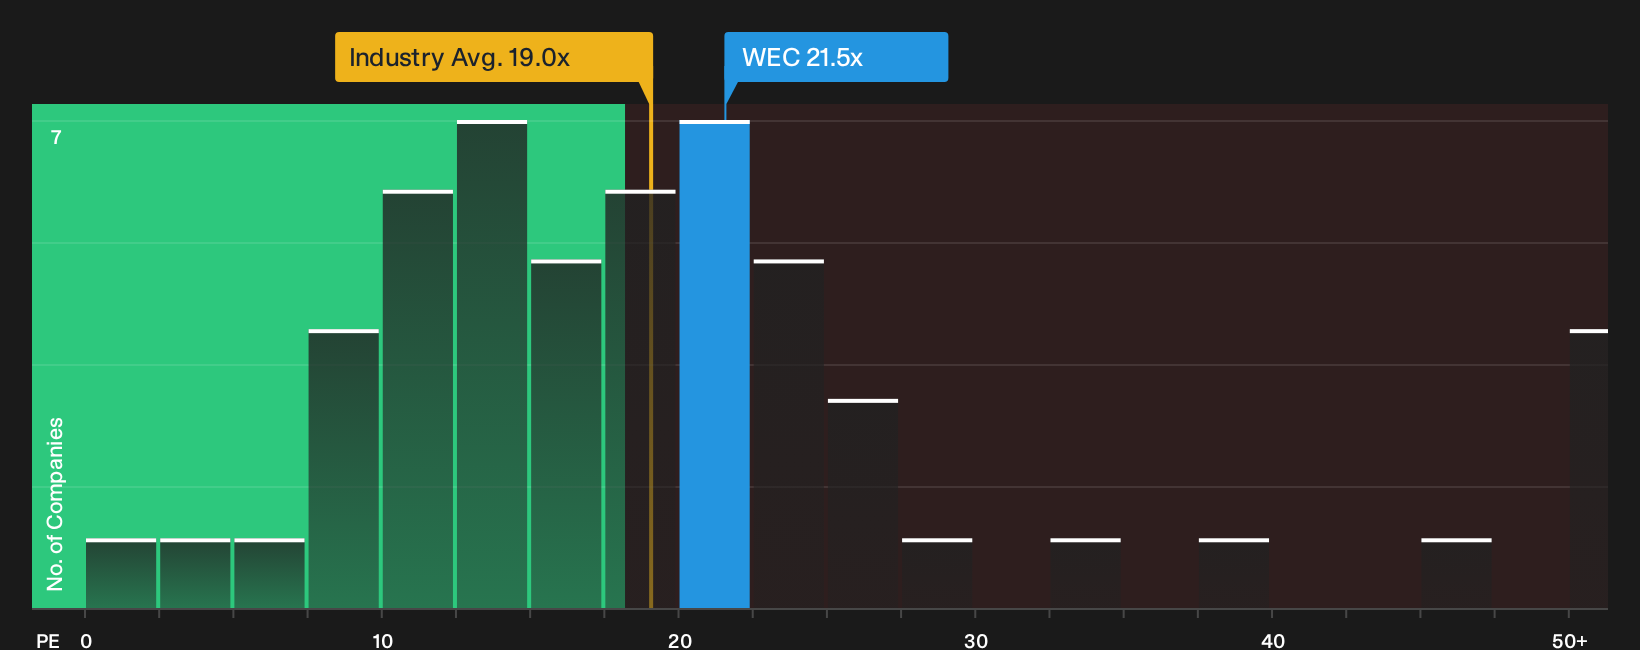
On simple earnings multiples, WEC Energy Group screens as anything but cheap. The stock trades on a P/E of 21.5x, which is above the global Integrated Utilities average of 18.8x and ahead of peers at 20.6x, yet it still sits just below a fair ratio of 22.3x.
That mix of a premium to the sector and a small discount to the fair ratio points to a stock where execution or sentiment shifts could move the multiple either way. For investors weighing new capital, the real question is whether that P/E gap feels like risk or opportunity.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the story so far. If you want to move before sentiment shifts again, weigh those trade offs yourself with 3 key rewards and 2 important warning signs.
Looking for more WEC Energy Group style investment ideas?
If you like the balance of income, stability, and upside potential around WEC Energy Group, do not stop here. The real edge comes from lining up a broader watchlist using targeted stock ideas built from the Simply Wall Street Screener, so you are ready when the next opportunity fits your playbook.
- Target resilient income by reviewing a curated pool of companies that pay higher yields and focus on durability through 6 dividend fortresses.
- Hunt for quality at a discount by scanning a focused universe of stocks that pair strong fundamentals with appealing valuations through 21 high quality undiscovered gems.
- Stack your watchlist with sturdier balance sheets by zeroing in on businesses screened for financial strength and debt discipline using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com