


What Just Happened With Replimune Group (REPL)?
Replimune Group (REPL) just reported second quarter and first half results, with net losses narrowing to US$57.12 million and US$126.89 million, compared with US$83.1 million and US$169.79 million a year earlier.
The earnings update follows a strong run in Replimune Group’s share price, with a 30 day share price return of 51.09% and a 90 day gain of 66%. The 1 year total shareholder return of 135.53% contrasts with a 5 year total shareholder return that remains down 40.61%.
Scan how Replimune Group’s earnings shift compares with other biotech opportunities by running your eye over our hand picked 21 high quality undiscovered gems in the sector.
After a surge like Replimune Group has just logged, some investors rush in while others wait for a pullback. So how does the current valuation stack up against the risk of sitting on the sidelines?
Most Popular Narrative: 3% Overvalued
Replimune Group last closed at $20.02, compared with a widely followed fair value narrative of $19.50 that uses a 7.6% discount rate and ties directly to long range earnings assumptions.
The current valuation suggests that the market is still applying a discount to Replimune Group despite TUDRIQEV’s FDA accelerated approval, analyst upgrades with price targets up to US$21, and the company’s view that the stock is undervalued and that its outlook is positive.
See why 1 investors see Replimune Group as 3% overvalued.
Result: Fair Value of $19.50 (OVERVALUED)
Still, Replimune Group’s story can change quickly if the IGNYTE-3 confirmatory trial disappoints or if TUDRIQEV uptake at key hospitals proves slower than expected.
Find out about the key risks to this Replimune Group narrative.
Another View: Our DCF Model Sees Deep Value In Replimune Group
The analyst narrative pegs Replimune Group at roughly 3% over fair value, yet our DCF model points in the opposite direction. On Simply Wall St’s numbers, REPL trades about 85% below an estimated future cash flow value of $131.38. That gap signals sizeable valuation risk if the growth narrative falters, but also raises the question of whether the market is underpricing success in TUDRIQEV and the broader RPx pipeline.
To understand how this future cash flow estimate is built and what would need to go right for Replimune Group to grow into that valuation, take a close look at the Look into how the SWS DCF model arrives at its fair value..
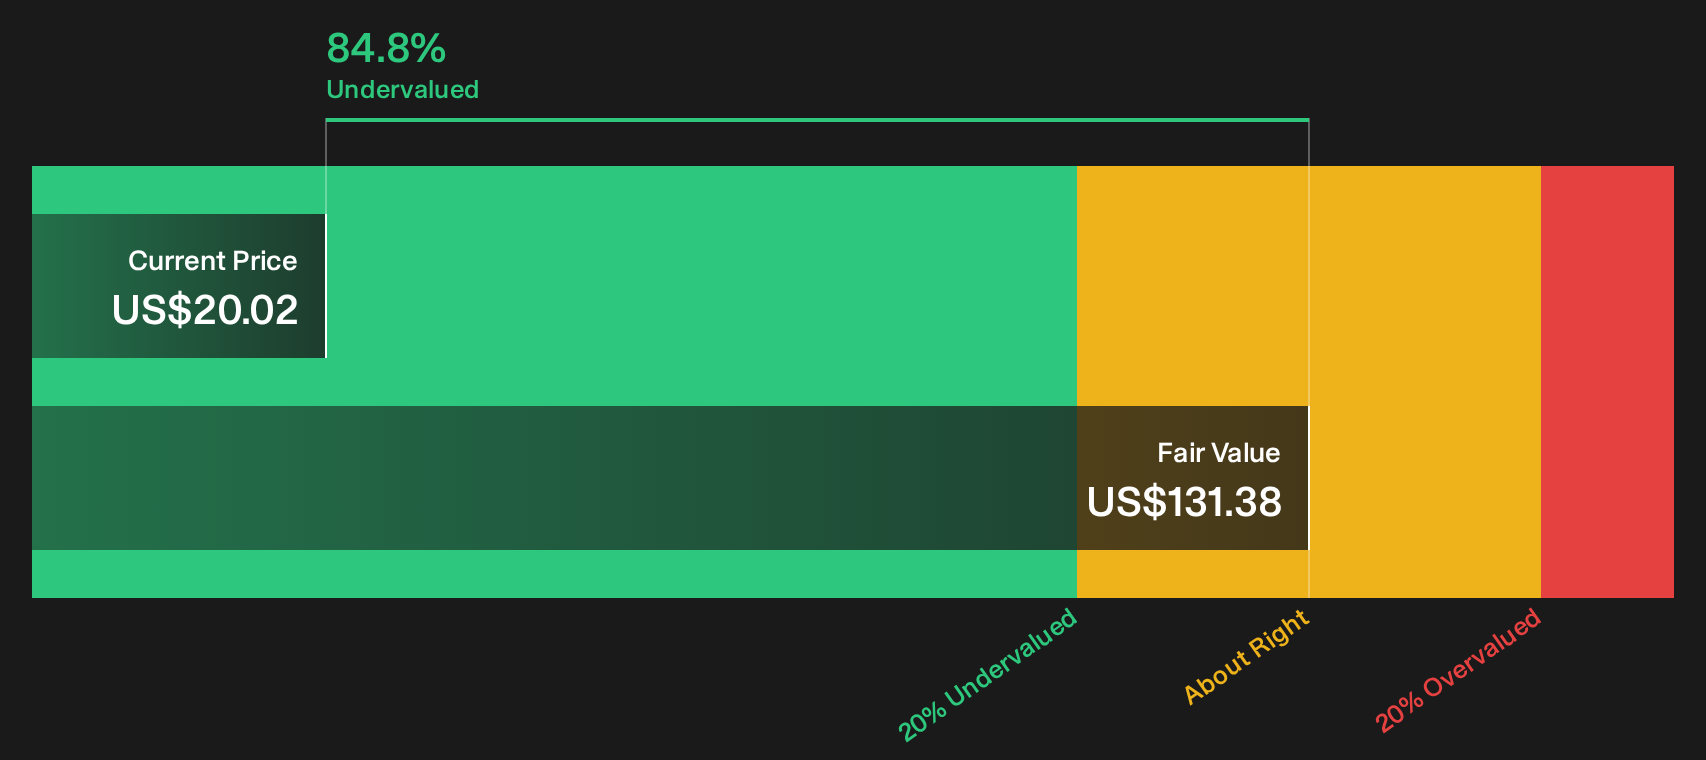
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Replimune Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty in this Replimune Group update points in different directions, so move quickly, study the numbers for yourself, and weigh both the bright spots and the pressure points. To understand that balance clearly, start with the 2 key rewards and 4 important warning signs.
Looking For More Investment Ideas Beyond Replimune Group?
Do not stop with Replimune Group. Broaden your watchlist now, or you risk missing other opportunities that could better match your goals and risk comfort.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (24 results) that can help anchor a portfolio through different market conditions.
- Hunt for quality at a discount by reviewing the 42 high quality undervalued stocks that filters for companies combining strong finances with prices below estimated worth.
- Lock in dependable cash returns by assessing the 6 dividend fortresses that highlights higher yielding businesses with an income focus.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com