


Is Elementis (LSE:ELM) Undervalued On 7% Revenue Growth And Softer Fourth Quarter Guidance?
Why Elementis Updated Its Outlook
Elementis (LSE:ELM) triggered fresh interest after reporting a 7% organic constant currency revenue increase to $479 million for the first nine months of 2026, alongside seasonally softer fourth quarter revenue guidance.
Recent trading has been upbeat for Elementis, with a 1-day share price return of 1.50% on the latest £1.90 close and a 30-day share price gain of 7.59% that lines up with the fresh trading update on revenue and guidance.
That short-term lift sits on top of a 14.05% year to date share price return and a 1-year total shareholder return of 17.75%. The 3-year total shareholder return of 66.87% suggests that investors have been steadily re-rating the business as execution in areas such as Personal Care and Asia has become clearer.
Scan beyond Elementis and line up other specialty and materials stocks showing fresh momentum using our hand picked 13 high quality undervalued stocks as a starting field.
The recent jump in Elementis shares tracks concrete updates on Personal Care and regional performance, not just changing mood music. The key issue now is how that shift lines up with what investors are paying for the stock.
Most Popular Narrative: 11% Undervalued
Elementis is trading at £1.90 against a widely followed fair value estimate of about £2.13. This frames the recent share strength as investors reassessing what they are willing to pay rather than chasing momentum alone.
The company's increased focus on high-growth specialty additives following the divestiture of commoditized and carbon-intensive Talc and Chromium businesses positions Elementis to benefit from rising global demand for advanced, sustainable materials in urbanization-driven end markets such as personal care and coatings, supporting both topline revenue growth and higher operating margins.
Elementis' leadership in natural, sustainable rheology modifiers (especially hectorite) and the planned expansion into new applications (like fire retardants, agrochemicals, and construction) aligns with growing regulatory and consumer pressure for eco-friendly products, likely driving revenue expansion and premium pricing power that will support margin improvement.
See why 2 investors see Elementis as 11% undervalued.
The most followed narrative uses a 7.97% discount rate and arrives at a fair value of £2.13 per share, compared with the latest £1.90 close, and labels Elementis as undervalued by about 11%. That view rests on relatively modest revenue growth assumptions, higher forecast profit margins at 15.5%, and a future P/E of 20.1x that sits slightly above the current GB Chemicals industry level cited in the narrative.
For readers, the key question is whether those inputs feel reasonable. The model assumes earnings rising from US$71.7m to US$101.4m by around 2029 and then discounts those future cash flows back at just under 8%. If you think Elementis can sustain higher margins in Personal Care and Coatings while maintaining that earnings path, the narrative fair value may look sensible. If not, the £2.13 figure could be on the optimistic side.
Result: Fair Value of £2.13 (UNDERVALUED)
Still, the Elementis narrative leans on higher margins and hectorite demand, and any pressure on R&D or faster shifts to alternative chemistries would quickly test that view.
Find out about the key risks to this Elementis narrative.
Another View: What Elementis Looks Like On Earnings Multiples
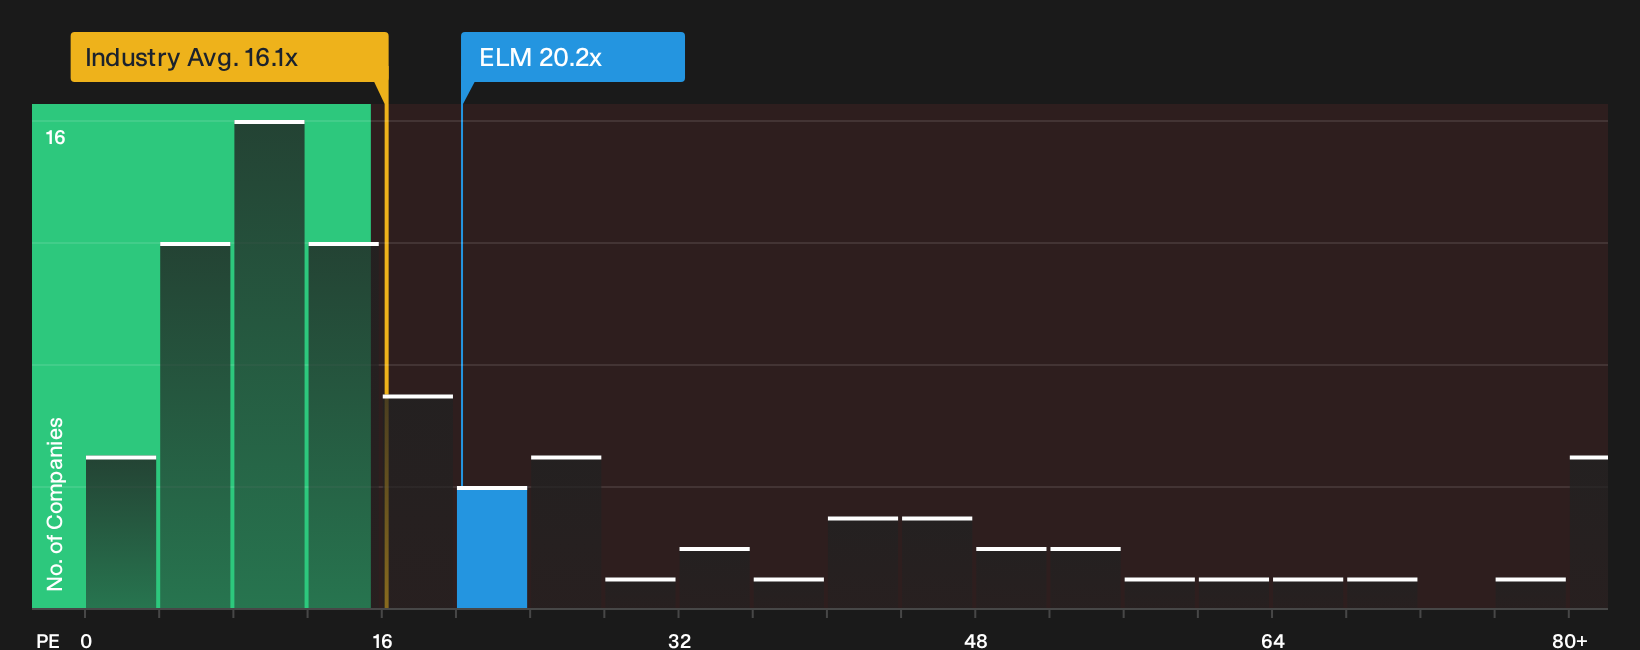
The narrative around Elementis leans on cash flows and margin expansion, yet the market is still paying 20.2x P/E. That is above the European Chemicals group on 16.1x and the fair ratio of 14.4x that the market could move towards. This points to valuation risk if sentiment cools.
Set against cheaper peers and a lower fair ratio anchor, the current multiple asks you to pay up for execution on margins and growth that are not especially fast. The question is simple: are you comfortable paying a premium tag today for earnings that analysts only expect to rise at about 10.4% a year?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this Elementis story feels finely balanced to you, trust that instinct and pressure test the numbers yourself while sentiment is still forming. To see what optimistic investors are focusing on, run through the 3 key rewards.
Looking for more Elementis-sized investment ideas?
If Elementis has sharpened your focus, treat that curiosity as a signal and use it to widen your opportunity set before the next move passes you by.
- Target higher yield potential and stress test your income plan with the 5 dividend fortresses.
- Hunt for quality businesses that trade below their estimated worth so you are not overpaying, starting with the 13 high quality undervalued stocks.
- Prioritise financial resilience by focusing on balance sheets that look built to endure shocks using the list of solid balance sheet and fundamentals (10 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com