


Is Upcoming Earnings Altering The Investment Case For Iron Mountain Stock?
- Iron Mountain is scheduled to report third quarter 2026 results on 5 November, with expectations for higher revenue and adjusted funds from operations supported by data center and asset lifecycle management activity.
- The focus on data centers and asset lifecycle services highlights how Iron Mountain is relying on digital infrastructure and IT hardware handling to support its broader information management franchise.
- This article examines how Iron Mountain's expected third quarter revenue and AFFO trends could influence the broader investment narrative.
Scan beyond Iron Mountain and line up other digital infrastructure and data center plays using the hand picked 54 AI infrastructure stocks as a starting shortlist.
Iron Mountain Investment Narrative Recap
To own Iron Mountain, you need to believe the business can keep shifting from paper storage to higher value digital infrastructure and asset lifecycle management while still using its legacy records operation as a cash engine. The upcoming third quarter update, with expectations for higher revenue and AFFO, points directly at whether that pivot is gaining traction.
The short term swing factor is execution on data center and asset lifecycle growth, especially converting new capacity and services into recurring contracts. The biggest risk is that heavy capital spending and interest costs, alongside currency moves, weigh on AFFO progression. If those headwinds are modest, the earnings story is largely unchanged.
With no fresh company specific announcements tied directly to this third quarter release, the most relevant context is the existing plan to energize about 325 megawatts of data center capacity over the next 18 to 24 months and scale asset lifecycle management. This is where Iron Mountain is trying to build its next leg of cash flow.
Third quarter numbers sit in the middle of that build out. Stronger data center and asset lifecycle revenue would support the idea that previously signed hyperscale leases, AI oriented deployments in cities such as London and Mumbai, and ALM expansion are coming through in reported results. Any disappointment, or signs that higher interest expense is biting into AFFO, would highlight how tight the execution window is.
What The Long Range Iron Mountain Numbers Assume
Iron Mountain's narrative projects US$9.9b revenue and US$764.5m earnings by 2029. This implies 9.5% yearly revenue growth and an earnings increase of about US$345.8m from US$418.7m today.
Discover why Iron Mountain's fair value suggests a 24% potential upside to its current price, which could narrow quickly.
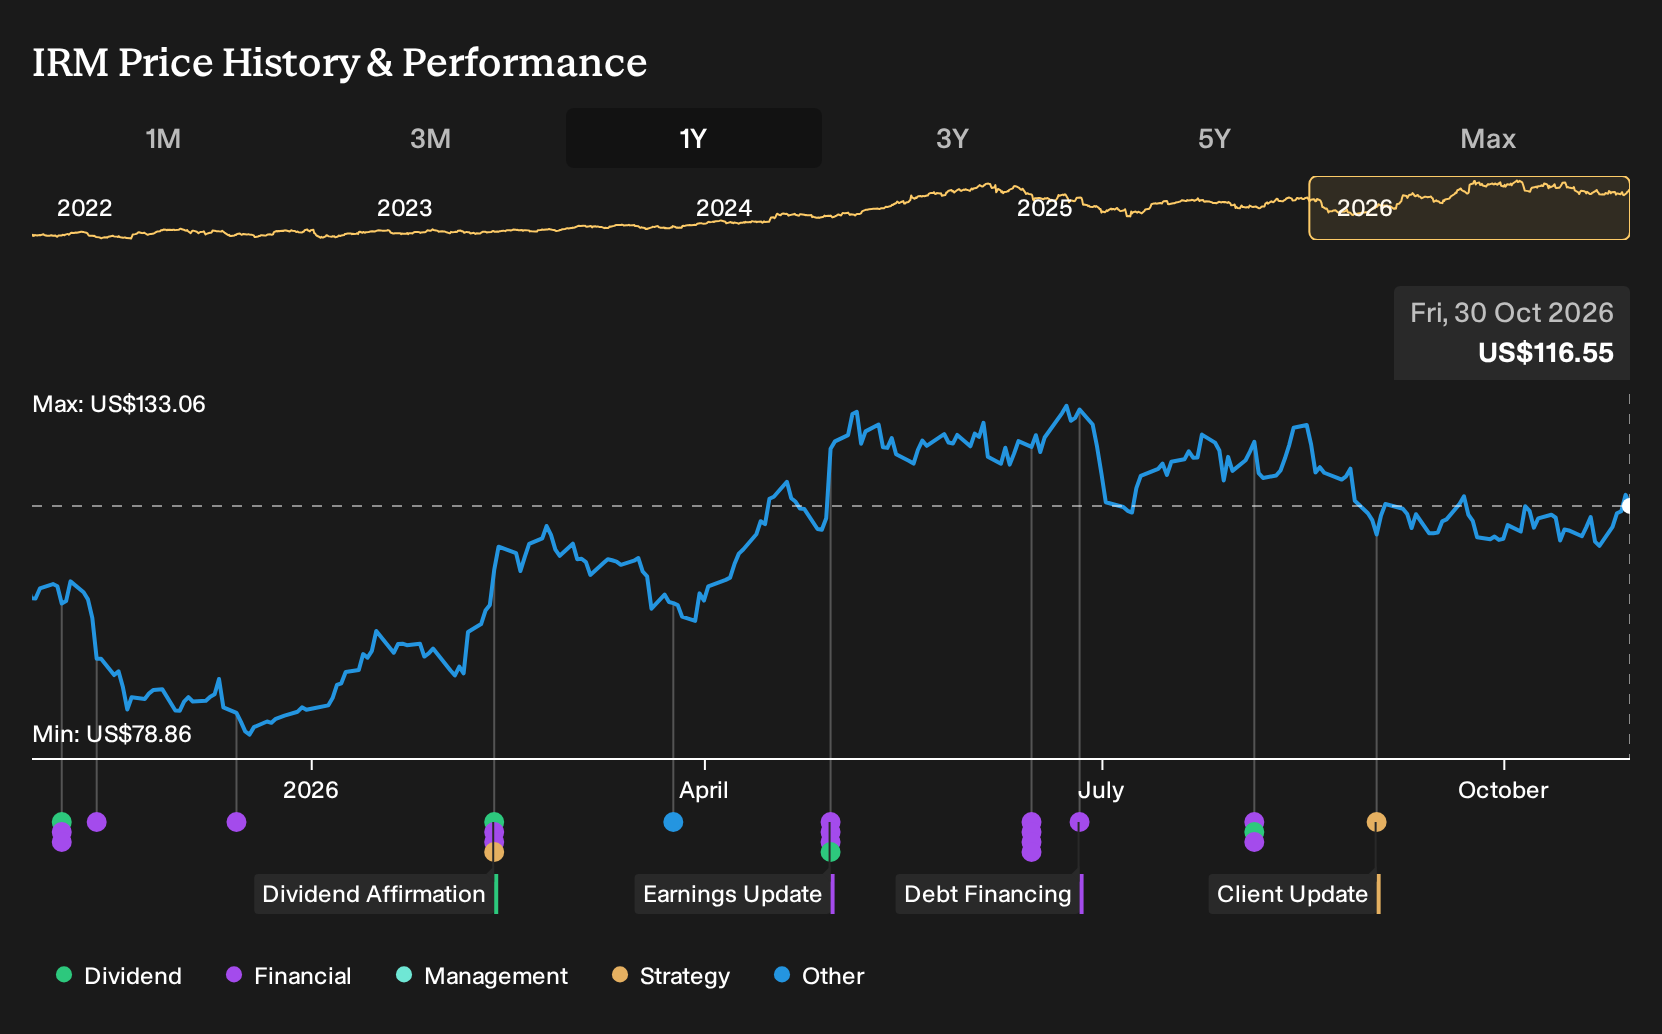
Exploring Other Perspectives
One alternate angle on Iron Mountain focuses on margin pressure from lower margin Asset Lifecycle Management work. The most cautious analysts were penciling in about US$9.0b of 2029 revenue and US$554.4m of earnings, far below the consensus earnings view. Those estimates came before this quarter, so you should expect opinions to evolve as new information lands.
Explore 4 other Iron Mountain fair value estimates, including one that suggests it could be worth just $144.00!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Iron Mountain research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Iron Mountain. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Iron Mountain's overall financial health at a glance.
Looking For More Investment Ideas Beyond Iron Mountain?
If the Iron Mountain story has sharpened your thinking about where to put fresh capital to work, use that momentum to widen your watchlist with a few targeted stock pools from the Simply Wall St Screener.
- For investors who want value with quality, start with companies flagged as 36 high quality undervalued stocks and see which ones match your return and risk preferences.
- If income is your priority, filter for businesses that show consistent payouts and stronger yields through a curated set of 5 dividend fortresses.
- When capital preservation matters most, narrow the field to companies with sturdier finances using a focused 29 resilient stocks with low risk scores as your hunting ground.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com