


Learn Why The Bull Case For Waters Stock Could Change Following AI Software Launch
- Waters Corporation has rolled out AI-powered peak integration in its Empower software and announced collaborations with Labcorp, Quest Diagnostics and IMU Biosciences that expand access to HPV testing, at-home cervical cancer screening and large-scale immune profiling using its instruments and software.
- The combination of AI-driven chromatography automation and deeper ties into diagnostics and multi-omics projects points to Waters embedding its technology more tightly into regulated laboratory workflows and long-term research programs, which can influence demand visibility for both instruments and recurring software and consumables.
- We will now look at how Waters' AI-powered Empower upgrade could influence its investment narrative and long-term execution story.
Scan how Waters is weaving AI deeper into lab workflows, then size up other potential beneficiaries across regulated science with our hand-picked 33 healthcare AI stocks.
Waters Investment Narrative Recap
To own Waters, you need to believe the business can keep turning its instrument footprint, BD Diagnostics acquisition and Empower software into steadier, higher quality earnings despite recent margin pressure and shareholder dilution. The AI powered Empower upgrade fits that story because it aims at regulated labs where workflows are sticky and software is central to day to day operations.
In the near term, the key swing factor is execution on BD integration and stabilising weaker regions like China, while keeping profit margins from slipping further after a large one off loss. The AI Empower release and diagnostics collaborations are helpful for the narrative but are unlikely to change the most important near term risk, which is integration missteps that weigh on earnings.
The AI Powered Peak Integration launch inside Empower looks most relevant right now. It targets exactly where Waters already has deep penetration, regulated QC and QA labs, with claims of up to 95% fewer manual interventions, 76% higher accuracy and 72% less user variability versus prior practice. Early access beginning in December 2026 and validated rollout in 2027 gives a clear execution timeline.
For you as an investor, the interest is how far this premium tier subscription can deepen Empower’s role as the chromatography data system of record and support more recurring software and consumables revenue. It also links tightly to the broader AI workflow theme that analysts already cite as a catalyst, while still leaving BD integration, margin repair and China weakness as the main operational watchpoints.
How Waters’ AI Story Connects To The Numbers
Waters' narrative projects US$7.9b revenue and US$1.4b earnings by 2029. This assumes revenue expanding at about 19.3% a year and earnings rising by roughly US$1.2b from current earnings of US$166.6m.
Uncover why Waters' fair value is consistent with its current price.
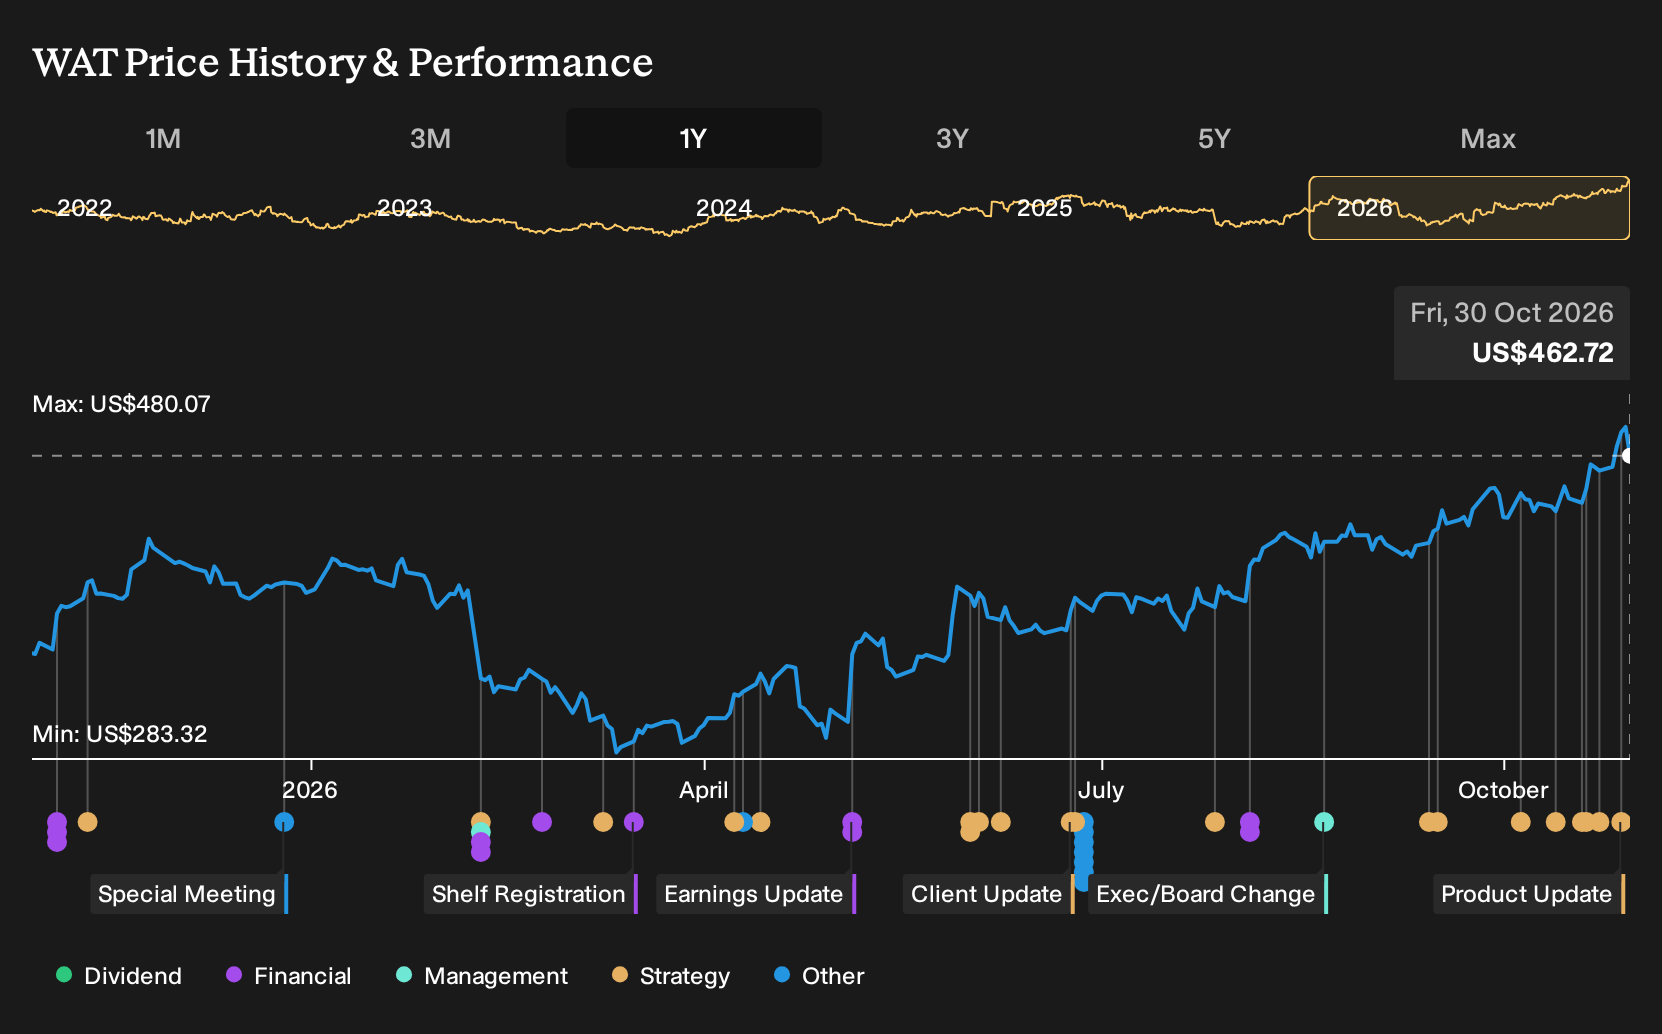
Exploring Other Perspectives
You can interpret Waters in several ways. The most cautious analysts worry that complex BD integration and reliance on mature LC and LC MS product lines could limit the impact of AI Powered Peak Integration. As a result, their pre-news forecasts indicated about US$8.2b in revenue and US$1.2b in earnings by 2029. You can use these more skeptical assumptions to test your own view and consider how this new AI and diagnostics development might change the narrative.
Explore 3 other Waters fair value estimates, including one that suggests as much as 24% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Waters research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Waters. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Waters' overall financial health at a glance.
Looking For More Investment Ideas Beyond Waters?
Once you have a handle on Waters and its AI push into regulated labs, it can help to set it alongside other opportunities that match different portfolio goals using the Simply Wall St Screener.
- For readers focused on quality at a sensible entry point, compare Waters with a 36 high quality undervalued stocks that combine strong fundamentals with attractive pricing signals.
- If capital preservation and a smoother ride matter most to you, consider how Waters stacks up against a 29 resilient stocks with low risk scores that score well on stability and financial resilience.
- For those hunting for less crowded opportunities, weigh Waters alongside a 19 high quality undiscovered gems that pair solid business metrics with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com