


Chevron (CVX) Looks Fully Valued As Strong Q3 Earnings Lift The Debate
Why Chevron’s latest earnings matter for shareholders
Chevron (CVX) just posted a strong third quarter, with revenue and net income well above last year, helped by record refining margins, tight diesel supplies and heavier activity in Venezuela.
The firm’s refineries ran hard during a global diesel shortage, while expanded Venezuelan operations and improved execution in U.S. assets added further support to earnings and helped draw in fresh ETF buying.
Across all this news, Chevron’s share price has picked up strong momentum, with a 30-day share price return of 13.95%, a 90-day gain of 23.70% and year-to-date share price return of 51.07%. The 1-year total shareholder return of 58.92% and 5-year total shareholder return of 149.93% show how recent buying and dividend income have compounded for longer term holders.
Scan how Chevron’s move has reshaped the energy patch and spot other potential winners with the hand-picked 42 power grid technology and infrastructure stocks that is driving the next leg of infrastructure demand.
Chevron now trades almost exactly in line with the average analyst target, while internal fair value estimates still point to a sizeable discount. The real puzzle is which reference point you treat as the anchor for worth.
Most Popular Narrative: 1% Overvalued
Chevron last closed at $235.52, a touch above the most followed fair value estimate of $232.50, so the focus shifts to what needs to happen in the business for that gap to close.
Record production growth, especially in the Permian and from the Hess acquisition in areas such as Guyana and the Bakken, now sits on top of capital and drilling programs that aim to keep Permian volumes around 1 million barrels per day with lower CapEx per barrel, which supports future revenue and free cash flow.
See why 483 investors see Chevron as 1% overvalued.
Result: Fair Value of $232.50 (OVERVALUED)
Still, this Chevron narrative can crack if long term energy demand shifts away from hydrocarbons faster than expected or if investors stop paying a premium P/E multiple.
Find out about the key risks to this Chevron narrative.
Another View on Chevron’s valuation
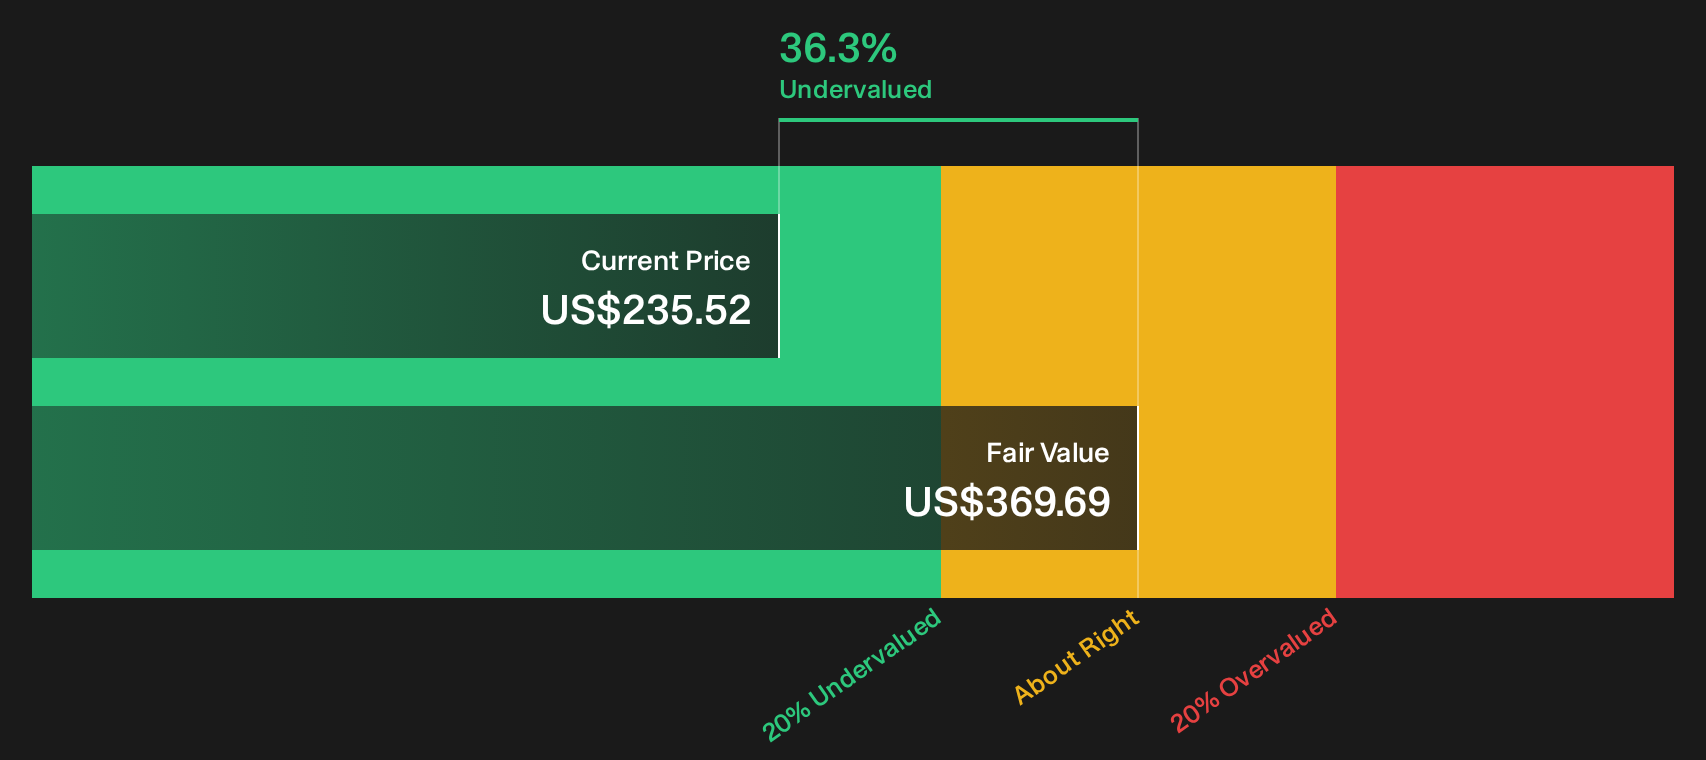
While the most followed fair value for Chevron pegs the stock at $232.50 and labels it slightly overvalued, the SWS DCF model tells a very different story. On that cash flow view, Chevron at $235.52 trades well below an estimated future cash flow value of $369.69. This flags a wide gap that investors need to sanity check for themselves.
To understand how that gap arises and what assumptions sit under it, run through Look into how the SWS DCF model arrives at its fair value..
Next Steps
Mixed messages in Chevron’s valuation story so far. If you want to move beyond the headline views and pressure test the upside and downside yourself, start by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Chevron?
If Chevron has sharpened your focus, now is the moment to broaden your list and hunt for other high conviction setups before the next wave of money moves.
- Target resilient income by reviewing 5 dividend fortresses to help anchor your portfolio with steady cashflows when markets turn choppy.
- Hunt for quality at a discount by filtering for 19 high quality undiscovered gems before the crowd starts paying attention to their fundamentals.
- Dial down potential volatility by scanning 29 resilient stocks with low risk scores so you are not caught off guard when sentiment swings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com