


What Bata India Holders Got Wrong Before The Slide
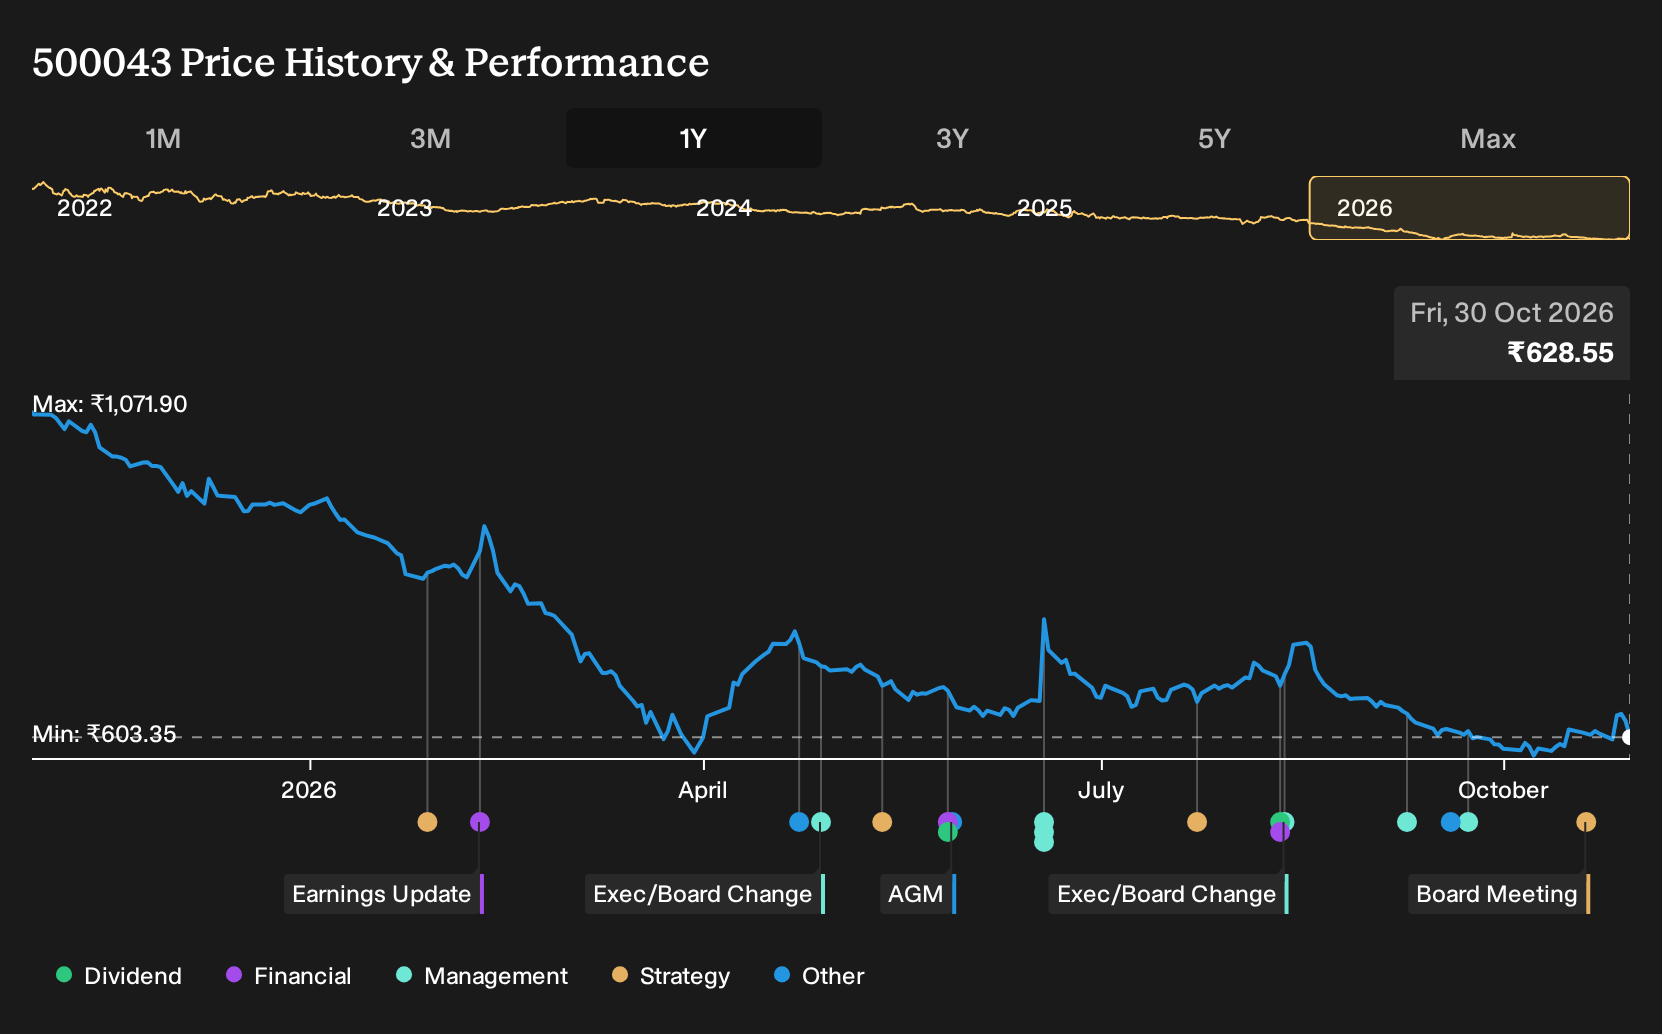
If you had looked at Bata India in late October 2025 and decided to sit it out, the decision might feel very different today. Investors who held Bata India over the past year are down 38.5%, including dividends. That result sits beside rising quarterly revenue and higher net margin reported in August 2026, which makes the slide even more puzzling. So what assumption on record back in October 2025 might have signalled that this outcome was a real risk?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
If the move has made Bata India harder to judge, start where the gap is still open and scan 200 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On Bata India
The shares cost ₹1,072 at the start of the period, and anyone looking at Bata India then had to decide which story sounded more reasonable.
The bullish narrative pinned fair value at ₹1,394. It leaned on assumptions that annual revenue growth would run at 9.2% and that profit margin would climb to 10.0% over three years.
The bearish view argued for fair value of ₹850. That script still assumed 6.3% yearly revenue growth, but saw profit margin only reaching 8.2% and a future P/E of 48.5x.
What The Results Changed For Bata India
The clearest new fact was Bata India reporting Q1 2027 revenue of ₹9,789.47m with net income of ₹639.84m. Net margin moved from 5.5% in Q1 2026 to 6.5%. That direction of profitability supported the view that expected higher margins, although one quarter of progress left the broader debate between the optimistic and cautious cases open.
The key assumption was margin expansion. When you assess another stock with a similar story, track the reported net margin each year against the thesis and ask whether profits are moving toward the written target or stalling short.
What You Would Be Paying For In Bata India Today
Bata India now trades at ₹629, with this Narrative’s Fair Value estimate sitting above that level based on its own modelling. The gap rests on the belief that cost structure, product mix and channel choices can do more heavy lifting than store rollout alone.
For that higher figure to be realised, a buyer today would need to assume Bata India actually delivers the margin uplift implied in its reset supply chain and employee base.
"Bullish analysts expect Bata India to compound the benefits of leaner merchandising, a larger franchise and omnichannel footprint, and a higher mix of premium brands into meaningfully stronger profitability over time. The main requirement is that Bata India executes on supply chain consolidation and manufacturing restructuring, including the shift to a smaller set of core suppliers and lower structural employee costs, so that the targeted margin uplift is reflected in reported earnings."
The price and this Narrative do not agree. → Uncover what this Narrative says Bata India is actually worth
Before The Next Story Makes Headlines
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 41% below our estimate - builds AI centric video collaboration and B2B offerings to offset weaker hardware regions.
- Company 2 - 28% below our estimate - expands AI heavy cloud infrastructure so subscriptions and consumption workloads run on the same stack.
- Company 3 - 43% below our estimate - converts forensic software users to higher tier licenses while growing recurring contracts from public agencies.
Those are three of them. See every one of the 199 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com