


Autohome (ATHM) Could Be 7% Undervalued After Its Hong Kong Office Move
Autohome (ATHM) recently shifted its principal place of business in Hong Kong to Suite 802, CITIC Tower in Central, an administrative move that comes as the stock trades near its assessed intrinsic value.
Over the past year, Autohome’s share price has trended lower, with the 90 day share price return down 13.5% and the 1 year total shareholder return declining 13.9%. This points to fading momentum even as management pursues AI tools and transaction expansion, and the shares trade at a valuation close to assessed intrinsic value.
Seize this chance to compare Autohome’s muted share price with resilient peers by scanning our 29 resilient stocks with low risk scores, which aims to combine sturdier balance sheets with lower risk profiles.Autohome now trades close to assessed intrinsic value after a steady slide and a quiet address shift in Hong Kong. Does that mix still skew the risk reward toward new buyers, or has most of the upside already been priced in?
Most Popular Narrative: 7% Undervalued
Autohome’s most followed narrative pegs fair value at $21.40, slightly above the recent $19.86 close, which frames the stock as modestly undervalued while the market digests softer revenue and margin pressure.
The build out of Autohome Mall and new retail pilots, including online car purchase models in multiple cities and the Autohome Good Car offline franchise network, is creating a broader transaction ecosystem that may shift the company’s revenue base from media and leads toward transaction commissions and service fees.
The expansion of a dual used car engine, with a standardized domestic inspection process and a cross border export platform already serving buyers in over 100 countries, is setting up new fee and commission streams that could gradually change the balance of revenue and earnings between used and new car related activity.
See why 3 investors see Autohome as 7% undervalued.
Result: Fair Value of $21.40 (UNDERVALUED)
Still, if China’s auto slump lingers and Autohome’s AI and transaction push fails to offset weaker media and leads revenue, this modest undervaluation case can unravel quickly.
Find out about the key risks to this Autohome narrative.
Another View: Autohome Through The P/E Lens
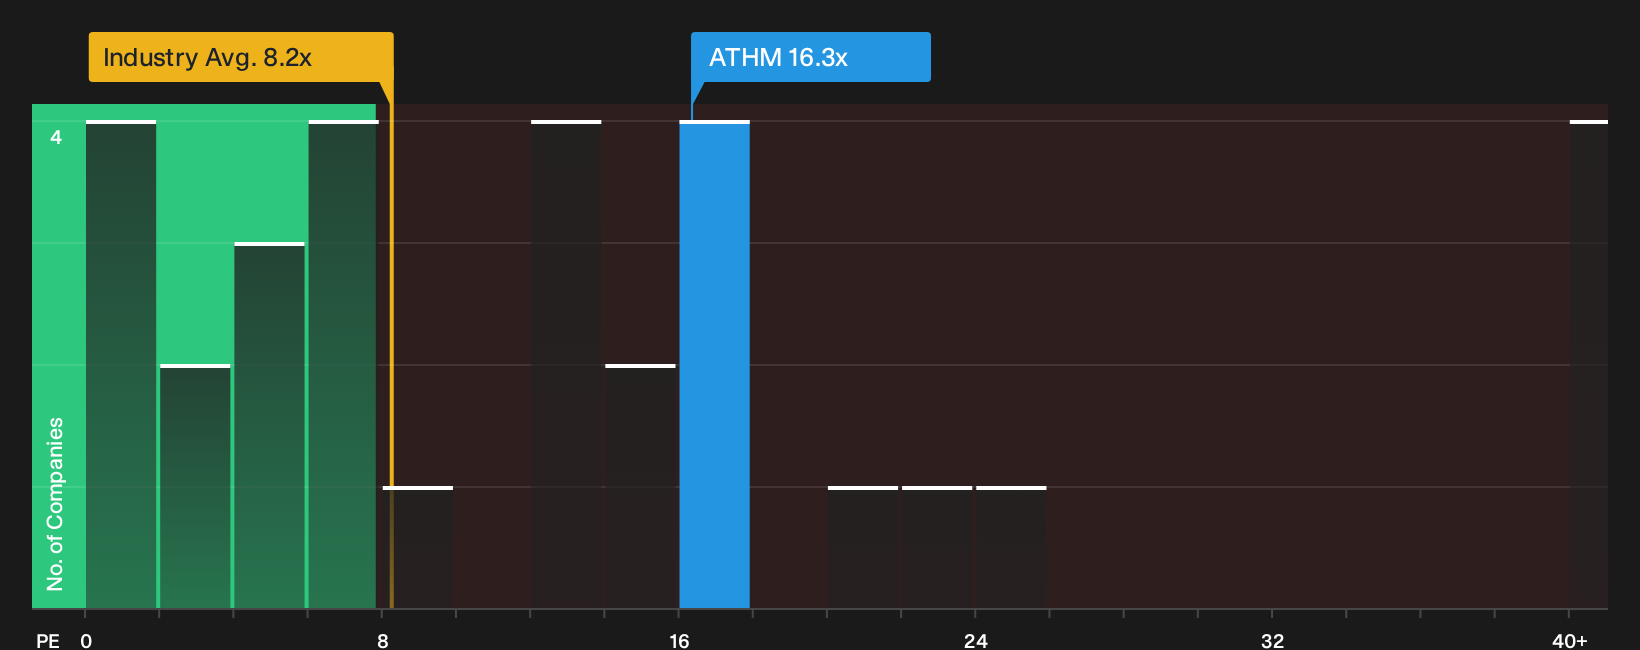
A different yardstick paints Autohome as less comfortable. The current P/E of 16.3x is higher than the US Interactive Media and Services industry at 8.2x and above the peer average of 12.9x. It also sits above a fair ratio of 14.4x that the market could move toward.
That gap suggests less margin for error if earnings fall short, since a move closer to the fair ratio or industry levels would pressure the share price even if profits track forecasts. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Reading this mix of modest undervaluation, richer P/E, and shifting business drivers, you can see why opinions on Autohome are split. If you want to move fast and form your own judgment based on both caution and optimism, start by weighing the 2 key rewards and 1 important warning sign
Looking for more Autohome sized investment ideas?
If Autohome has sharpened your thinking, do not stop here. Fresh opportunities keep appearing, and missing them often comes down to not checking what else is on the radar.
- Target more resilient candidates by scanning a list of solid balance sheet and fundamentals (24 results). This aims to highlight businesses with sturdier finances and dependable fundamentals.
- Hunt for mispriced opportunities using the 19 high quality undiscovered gems. This focuses on quality companies investors may not be watching closely yet.
- Strengthen your income ideas through the 5 dividend fortresses. This highlights higher yielding stocks that still prioritize durability and balance sheet health.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com