


Learn Why The Bull Case For Whirlpool Stock Could Change Following Full Year Loss Outlook
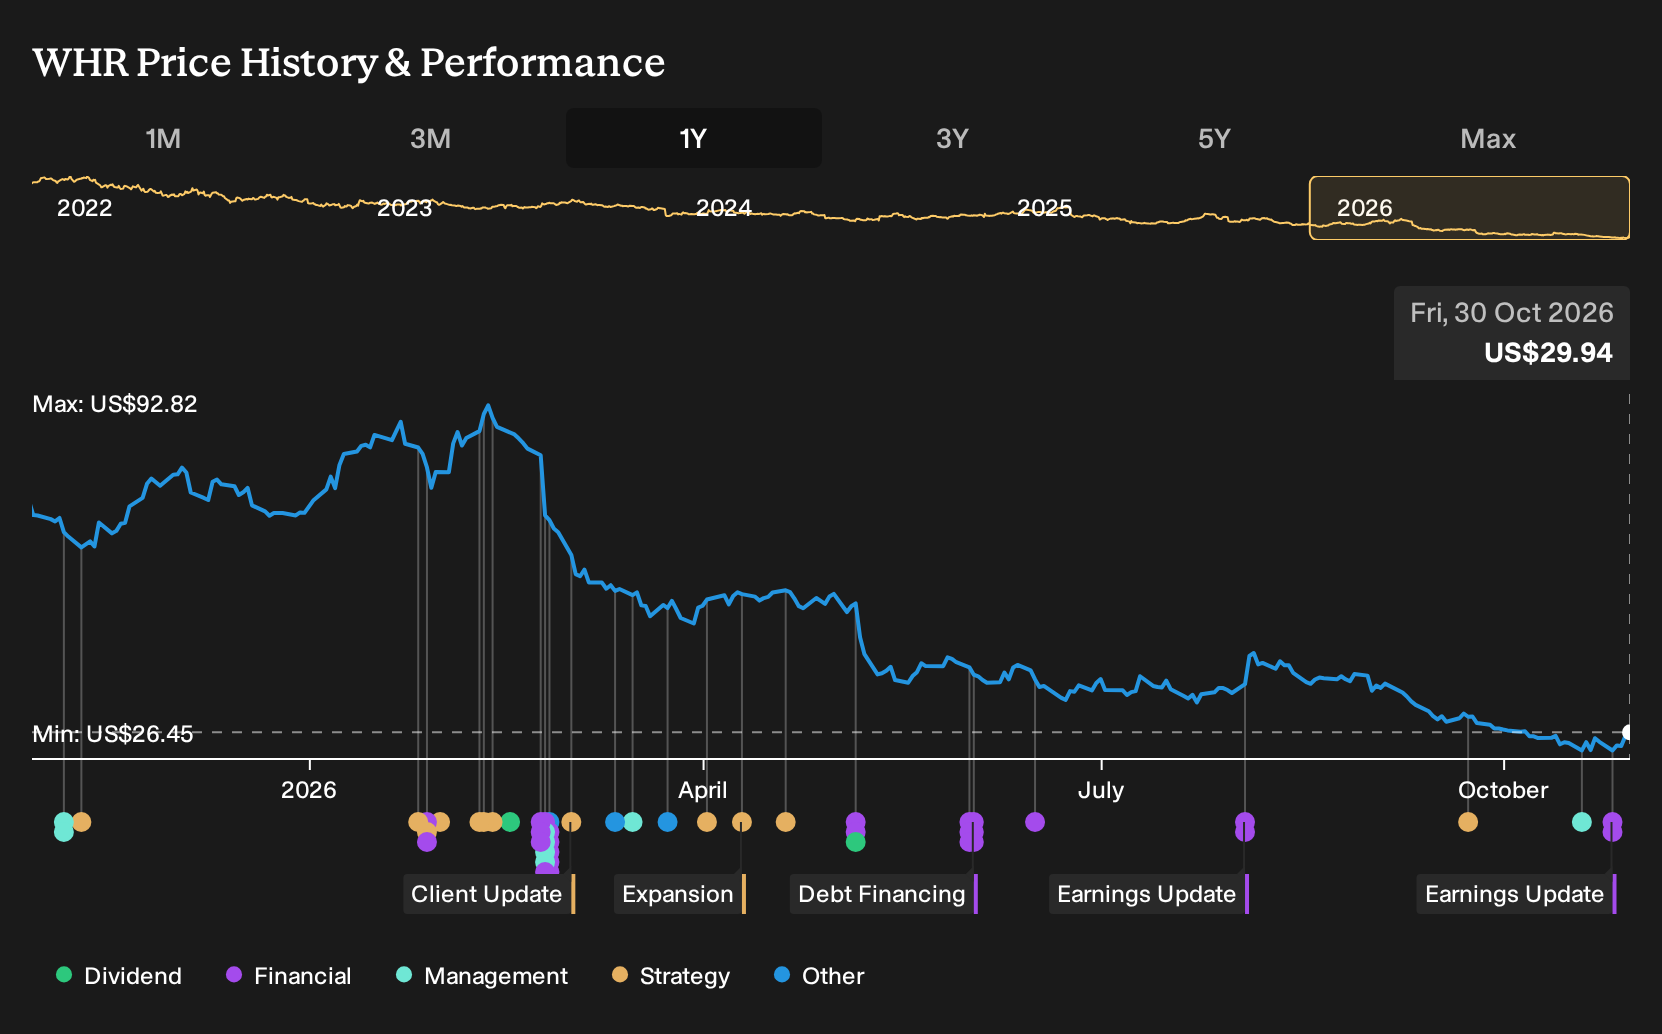
- Whirlpool reported third quarter 2026 sales of US$3,677 million and a net loss of US$237 million, with basic and diluted loss per share from continuing operations of US$3.80, and also recorded a net loss of US$231 million for the first nine months on lower sales versus the prior year.
- The full year 2026 outlook now points to roughly US$14.5 billion in net sales, indicating a declining top line versus 2025 and a GAAP net loss margin of 2.2%. This underlines ongoing earnings pressure even as Whirlpool adds a seasoned finance and asset management executive, Karin Risi, to its board.
- We will now assess how Whirlpool’s shift to a full year loss outlook might reshape the existing investment narrative around cost savings and margin repair.
Reassess Whirlpool in context and scan a hand picked 33 high quality undervalued stocks that may offer stronger balance sheets or cleaner earnings profiles than a manufacturer guiding to a full year loss.
Whirlpool Investment Narrative Recap
To own Whirlpool here, you need to believe the appliance cycle eventually stabilises and that cost work plus product refresh can repair margins from today’s loss making base. The new full year outlook, with about US$14.5b in sales and a GAAP loss, keeps the focus squarely on execution rather than on growth.
The biggest near term swing factor is whether Whirlpool can hold pricing and promotions in a weak demand backdrop without further eroding volumes. The sharp move from prior ongoing EBIT margin guidance to an expected loss raises the operational risk that factory consolidation, automation and logistics changes take longer to flow through than previously anticipated.
The most relevant update is the new 2026 guidance, which points to a GAAP net loss margin of 2.2% and ongoing loss per diluted share of US$1.30. That reframes Whirlpool as a turnaround story again, with the market now watching whether cost savings and mix upgrades are sufficient to close that earnings gap.
This outlook also matters for balance sheet work. Management has already raised equity, sold the Beko Europe stake and lined up sizable secured funding to support liquidity above US$3b. With interest payments not well covered by current earnings, consistent progress toward the loss targets and any traction in SDA Global profitability become key operational catalysts to monitor.
Whirlpool's current analyst narrative points to US$15.6b of revenue and US$201.3 million of earnings by 2029, based on assumptions of 2.4% yearly revenue growth and a shift from today's loss of US$152.0 million to that forecast profit, which would require an earnings improvement of about US$353 million.
Uncover how Whirlpool's fair value indicates a 23% potential upside to its current price that could narrow quickly if Whirlpool follows its turnaround plan.
Exploring Other Perspectives
One optimistic angle on Whirlpool leans hard on the SDA Global story. Bullish analysts had pencilled in revenue of about US$17.0b and earnings of roughly US$564.2 million by 2029, far higher than the consensus US$15.6b and US$201.3 million. You can now ask whether this latest loss outlook nudges those upbeat forecasts lower.
Explore 4 other Whirlpool fair value estimates, including one that suggests as much as 255% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Whirlpool research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Whirlpool. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Whirlpool's overall financial health at a glance.
Looking For More Ideas Beyond Whirlpool?
If Whirlpool's full year loss outlook has you rethinking concentration risk, it can help to widen the lens and compare it with businesses that have different balance sheet profiles, income streams, or risk levels. The Simply Wall St screener lets you move from a single stock story to a broader watchlist that fits your own comfort with volatility, dividends, and financial resilience.
- For investors who want potential value with quality in mind, start by scanning a curated set of 33 high quality undervalued stocks that combine stronger fundamentals with appealing pricing.
- If dependable income matters more to you than rapid capital gains, focus on companies in the 5 dividend fortresses that pair higher yields with an emphasis on ongoing shareholder payouts.
- When capital preservation sits at the top of your checklist, filter for resilience using the 29 resilient stocks with low risk scores to zero in on businesses that score better on risk metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com