


Is Proto Labs (PRLB) Undervalued After Q3 Earnings And Raised Guidance?
Q3 earnings headline and guidance shift
Proto Labs (PRLB) moved into focus after its Q3 2026 report, as higher revenue, stronger net income, and a raised full year growth outlook were paired with fresh Q4 guidance.
The Q3 release and new guidance landed against a sharp pullback in Proto Labs' share price, with the stock down 11.27% on the day and 29.85% over 30 days. It still shows a 34.16% year to date share price return and a 117.39% three year total shareholder return, which reflects longer term momentum built over several years rather than the past month.
Scan other manufacturing and automation plays reacting to earnings and guidance shocks with our curated list of 94 robotics and automation stocks that echo the Proto Labs Q3 story.
Proto Labs now trades well below both its analyst target and intrinsic value estimate, creating a wide valuation gap after the selloff. The next step is to determine where fair value plausibly sits within that range.
Most Popular Narrative: 32% Undervalued
Proto Labs last closed at $68.89, while the most followed narrative pegs its fair value at $101.25. This frames the recent share price drop against a materially higher long term estimate.
Continued expansion of Proto Labs’ CNC Machining and Injection Molding work into higher requirement production programs for aerospace and defense customers, including rockets, satellites, drones, and space exploration, can add more recurring revenue and support gross margin resilience as these projects move beyond one off prototyping into multi year programs.
See why 4 investors see Proto Labs as 32% undervalued.
Result: Fair Value of $101.25 (UNDERVALUED)
Still, this Proto Labs narrative can crack if European operations slip back into weakness or if softness in 3D printing continues to offset progress elsewhere.
Find out about the key risks to this Proto Labs narrative.
Another View: Proto Labs Through The P/E Lens
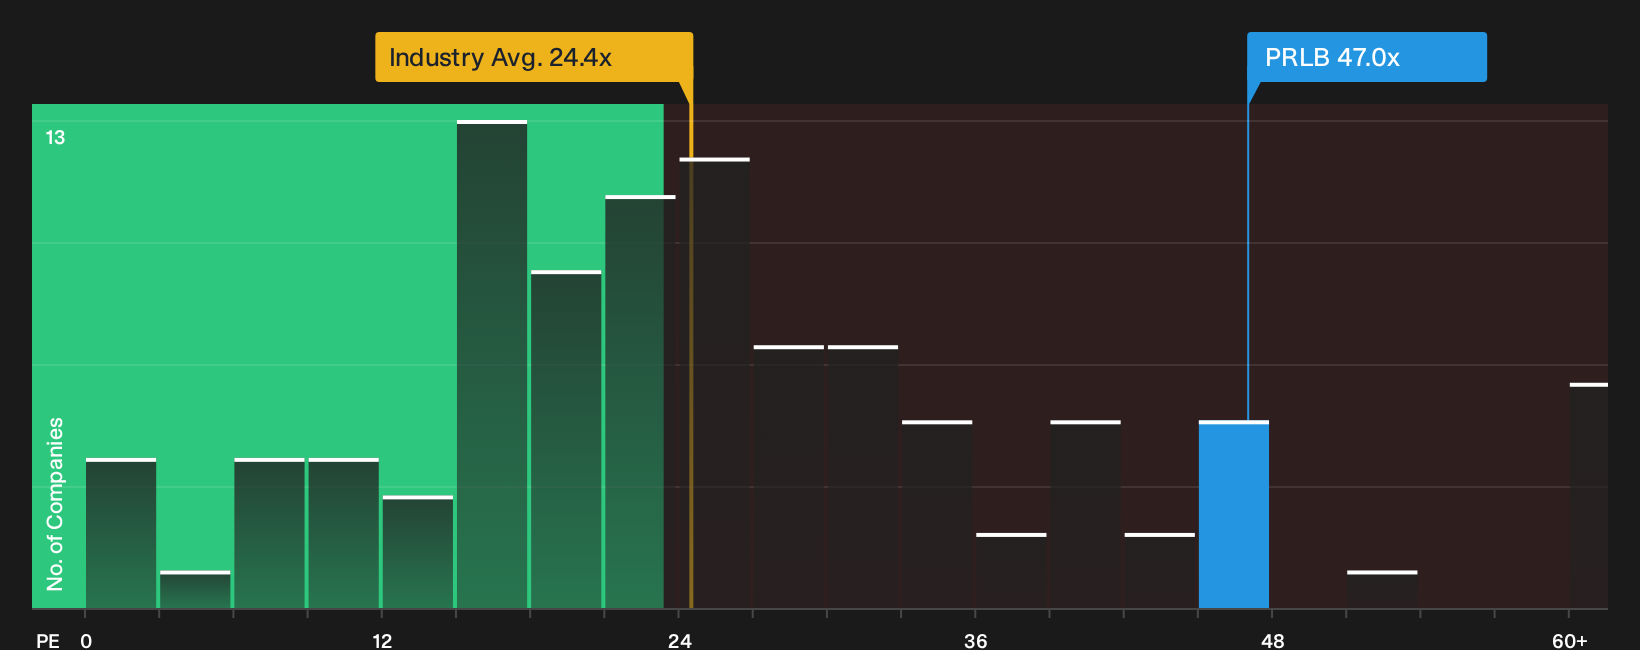
The SWS DCF model points to Proto Labs trading 24.9% below an estimate of fair value at $91.72, yet the market is still putting a rich P/E of 47x on the stock versus 24.2x for the US Machinery industry and 21.5x for peers, while the fair ratio sits at 29.6x.
This gap suggests investors are paying a premium multiple for Proto Labs even though the DCF flags upside. This raises a simple question for you as a shareholder or potential buyer: Is the story strong enough to keep that P/E from drifting closer to the fair ratio over time?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in the Proto Labs story points to optimism, yet the recent share price move means you need to weigh the trade off yourself and potentially act quickly. To see exactly which bright spots our model is flagging, review the 4 key rewards
Looking for more Proto Labs investment ideas?
If Proto Labs has sharpened your focus, do not stop here. Use the screener to surface fresh opportunities that fit your portfolio and time horizon.
- Target higher potential by scanning a curated pool of 19 high quality undiscovered gems that combine strong fundamentals with less crowded ownership.
- Prioritise resilience by filtering for 29 resilient stocks with low risk scores that emphasise sturdier balance sheets and steadier business profiles.
- Hunt for value by lining up 33 high quality undervalued stocks that pair solid financial quality with prices below internal estimates.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com