


Learn Why The Bull Case For Old Republic International Stock Could Change Following Investment Losses
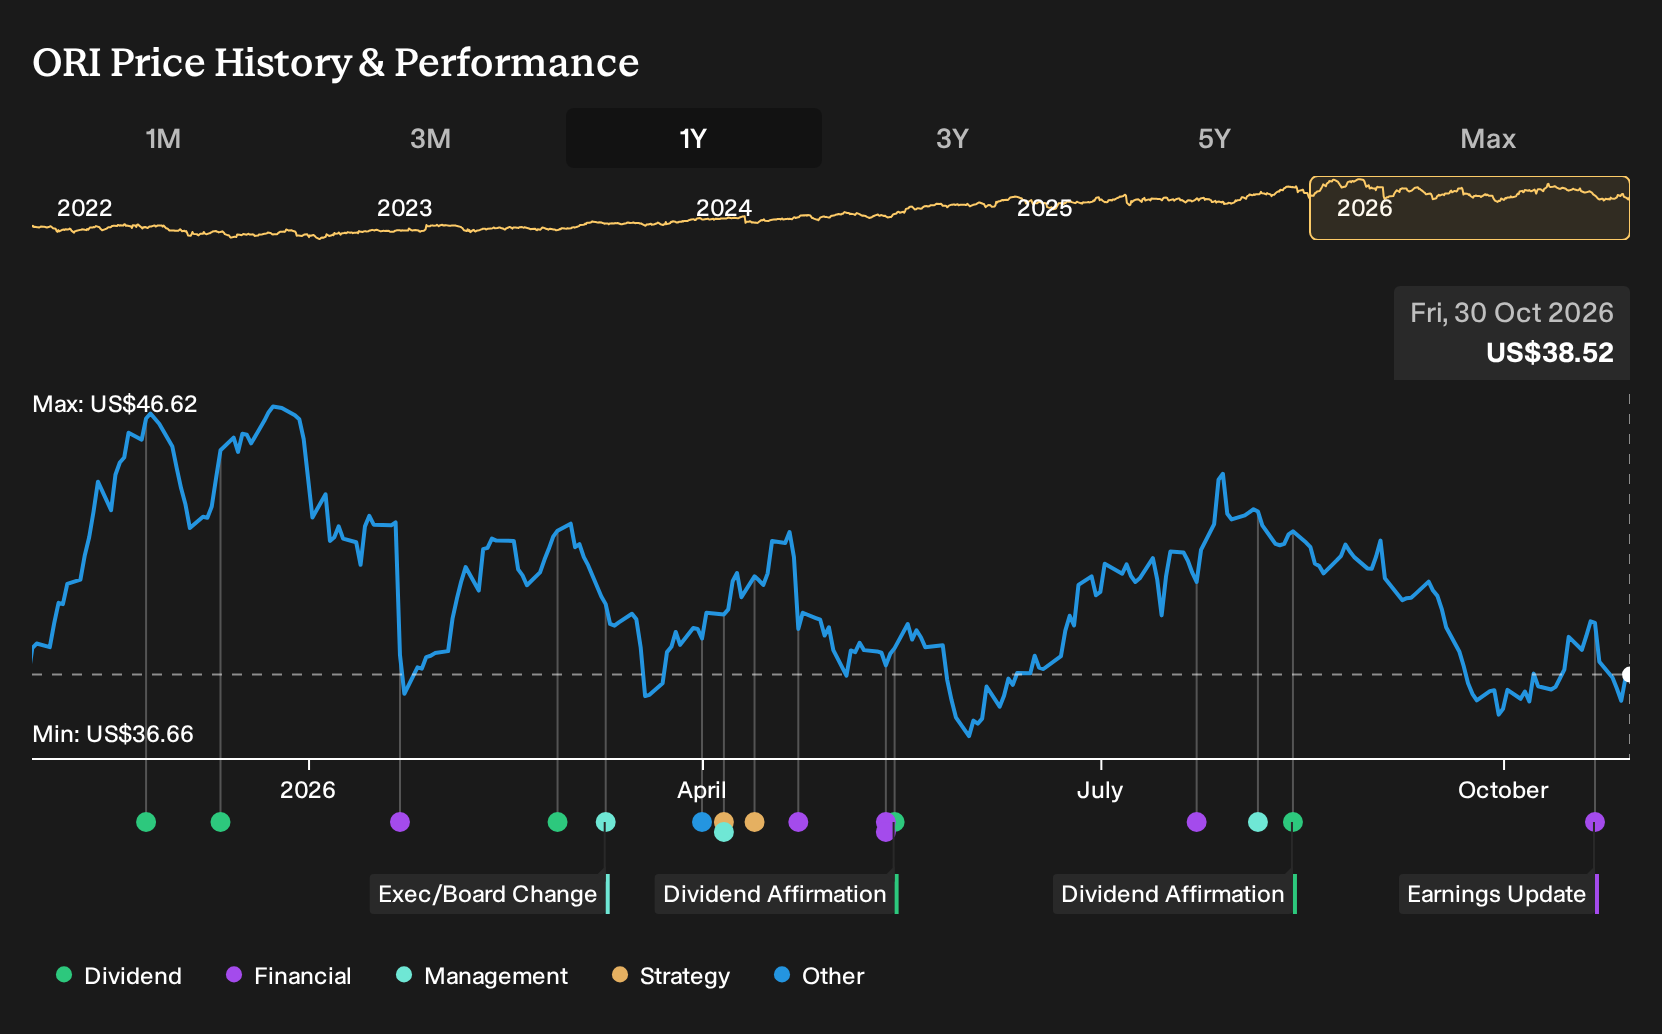
- Old Republic International reported third quarter 2026 revenue of US$2,550.5 million, with net income of US$243.2 million and diluted EPS from continuing operations of US$0.99, alongside a nine month net income of US$895.6 million.
- The latest quarter combined weaker profit, influenced by investment losses, with a US$124.9 million bargain purchase gain from the ECM Insurance Company acquisition, which reshapes how earnings quality is viewed.
- The focus will now be on how Old Republic International's investment narrative incorporates weaker quarterly earnings tied to investment losses.
Old Republic International Investment Narrative Recap
To own Old Republic International, you need to be comfortable with an insurance group that leans heavily on underwriting discipline, technology projects and specialty build outs rather than rapid premium expansion. The third quarter result brought softer profit, influenced by investment losses, but nine month earnings still reflect a business generating substantial cash that can support those ongoing projects.
The key near term swing factor remains Specialty Insurance profitability and expense control. Higher costs tied to technology and expansion, plus prior reserve strengthening, already pressured margins. If those do not translate into cleaner underwriting ratios, the biggest risk is that earnings stay compressed while capital returns and investment losses keep quarterly results choppy.
The most relevant development here is the ECM Insurance Company acquisition, which produced a US$124.9 million bargain purchase gain in the latest quarter. That one off gain sits on top of a broader push into farm and agriculture lines, where management had previously outlined combined ratio targets between 90% and 95%.
For you as a shareholder, the real question is execution. ECM adds another piece to Specialty Insurance at a time when that segment already faces weaker profitability and higher expenses. If underwriting from ECM tracks closer to the group’s targets, it could support the broader catalyst of more balanced earnings between investment income and core insurance results while helping offset pressure from slower premium growth elsewhere.
Old Republic International's analyst narrative points to revenue of US$11.0b and earnings of US$674.8 million by 2029, based on assumed yearly revenue growth of 4.1%. This implies earnings today are US$1.1b and would need to decline by about US$425 million to reach the 2029 consensus forecast.
Uncover how Old Republic International's fair value indicates a 13% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$43.5 to just under US$78, which shows how far opinions on Old Republic International can stretch. Those views pre date the third quarter investment losses and the ECM gain, so treat them as one input and weigh them against softer Specialty Insurance profitability and higher technology spending.
Explore another Old Republic International fair value estimate, including one that suggests it could be worth just $43.50.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Old Republic International research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Old Republic International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Old Republic International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Old Republic International?
If Old Republic International has sharpened your thinking about risk, earnings quality and capital strength, use that same lens to size up other opportunities with the Simply Wall St Screener. You can filter by balance sheet resilience, income potential or unloved fundamentals and quickly build a shortlist that matches how you like to invest.
- For investors who want staying power first and returns second, start with a list of solid balance sheet and fundamentals (24 results) that can help you focus on companies built to handle tougher periods without stressing their finances.
- If your priority is income you can monitor over time, scan a 5 dividend fortresses and zero in on payouts that line up with your tolerance for risk and drawdowns.
- If you prefer to hunt for mispriced stories before the crowd arrives, work through a 19 high quality undiscovered gems and see which businesses pair cleaner fundamentals with limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com