


Pfizer (PFE) Scores Legal And Product Wins, Is The Stock Now Too Expensive?
Pfizer (PFE) just cleared a key legal overhang in Europe, with the Unified Patent Court ruling Enanta Pharmaceuticals’ Paxlovid-related patent invalid and rejecting the infringement claim against the drugmaker.
The legal win fits into a series of supportive headlines for Pfizer, and the market reaction reflects that shift in sentiment. The share price is up 21.2% year to date with a 90 day share price return of 21.9%, while the 1 year total shareholder return of 32.5% indicates recovering momentum after weaker 5 year total shareholder returns.
Spot inflection points like Pfizer's across a curated 19 high quality undiscovered gems that pair strong fundamentals with under-the-radar stories.Pfizer now appears to be a solid pharmaceutical powerhouse again, supported by recent legal and product wins. After reaching a 52-week high followed by a sharp rerating, the key question is whether that strength is already fully priced in, or if there is still room for further adjustment.
Most Popular Narrative: 5.7% Overvalued
Pfizer last closed at $30.52, compared with a widely followed fair value estimate of $28.88 that is based on a detailed cash flow narrative using a 7.24% discount rate. That gap puts more weight on how confidently you view the future mix shift away from COVID treatments and the impact of cost savings.
Expansion of launched and acquired products, which management now describes as running at around a US$13b annualized revenue rate and growing in the 20% range, continues to support the view that Pfizer can further shift its mix toward non COVID therapies and sustain revenue as loss of exclusivity pressures emerge. Execution on large scale productivity and manufacturing programs, now expected to deliver about US$9.7b in net savings through 2029 after already removing US$7.2b from the cost base, provides a longer runway for operating margin support and underpins earnings capacity while Pfizer increases R&D spending on oncology and obesity.
See why 551 investors see Pfizer as 6% overvalued.
Result: Fair Value of $28.88 (OVERVALUED)
Still, Pfizer’s story could change quickly if drug pricing reforms bite harder than expected or if key oncology and obesity programs fail to meet current expectations.
Find out about the key risks to this Pfizer narrative.
Another View: Pfizer Through The Earnings Lens
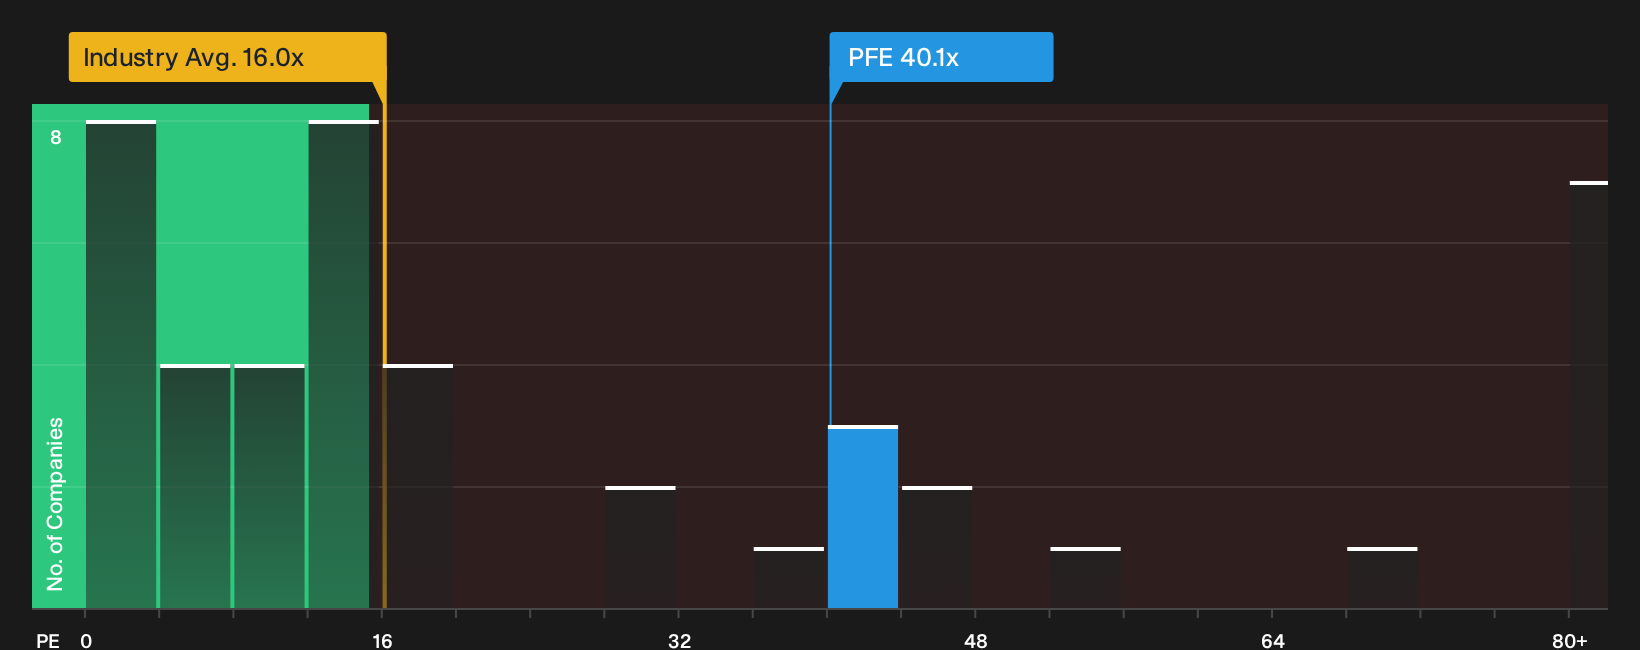
The first narrative pins Pfizer at about 5.7% above a $28.88 fair value, yet the picture shifts once current earnings multiples are used. On a P/E of 40.1x, the stock trades above both its own fair ratio of 29.6x and the US pharmaceuticals average of 16x, which lifts the risk that sentiment cools before earnings catch up.
That richer multiple also looks cheaper than peer levels around 68.6x. Investors weighing Pfizer have to decide which crowd the valuation could gravitate toward: the wider sector, or the fair ratio the model suggests is more sustainable over time.
For a closer look at how those earnings-based signals stack up against each other, and what that might mean for future upside or downside, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Pfizer so far. If you want your view to be shaped by hard numbers rather than headlines, weigh up the 2 key rewards and 4 important warning signs.
Looking for more Pfizer-sized opportunities?
Do not stop your research at Pfizer. Use data driven screens to spot fresh ideas that fit your style before the crowd starts paying attention.
- Pinpoint potential mispricings by scanning a curated set of 33 high quality undervalued stocks that combine solid cash flows with disciplined balance sheets.
- Build a steadier income stream by reviewing 5 dividend fortresses offering yields that could complement or contrast with what Pfizer provides today.
- Reduce portfolio stress by focusing on 29 resilient stocks with low risk scores that our models flag with resilient fundamentals and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com