


OLBA DVx HEALTHCARE (TSE:2689) Q1 Results Pressure A Premium Stock Case
OLBA DVx Healthcare has come into this Q1 2027 earnings release with a stock that has gone largely sideways in recent months and a valuation that already prices in a lot of hope, trading on a P/E of 20.2x above both peer and sector averages. The fresh result lands with a jolt. Revenue for the quarter sits at ¥31,454 million, yet basic EPS is only ¥5.12, a sharp profit squeeze after previously richer quarters. If today’s price reaction looks calm, the sentiment story is not. The market is weighing a premium multiple against visibly thinner earnings power.
Love the premium story around OLBA DVx HEALTHCARE but concerned that thinner earnings might not support a 20.2x P/E over time? You can balance that risk by comparing it with our list of solid balance sheet and fundamentals stocks (22 results)
Q1 2027 Earnings Summary
- Revenue (Q1 2027 vs. Q1 2026): ¥31,454 million vs. ¥30,824 million (modest top-line increase)
- Net Income (Excl. Extra Items, Q1 2027 vs. Q1 2026): ¥36 million vs. ¥166.754 million (sharp decline in quarterly profit)
- Basic EPS (Q1 2027 vs. Q1 2026): ¥5.12 vs. ¥28.14 (very large drop in earnings per share)
- Trailing 12-Month Net Profit Margin (latest vs. prior year): 0.8% vs. 1.1% (profitability compressed over the year)
Ask Charlie what OLBA DVx HEALTHCARE’s rich P/E really prices in.
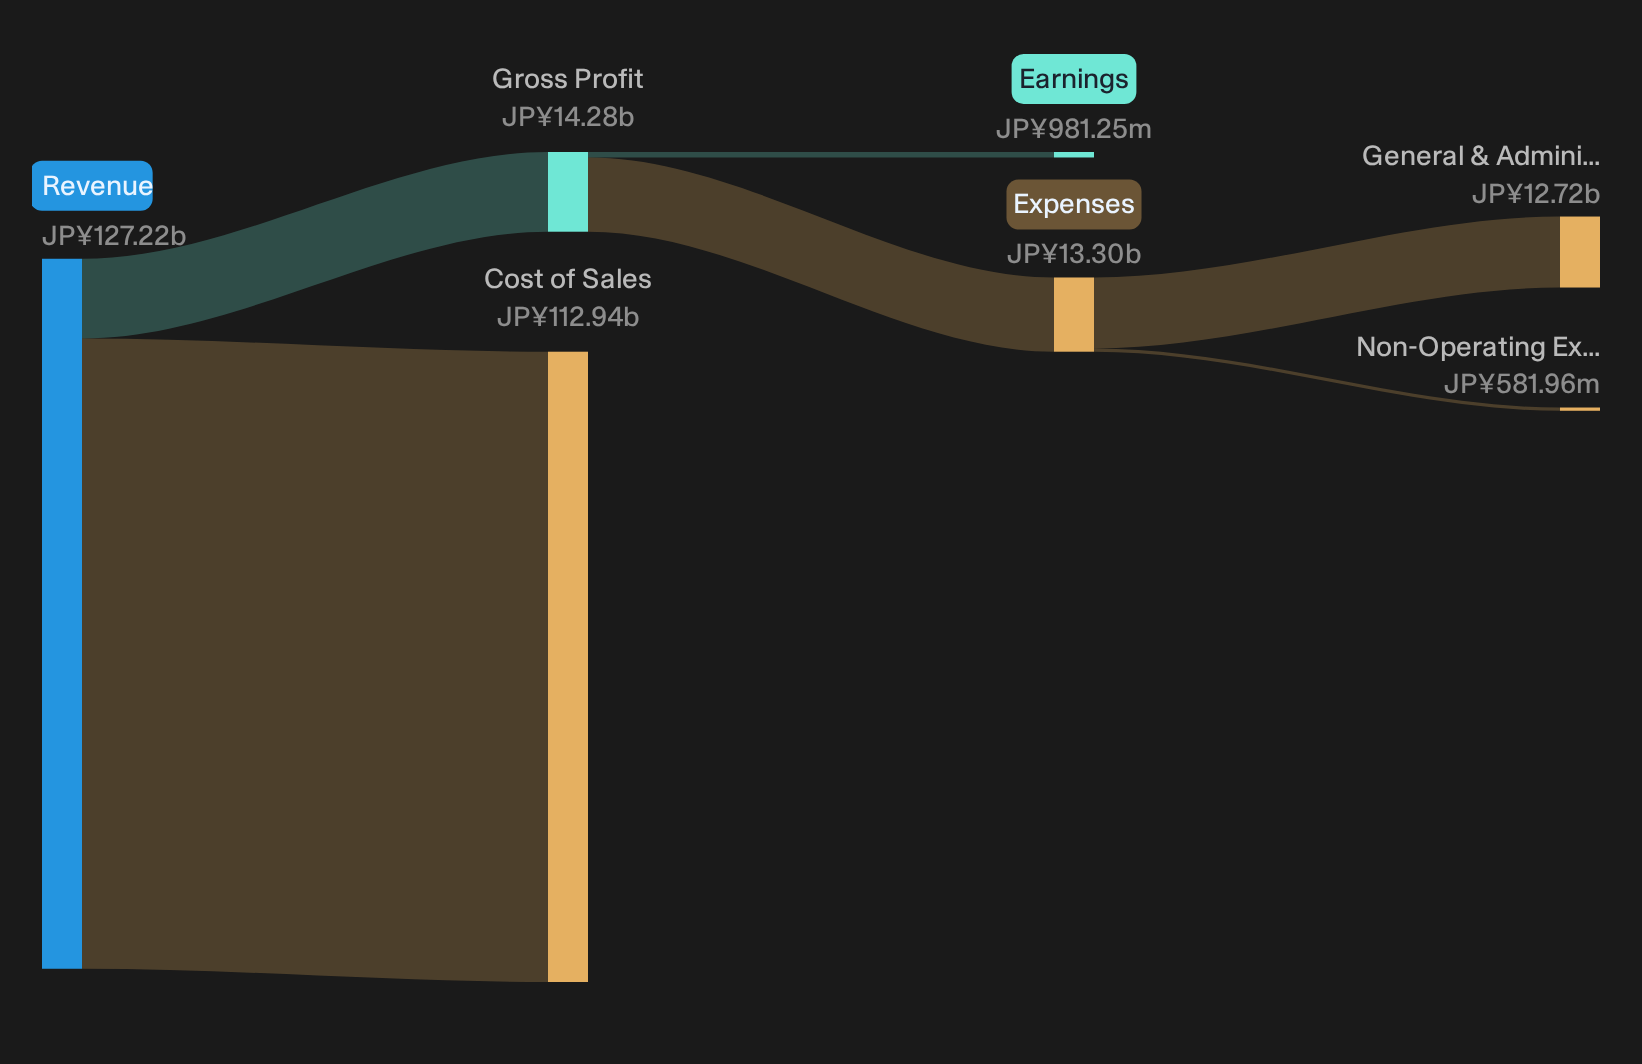
OLBA DVx HEALTHCARE: Testing The Bullish Story
For anyone leaning into OLBA DVx HEALTHCARE as a steady healthcare platform, the latest figures give mixed support. Revenue of ¥31,454 million versus ¥30,824 million a year ago fits the idea of a business still plugged into Japan’s medical and care demand. The problem is earnings power. Net income excluding extras dropped to ¥36 million and basic EPS slid to ¥5.12. That pattern points to volume and customer ties holding up while the model absorbs heavier cost or pricing pressure.
Profit Squeeze Keeps The Bear Case Alive
Bears get more reinforcement than pushback from this quarter. Net income excluding special items fell from ¥166.754 million to ¥36 million and basic EPS dropped from ¥28.14 to ¥5.12. The trailing 12 month net profit margin eased from 1.1% to 0.8%. For a distributor and service provider like OLBA DVx HEALTHCARE, that compression suggests limited current pricing power and rising operating strain. Revenue is not cracking, which reins in the most severe downside worries, but the thinner margin profile keeps the risk narrative very much in play.
After a 20.2x P/E meets shrinking margins and past shareholder dilution, it is worth asking if this pressure signals deeper structural fragility. Review the full risk analysis for OLBA DVx HEALTHCARE which shows 4 important warning signsHunt For Stronger Earnings Engines
OLBA DVx HEALTHCARE highlights how a high valuation can meet slimmer profits. The real opportunity is finding stocks that could be low debt before the market corrects them.
- Company 1 - 35% below our estimate - uses AI driven hiring and local service platforms to align fees with customer transactions.
- Company 2 - 18% below our estimate - expands a maintenance focused elevator network by adding sales staff to win recurring service and modernization contracts.
- Company 3 - 45% below our estimate - builds an AI native security platform that moves customers toward subscriptions for recurring software and monitoring.
Three companies from the same screener. Open all 22 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com