


Eslead (TSE:8877) Q2 Results Spotlight Strong Earnings And Cash Flow Risk
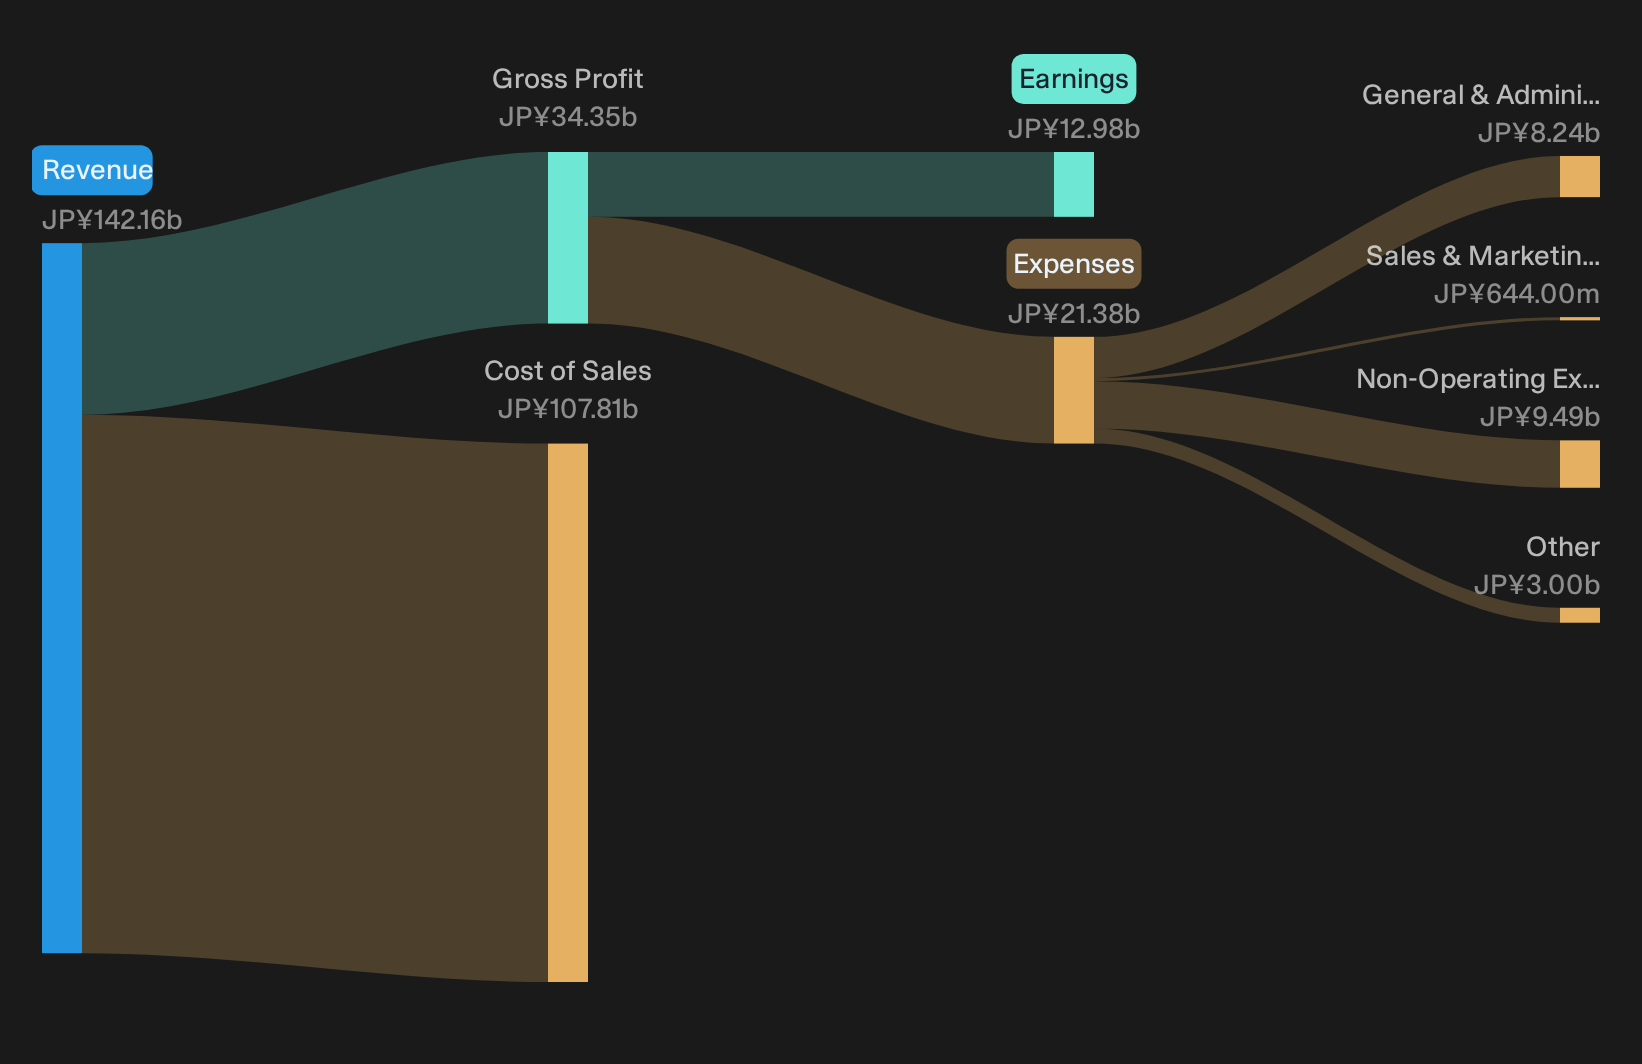
Eslead stock closed at ¥5,080 on 30 October, only a modest move over the past month, yet the fresh Q2 2027 figures were anything but quiet. Basic earnings per share hit ¥298.78 with net income of ¥4,610 million, both well above the recent quarterly run rate for this residential developer.
In the short term, that kind of jump can look like a simple earnings pop. Looking over a longer period, with trailing twelve month earnings of ¥12,979 million and a P/E of 6x, the key question is how long this profit strength can run against balance sheet and cash flow pressure.
Like the earnings power at Eslead but uneasy about the balance sheet and cash flow pressure hinted at in these results? Compare this quarter with companies screened for stronger fundamentals and steadier financing profiles using the list of solid balance sheet and fundamentals stocks (22 results).
Q2 2027 Eslead Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥43,443 million vs. ¥26,960 million (up about 61%)
- Net Income (Q2 2027 vs. Q2 2026): ¥4,610 million vs. ¥3,178 million (up about 45%)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥298.78 per share vs. ¥206.05 per share (up about 45%)
- Trailing 12-Month Net Income (Q2 2027 vs. Q2 2026): ¥12,979 million vs. ¥9,119 million (up about 42%)
Earnings tell one story for Eslead, but valuation focused investors often care more about how much cash actually comes through the door and how reliably that cash can support payouts and obligations over time. When you line up Eslead's underlying cash generation against its current share price and dividend commitments, the stock could be a solid 26% overvalued.
Eslead earnings power backing a constructive view
For anyone leaning positive on Eslead, the latest quarter gives the story some support. Revenue of ¥43,443 million and net income of ¥4,610 million both sit meaningfully above the prior year period, and earnings per share tracks the same direction. Trailing 12 month profit of ¥12,979 million adds weight to the idea that this is not only a single quarter spike. For a diversified real estate platform that mixes development with services, that kind of consistent earnings base matters for investors who care about resilience across cycles.
Profit strength meets ongoing balance sheet questions
Bears worry first about balance sheet strain and cash conversion at Eslead rather than the income statement. The latest figures do not resolve those concerns, since there is no fresh disclosure here on leverage, funding costs, or operating cash flow. Stronger net income can ease some pressure, yet short term gains in profit do not automatically translate into safer financing or smoother cash generation. For a property developer with multiple business lines, that gap between accounting earnings and hard cash remains a reasonable risk flag for more cautious investors.
After a quarter where earnings look strong but leverage, funding costs and cash conversion are still open questions, it is worth asking whether Eslead's current pressures around debt coverage and dividend funding are isolated issues or early signals of deeper structural fragility. Review the full risk analysis for Eslead which shows 2 important warning signsHunt Balance Sheets Before Crowds
Eslead just posted firm earnings power while balance sheet questions stayed unresolved. The real opportunity is finding stocks that could be low debt before the market revalues them.
- Company 1 - 45% below our estimate - uses an AI-native security stack to grow subscription revenue from a consolidated platform rather than point products.
- Company 2 - 35% below our estimate - ties hiring fees and software pricing directly to job volume and transaction value through automated matching tools.
- Company 3 - 18% below our estimate - adds sales capacity to win more long term elevator maintenance contracts that deepen recurring modernization and service work.
Those are three of them. See every one of the 22 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com