


EIZO (TSE:6737) Stock Can Q2 Earnings Sustain Margin Strength?
EIZO walked into this Q2 2027 earnings release with the stock drifting, down about 6% over the past week and past month, and only slightly positive over three months. The headline result was clear: net income reached ¥3,723m, with basic earnings per share at ¥96.47, while revenue held at ¥20,666m.
The real story for you is the margin picture. Profitability has been running far stronger over the last year, helped by a very large one-off gain of about ¥11.3b that flatters trailing earnings and feeds a P/E of 9.8x that looks low against tech peers. The market now has to decide whether today’s muted price reaction reflects healthy scepticism or an emotional overreaction to past windfalls that are unlikely to repeat.
Like the high profit margin story at EIZO, but worried that a one time gain is skewing the P/E and masking what is sustainable? Compare that setup with our 14 high quality undervalued stocks
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): ¥20,666m vs. ¥20,536m (broadly flat, slight uptick)
- Net Income (Excl. Extra Items, Q2 2027 vs Q2 2026): ¥3,723m vs. ¥623m (very large year on year increase)
- Basic EPS (Q2 2027 vs Q2 2026): ¥96.47 vs. ¥15.13 (very large year on year lift)
- Net Profit Margin (Trailing 12 Months vs Prior Year): 13.5% vs. 5.4% (margin level higher, reflecting stronger profitability before considering the one off gain)
A big one‑time gain boosted EIZO’s profit jump. Ask Charlie which part of EIZO’s earnings was a one‑off.
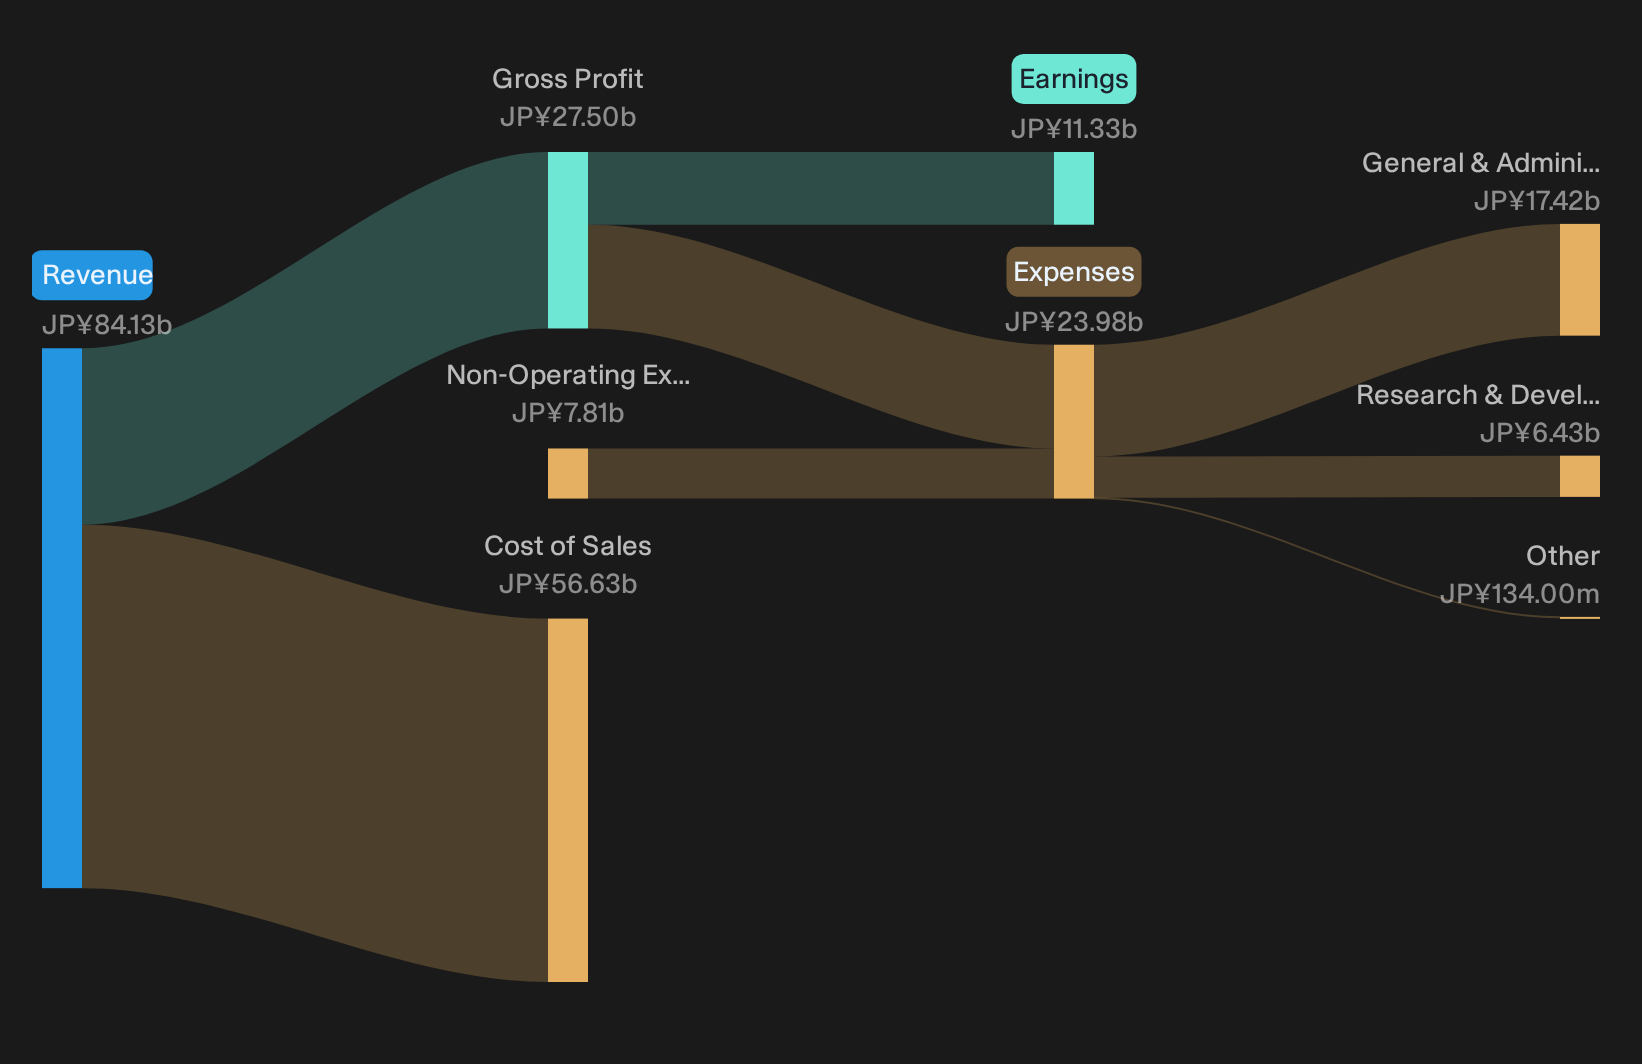
EIZO earnings, niche resilience and margin strength
The quarter backs up the idea that EIZO has a resilient specialist franchise. Revenue stayed broadly steady year on year, which fits a story of steady demand across medical, industrial and control room clients rather than volume chasing. Profitability is where the case looks strongest. Net income excluding extra items reached ¥3,723m and EPS climbed to ¥96.47, while the trailing net margin stepped up to 13.5%. For a hardware focused business, that combination of flat sales and higher profits points to firmer pricing power and a better mix.
Short term setbacks and questions on sustainability
There is a flip side. Recent share performance, with the stock down around 6% over one and three months, indicates that investors are cautious despite the solid Q2 2027 print. The very large ¥11.3b one off gain feeding into trailing earnings creates uncertainty about how much of the current margin profile is repeatable. Revenue is not surging, so any slip in underlying profitability could matter quickly. For now, the results ease fears about immediate stress, but they do not fully settle the debate on sustainability.
Access what the street is quietly baking into its models for EIZO, where the current ¥2,909 share price looks settled on the surface, but the multi year EPS paths may point to sharply different inflection points by checking the analyst estimates for EIZO
Hunt Quiet Balance Sheet Stories
EIZO just reminded you that clean earnings and muted trading can appear together. The real opportunity is finding stocks that could be low debt before the market evaluates them.
- Company 1 - 45% below our estimate - target enterprises consolidating security on unified platforms as AI incidents increase.
- Company 2 - 35% below our estimate - link hiring budgets to performance-based job ads as recruiters use automated screening.
- Company 3 - 18% below our estimate - convert one-off elevator projects into maintenance contracts as sales teams focus on older equipment.
Three companies from the same screener. Open all 22 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com