


Marvelous (TSE:7844) Stock Q2 Earnings Put Revenue Durability In Focus
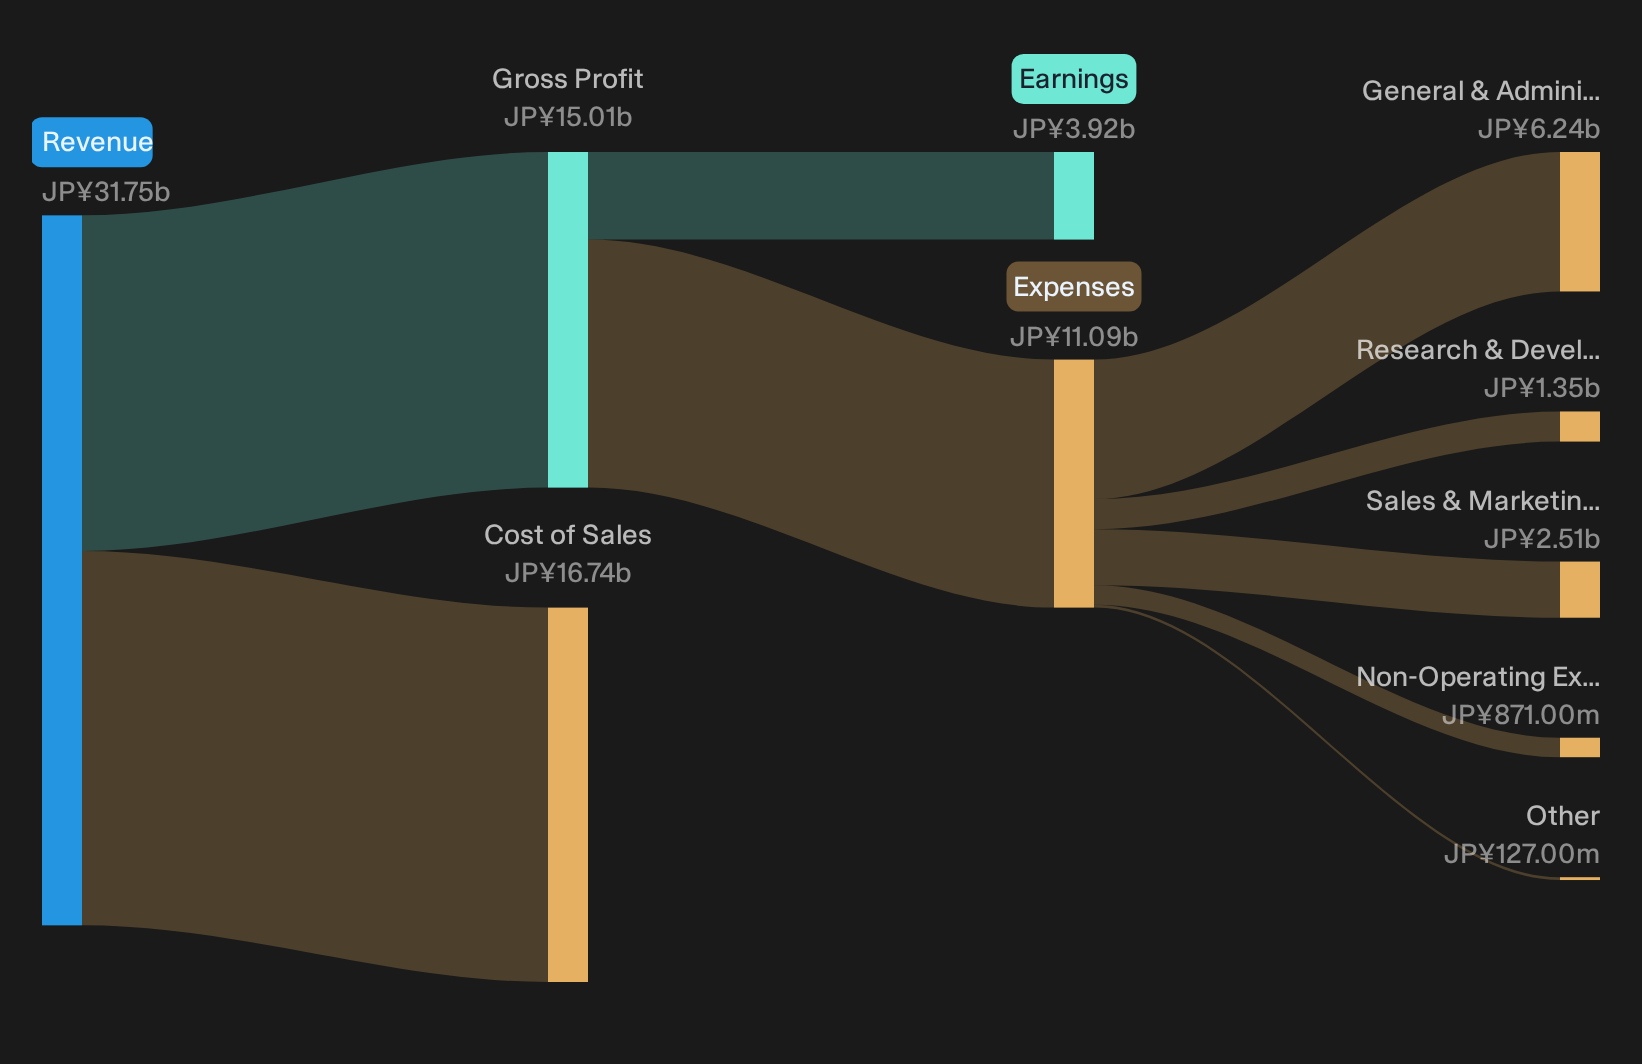
Marvelous came into this earnings print with a reputation as a cheap entertainment stock on an 8.3x P/E, trading at ¥537, and priced as if the best days were behind it. Q2 2027 results told a different story. Basic earnings per share jumped to ¥22.93 and net income reached ¥1,321m, highlighting profitability that sits awkwardly beside a valuation flagged as far below an estimated fair value. The share price barely moved on the day. The gap between that muted reaction and the strength in recent profits is now the central investment question.
Impressed by Marvelous delivering strong earnings on what still looks like a value label, yet uneasy about whether this is a rare exception or part of a wider pattern of underpriced quality. Benchmark those instincts against our 14 high quality undervalued stocks
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥7,792m vs. ¥11,542m (change of ¥3,750m, down 32.5%)
- Net Income (Q2 2027 vs. Q2 2026): ¥1,321m vs. ¥72m (increase of ¥1,249m, very large improvement)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥22.93 vs. ¥1.19 (rise of ¥21.74, very large jump)
- Trailing 12-Month Net Income (Q2 2027 TTM vs. Q2 2026 TTM): ¥3,916m vs. ¥924m (gain of ¥2,992m, up about 4.2x)
Big earnings jump, low valuation, and falling forecasts collide. Ask Charlie what makes Marvelous look this cheap.
Marvelous earnings, testing the quality bull story
On the optimistic side, Marvelous now looks more like a profit engine than a pure hit lottery ticket. Net income moved from ¥72m to ¥1,321m, and trailing 12 month earnings climbed to ¥3,916m from ¥924m. That kind of step up fits a narrative where a cross media IP platform starts to monetise its catalogue more effectively. The stable 90 day return close to 10% also hints that equity holders have not been forced to price in distress.
Volatile top line keeps the Marvelous bear alive
The bear story is not broken. Revenue in Q2 went from ¥11,542m to ¥7,792m, a 32.5% drop that reinforces how hit driven this entertainment model can be. Profitability looks far better, yet the path to those earnings clearly did not rely on steady sales growth. For readers worried about concentration in a few projects, this pattern backs that concern. Flat performance over 7 days and only modest gains over 30 days suggest the market is not ready to treat this as a low risk cash machine.
After revenue swinging this hard, it is fair to ask whether Q2 is a one off or a symptom of deeper fragility. Scan the risk analysis for Marvelous which shows 2 important warning signs to see whether concentration risk, earnings volatility and dividend stability are already flashing as structural warnings.Spot Hidden Balance Sheet Stories
Marvelous shows how earnings strength and share price reaction do not always move in step. The real opportunity is finding stocks that could be low debt before the market corrects them.
- Company 1 - 45% below our estimate - uses an AI focused security platform to move customers toward recurring software and managed service contracts.
- Company 2 - 18% below our estimate - expands a maintenance focused elevator service network by hiring sales staff to win recurring modernization and repair agreements.
- Company 3 - 35% below our estimate - builds AI driven matching tools that guide employers and service providers toward higher value digital acquisition channels.
Three companies from the same screener. Open all 22 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com