


Hamakyorex (TSE:9037) Q2 Results Expose Pressure On Profit Growth
Hamakyorex stock came into the Q2 2027 results with a flat near term record, down about 3% over the past week but slightly higher over one and three months, as investors weighed modest gains against caution. The new quarter lands with a clear headline. Revenue reached ¥42,323m while basic earnings per share printed at ¥28.63, softer than in the previous two quarters. Short term traders may focus on that step down in profitability. Longer horizon holders are more likely to look at the broader earnings trend and the current valuation discount.
Love the modest revenue base at Hamakyorex but uneasy about the softer earnings per share this quarter? Check out the list of solid balance sheet and fundamentals stocks (22 results).
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥42,323m vs. ¥38,032m (up about 11.3%)
- Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): ¥2,120m vs. ¥2,342m (down about 9.5%)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥28.63 vs. ¥31.64 (down about 9.5%)
- Trailing Twelve Month Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): ¥10,973m vs. ¥9,478m (up about 15.8%)
Earnings only tell part of Hamakyorex's story, since reported profit can move around quarter to quarter while the underlying cash that flows through the business often paints a steadier picture of what shareholders are really paying for.
When you focus on Hamakyorex's cash generation rather than this quarter's EPS dip, the stock could be a striking 39% undervalued.
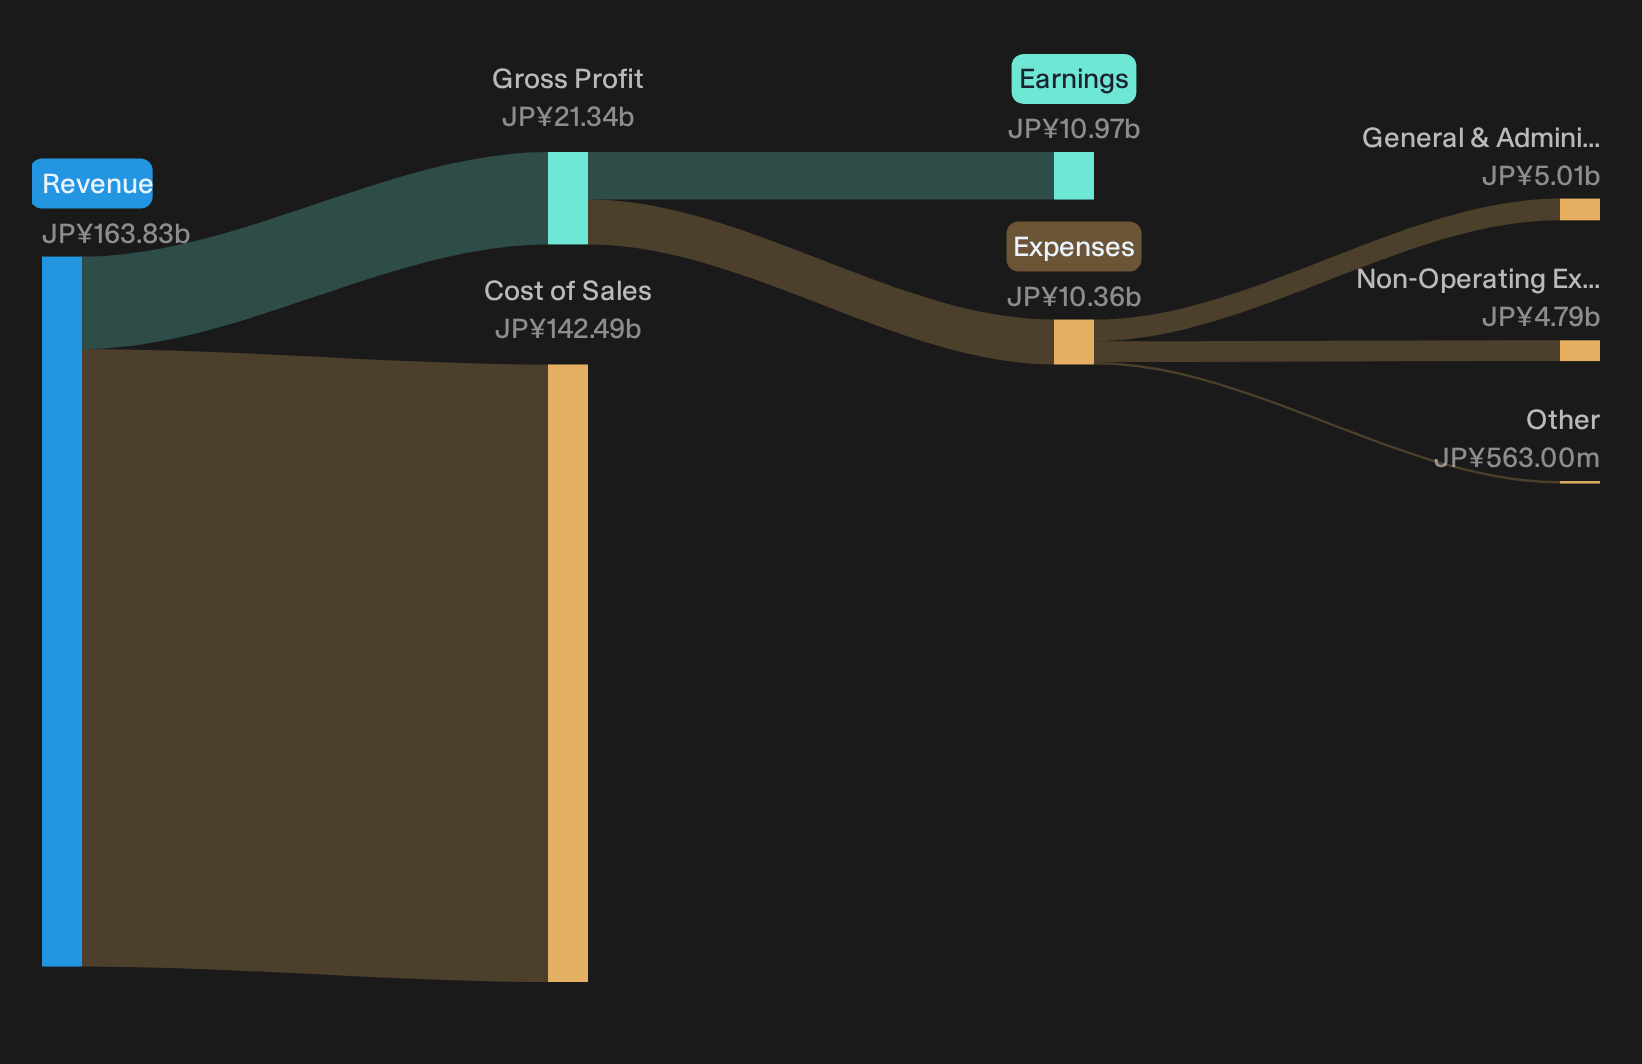
Hamakyorex bullish story leans on top line resilience
Hamakyorex still offers something for optimists. Revenue reached ¥42,323m and is higher than the ¥38,032m booked a year earlier, which fits the narrative of a logistics player with relatively steady volume-linked demand. Trailing twelve month net income excluding extra items sits at ¥10,973m versus ¥9,478m a year ago, so earnings power over a longer window has moved in the same broad direction as sales. For a business pitched as a steady enabler in Japanese logistics, that combination of firmer top line and higher trailing profit keeps the bullish story intact.
Short term margin squeeze underlines Hamakyorex bear case
There is also real fuel for caution. Quarterly net income excluding extra items declined from ¥2,342m to ¥2,120m and basic EPS fell from ¥31.64 to ¥28.63, which fits the concern that rising costs can bite into trucking and 3PL margins. Returns over the last week are down about 3.4%, hinting that investors have reacted to this softer profitability. For anyone worried about labor, fuel or regulatory pressures in Japanese transport, this step down in near term earnings gives that more cautious thesis fresh support.
Reveal where the surface looks calm, but the multi year projections start to pull apart. Access the analyst estimates for HamakyorexHunt For Balance Sheet Outliers
Hamakyorex shows how a single quarter can sharpen views on earnings power and valuation. The real opportunity is finding stocks that could be low debt before the market corrects them.
- Company 1 - 35% below our estimate - uses AI-driven hiring tools and sponsored listings to capture recruitment and local services spending on its platforms.
- Company 2 - 18% below our estimate - expands its salesforce so more elevator owners switch maintenance and modernization contracts, increasing installed base density and recurring service revenue.
- Company 3 - 45% below our estimate - shifts customers onto an AI-native security platform so subscription contracts and managed protection replace one-off software licenses.
Those are three of them. See the full list of 22 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com