


METAWATER (TSE:9551) Could Be 1% Undervalued As Half Year Results Stir Debate
METAWATER (TSE:9551) is back in focus after half year results to September 30, 2026 showed sales of ¥86,532 million, net income of ¥64 million and basic EPS of ¥1.47.
The latest move in METAWATER’s share price has been sharp, with a 1-day share price return of 23.33% and a 7-day gain of 25.64% taking the stock to ¥3,700.0. The 3-year total shareholder return of 95.07% and 5-year total shareholder return of 110.04% point to strong longer term compounding, suggesting recent momentum has been building as investors react to the mixed half year earnings update and the board’s work on revising forecasts and dividends.
Scan how METAWATER’s sharp move compares with other infrastructure and capital goods plays by reviewing our curated list of 41 power grid technology and infrastructure stocks.
After a 23.33% one day jump and a half year scorecard that mixes higher sales with thinner profits, METAWATER now presents a practical fork in the road: lean in at ¥3,700 or wait for a cooler entry as valuations stack up next.
Preferred P/E of 18.8x: Is it justified?
Valuation on METAWATER now hinges on a P/E of 18.8x at a closing price of ¥3,700, which points to a richer tag than many peers, with a DCF estimate of fair value sitting very close by at ¥3,740.6.
The P/E ratio compares what investors pay per share to the earnings that each share generates. For an infrastructure oriented machinery business like METAWATER, it gives a quick read on how much of a premium the market is willing to pay for current and forecast profit, especially when earnings dipped over the past year even as longer term growth has been positive.
METAWATER trades on 18.8x earnings while the wider JP Machinery industry sits at 12.6x and the closer peer group averages 13.2x. That is a clear premium. It also runs well above an estimated fair P/E of 14.4x that our models suggest, a level the valuation multiple could move toward if expectations around profit or return on equity at 9.5% reset.
Explore the SWS fair ratio for METAWATER.
Result: Price-to-Earnings of 18.8x (OVERVALUED)
Still, any disappointment on earnings quality or a cut to analyst price targets could quickly pressure METAWATER’s premium P/E and cool recent enthusiasm.
Find out about the key risks to this METAWATER narrative.
Another View on METAWATER’s Value
The P/E premium paints METAWATER as expensive, yet the SWS DCF model tells a slightly different story. At ¥3,700 the stock sits about 1.1% below an estimated fair value of ¥3,740.6, which frames the recent move less as excess and more as a tight valuation debate.
The gap between an 18.8x earnings multiple and a DCF value that is only marginally higher raises a practical question for you. Is the share price now baking in most of the future cash flow upside, or is a small discount enough comfort for fresh capital?
Look into how the SWS DCF model arrives at its fair value.
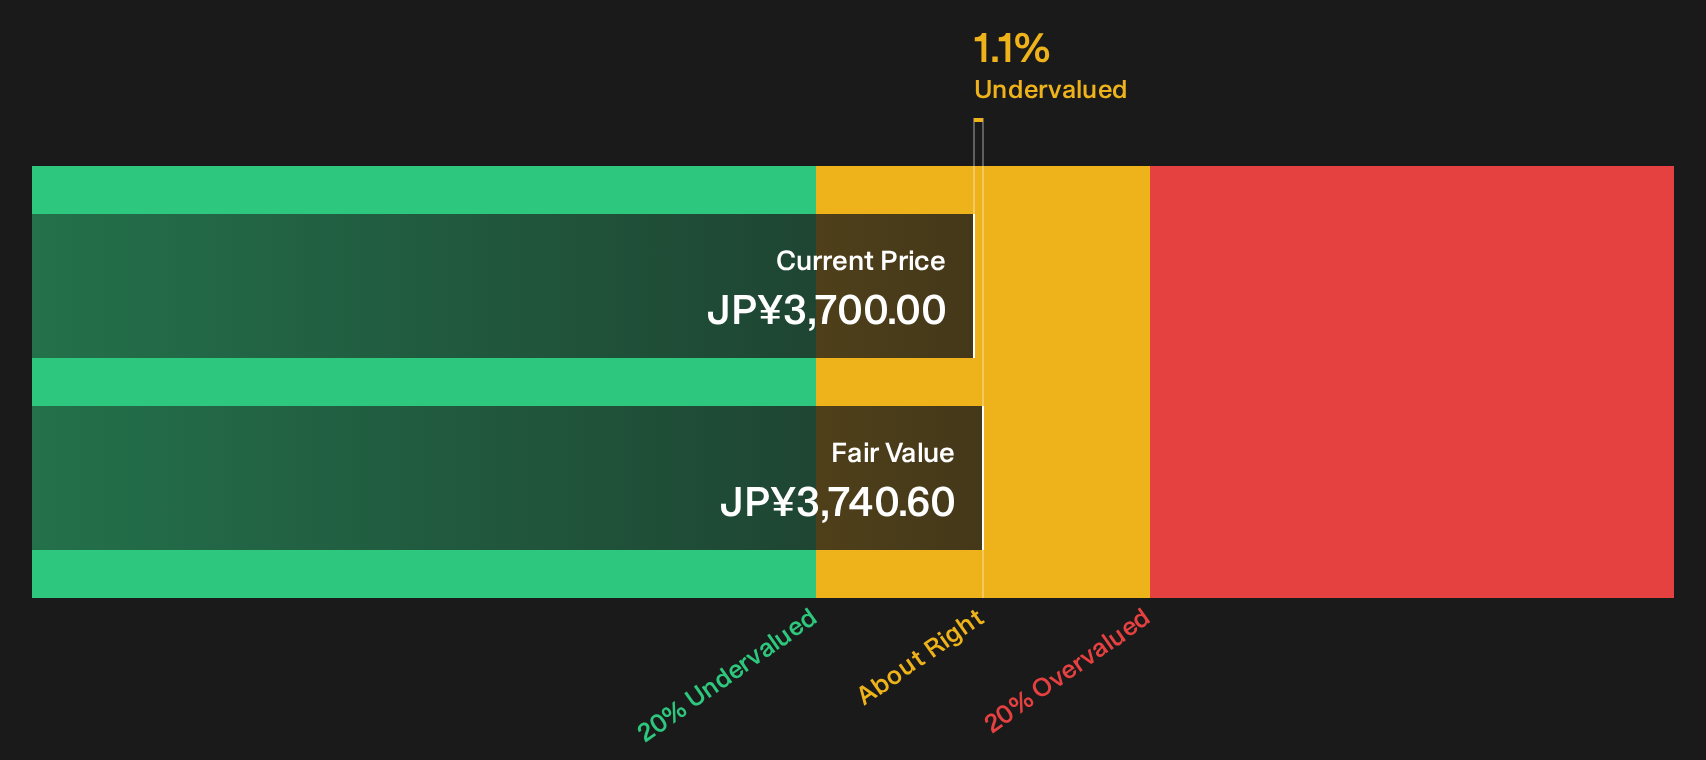
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out METAWATER for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on METAWATER’s valuation and fundamentals mean the real question is what you make of the trade off between potential rewards and flagged risks. Act while this move is fresh in your mind and weigh both sides carefully through the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond METAWATER?
If METAWATER has sharpened your focus, do not stop here. Broaden your watchlist, compare quality, and pressure test your thesis using fresh sets of data driven ideas.
- Target quality at a discount by scanning companies that pass strict fundamental checks and trade below intrinsic value using the 16 high quality undervalued stocks.
- Lock in income ideas by reviewing businesses with robust payouts and yields above 5% inside the 29 dividend fortresses.
- Prioritise resilience by focusing on businesses with cleaner balance sheets and healthier fundamentals with the list of solid balance sheet and fundamentals (21 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com