


DuPont De Nemours (DD) Launches AmberChrom SIL, Is It Still Below Fair Value?
DuPont de Nemours (DD) has introduced AmberChrom SIL silica gel, a reverse phase silica media designed to refine peptide purification for therapies such as GLP-1 receptor agonists used in chronic disease treatment.
The new AmberChrom SIL launch comes after a solid period for DuPont de Nemours, with the share price at US$140.05 and a 30-day share price return of 7.75%, adding to a 14.22% year-to-date share price gain. The 1-year total shareholder return of 39.10% and 3-year total shareholder return of 69.78% indicate momentum that long-term holders have already experienced.
Spot opportunities around DuPont de Nemours by scanning a hand picked 19 high quality undiscovered gems that share strong fundamentals yet remain off most investors' radar.After a sharp run that has already rewarded DuPont de Nemours holders, anyone watching from the sidelines faces a simple fork in the road. Is the recent price strength already baking in the AmberChrom story, or does the valuation still leave meaningful room to move?
Most Popular Narrative: 16% Undervalued
On the most followed view of DuPont de Nemours, a fair value of $166.41 sits well above the recent $140.05 close. This places the AmberChrom launch within a broader story about a focused industrial portfolio, rising margins and disciplined capital use.
DuPont de Nemours is reshaping its portfolio around Healthcare & Water Technologies and Diversified Industrials, supported by the recent Aramids divestiture and GICS shift to Industrials. This concentrates capital and management attention on businesses that management expects to support revenue growth and operating EBITDA margins over time.
See why 32 investors see DuPont de Nemours as 16% undervalued.
Result: Fair Value of $166.41 (UNDERVALUED)
Still, the DuPont de Nemours story can change quickly if PFAS related liabilities expand or if slower Water project activity limits profitability.
Find out about the key risks to this DuPont de Nemours narrative.
Another View: DuPont de Nemours Through The P/E Lens
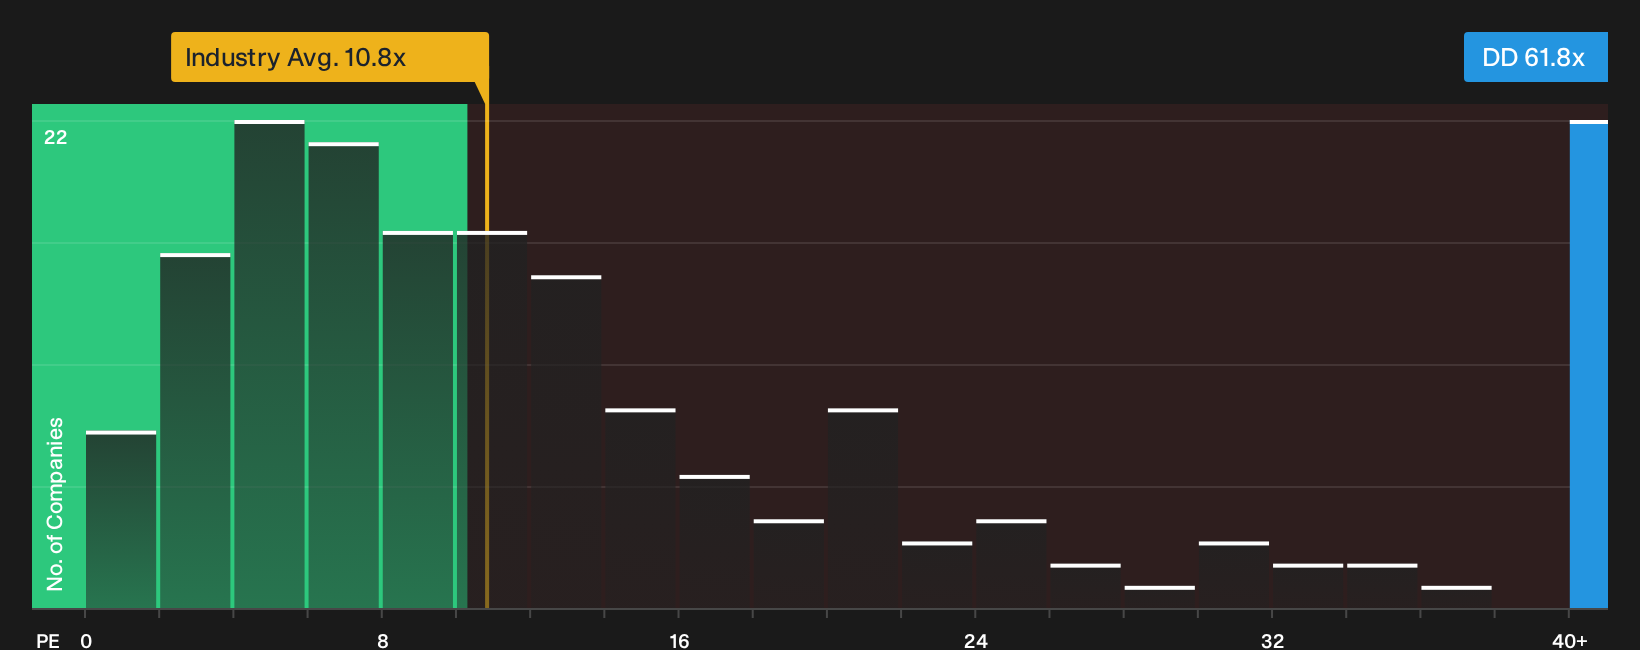
DuPont de Nemours looks very different once the share price is compared with earnings rather than cash flows. The stock trades on a P/E of 61.8x, while the global Industrials group sits at 10.8x and closer peers average 27.4x. The Simply Wall St fair ratio is 28.2x, so the current multiple sits well above where the market could drift over time. Is that a premium you are comfortable paying if sentiment turns?
For a deeper look at how this pricing gap stacks up against fundamentals, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Curious whether the mixed tone on DuPont de Nemours reflects your own view or not? Move quickly, weigh both sides of the story, and pressure test your thesis against the 3 key rewards and 2 important warning signs.
Looking for more DuPont de Nemours sized opportunities?
If DuPont de Nemours has your attention, do not stop here. The next smart move is widening your opportunity set with a focused set of ideas.
- Target quality at a discount by scanning a 33 high quality undervalued stocks that already clear strict cash flow and balance sheet basics.
- Prioritise resilience first by working through a 29 resilient stocks with low risk scores that screens for sturdier fundamentals and fewer red flags.
- Sharpen your income focus by zeroing in on a 5 dividend fortresses built around higher yields and durable payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com