


Is AZZ (AZZ) Undervalued As Strong Quarterly Results Beat Expectations?
AZZ (AZZ) is back in focus after quarterly earnings and revenue topped expectations, a result that has helped draw fresh interest in the stock and its near term earnings outlook.
AZZ’s recent earnings surprise comes after a choppy stretch for the share price, with the stock down about 10% over 90 days but still up 22.5% year to date. The 1 year total shareholder return of 35.5% and 3 year total shareholder return of about 1.9x hint that longer term momentum has been much stronger than the latest pullback suggests.
Scan how AZZ compares with other infrastructure focused industrials by reviewing the hand picked 41 power grid technology and infrastructure stocks that are attracting attention after their own earnings surprises.
AZZ has already delivered strong multi year gains, yet the latest 90 day slide and fresh earnings surprise pull the focus back to a simple tension: Is the meaningful upside still ahead or already in the rearview mirror as valuation comes under the microscope next?
Most Popular AZZ Narrative: 18% Undervalued
AZZ last closed at $134.44, while the most widely followed narrative pegs fair value closer to $164. That gap rests on the idea that execution on capacity, acquisitions and digital tools can support the earnings path implied by that higher valuation.
The main requirement is continued disciplined execution on capacity expansions, acquisitions such as the recent Seattle Galvanizing purchase, and the ramp of Washington, Missouri so that margins and cash generation remain resilient through different end market conditions.
The deverticalization model, where AZZ acquires in house kettles and long term service agreements from manufacturers that want to outsource galvanizing, is being discussed with a defined target list of customers and is viewed internally as repeatable, which could create durable service revenue streams and support cash flow growth.
See why 5 investors see AZZ as 18% undervalued.
Result: Fair Value of $164.00 (UNDERVALUED)
Still, AZZ’s story can be knocked off course if winter weather again cuts production days or if cost inflation and tariffs squeeze margins faster than pricing can adjust.
Find out about the key risks to this AZZ narrative.
Another View On AZZ Valuation
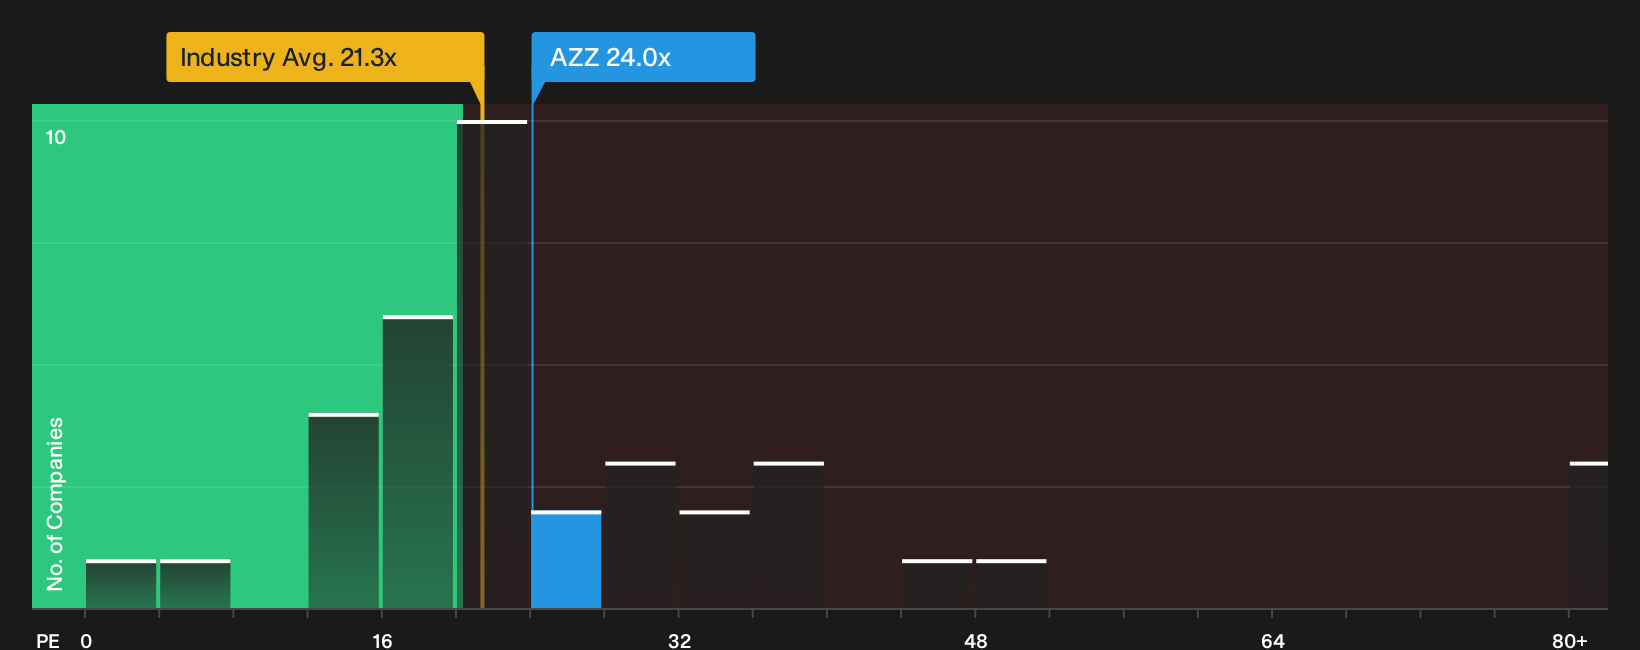
While the popular AZZ narrative leans on a fair value of $164, the market is currently asking investors to pay a P/E of 24x. That compares with 22.6x for peers, 21.3x for the wider US Building group, and a fair ratio of 19.4x that the market could move toward. Is that extra valuation a stretch you are paying, or a risk you are taking?
To see how those P/E gaps stack up against earnings quality and sector peers, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on AZZ valuation and fundamentals can create a lot of noise, so move quickly, review the numbers yourself, and then weigh the 3 key rewards and 2 important warning signs.
Looking for more AZZ investment ideas?
If AZZ has sharpened your focus on quality, do not stop here. Broaden your watchlist with fresh ideas that match how you like to invest.
- Target potential upside in quality leaders that the market may be overlooking by running your own search through the 19 high quality undiscovered gems.
- Prioritize resilience and focus on stability and downside protection by checking companies on the 29 resilient stocks with low risk scores.
- Explore income-focused opportunities by scanning the 5 dividend fortresses for higher yields supported by business fundamentals you can justify.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com