


Undiscovered Gems in Asia for November 2026
As the Asian markets navigate a landscape marked by mixed performances in global indices and persistent inflation pressures, small-cap stocks have shown resilience, particularly in value-oriented sectors. With this backdrop, identifying potential investment opportunities requires a keen eye for companies demonstrating strong fundamentals and adaptability to evolving economic conditions.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Shengyi Electronics | 28.87% | 29.30% | 56.37% | ★★★★★☆ |
| Shandong Head GroupLtd | 48.27% | 6.77% | -13.52% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Jade Bird Fire | 44.49% | 2.84% | -14.10% | ★★★★★☆ |
| Befar Group | 63.37% | 14.26% | -42.93% | ★★★★☆☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Primo Global Holdings | 64.63% | 9.93% | 28.27% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Below we spotlight a couple of our favorites from our exclusive screener.
Beijing Chunlizhengda Medical Instruments (SEHK:1858)
Simply Wall St Value Rating: ★★★★★★
Overview: Beijing Chunlizhengda Medical Instruments Co., Ltd. operates in the research, development, production, and sale of surgical implants and instruments both in China and internationally, with a market cap of approximately HK$4.99 billion.
Operations: Chunlizhengda generates revenue primarily from the sale of surgical implants and instruments. The company's financial performance is influenced by its gross profit margin, which stands at 75.32%.
Beijing Chunlizhengda Medical Instruments, a smaller player in the medical equipment sector, is trading at 42% below its estimated fair value. Despite a modest earnings growth of 5.6% over the past year, which lags behind the industry average of 14.5%, it remains profitable with positive free cash flow and more cash than total debt. The company reported sales of CNY 626 million for nine months ending September 2026, down from CNY 756 million last year, while net income slightly dipped to CNY 189 million from CNY 192 million. With high-quality earnings and plans for future growth at an annual rate of roughly 20%, Chunlizhengda presents an intriguing prospect in the market landscape despite recent challenges like executive changes impacting compliance requirements.

Warom Technology (SHSE:603855)
Simply Wall St Value Rating: ★★★★★☆
Overview: Warom Technology Incorporated Company specializes in the research, development, manufacturing, and supply of explosion-proof electric apparatus and professional lighting equipment both in China and internationally, with a market cap of CN¥6.07 billion.
Operations: Warom Technology generates revenue primarily through the sale of explosion-proof electric apparatus and professional lighting equipment. The company's financial performance is highlighted by a market cap of CN¥6.07 billion, indicating its significant presence in the industry.
Warom Technology, a nimble player in the electrical sector, has shown resilience despite recent challenges. The company's net income for the first nine months of 2026 rose to CNY 313.12 million from CNY 299.53 million last year, with earnings per share climbing to CNY 0.94 from CNY 0.88. Although sales dipped slightly to CNY 2,217.28 million from CNY 2,314.14 million year-on-year, Warom's financial health remains robust with interest payments comfortably covered by EBIT at a staggering ratio of over 757 times and more cash than total debt on hand—indicating strong fiscal discipline and potential for future growth amidst industry headwinds.
- Get an in-depth perspective on Warom Technology's performance by reading our health report here.
Evaluate Warom Technology's historical performance by accessing our past performance report.

Zhejiang Asia-Pacific Mechanical & ElectronicLtd (SZSE:002284)
Simply Wall St Value Rating: ★★★★★★
Overview: Zhejiang Asia-Pacific Mechanical & Electronic Co., Ltd focuses on the development, production, and sale of automotive parts and accessories both in China and internationally, with a market cap of CN¥6.64 billion.
Operations: The company generates revenue primarily from the production and sale of automotive components, amounting to CN¥5.77 billion. The focus on this segment is crucial for its financial performance.
Zhejiang Asia-Pacific Mechanical & Electronic, a notable player in the auto components industry, showcases impressive growth with earnings surging by 54% over the past year, significantly outpacing the industry's -7.4%. The company reported CNY 4.14 billion in sales for nine months ending September 2026, up from CNY 3.97 billion last year. Net income reached CNY 430 million compared to CNY 328 million previously, reflecting robust financial health and high-quality earnings. With a debt-to-equity ratio reduced from 58.4% to 35.4% over five years and trading at a substantial discount of about 59%, it presents compelling value prospects for investors seeking under-the-radar opportunities in Asia's dynamic markets.
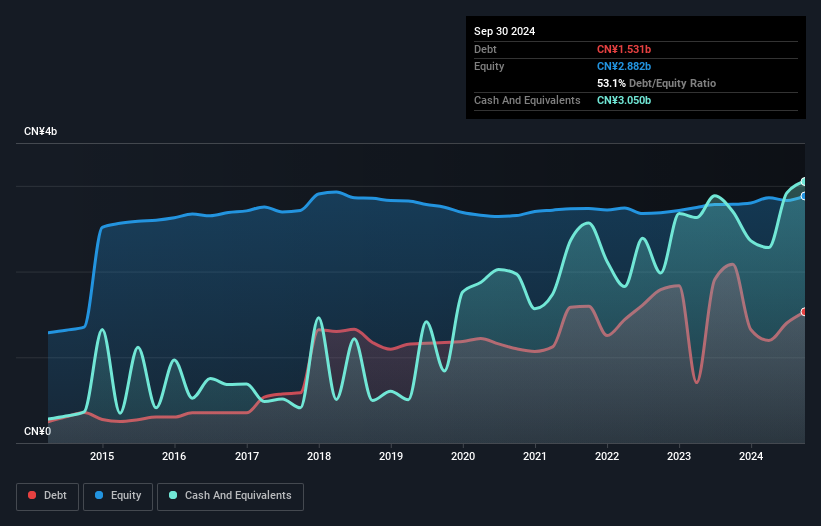
Make It Happen
- Click here to access our complete index of 147 Asian Undiscovered Gems With Strong Fundamentals.
- Already own these companies? Bring clarity to your investment decisions by linking up your portfolio with Simply Wall St, where you can monitor all the vital signs of your stocks effortlessly.
- Unlock the power of informed investing with Simply Wall St, your free guide to navigating stock markets worldwide.
Searching for a Fresh Perspective?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com