


Pinnacle Financial Partners (PNFP) Beat Expectations, Is The Stock Still A Bargain?
Earnings surprise draws attention to Pinnacle Financial Partners stock
Pinnacle Financial Partners (PNFP) moved into focus after third quarter results showed net interest income of US$986 million and net income of US$379 million, both higher than the same period a year earlier.
Pinnacle Financial Partners shares have edged up over the past week and month, with a 7-day share price return of 1.31% and 30-day gain of 5.80%. The 1-year total shareholder return of 21.42% and 3-year total shareholder return of 52.95% point to momentum that has built over time as recent earnings and dividend affirmations reset expectations around growth prospects and perceived risk.
Scan how Pinnacle Financial Partners compares with other banks showing improved earnings momentum and dividend support by reviewing the curated list of solid balance sheet and fundamentals (24 results)
The recent climb in Pinnacle Financial Partners appears closely tied to stronger reported earnings, rather than simply a change in sentiment around the stock. The key question is how far that business performance goes in justifying the current valuation.
Most Popular Narrative: 16% Undervalued
Pinnacle Financial Partners is priced at $101.66 against a widely followed fair value estimate of $120.32. This puts the spotlight on what needs to go right in the underlying business for that gap to make sense.
The main thing that has to go right is successful integration of the Synovus merger while preserving Pinnacle Financial Partners’ high-touch culture, maintaining strong credit quality, and delivering the full revenue synergy and productivity benefits of its specialty platforms and technology investments.
See why 25 investors see Pinnacle Financial Partners as 16% undervalued.
Result: Fair Value of $120.32 (UNDERVALUED)
Still, if higher long term funding costs persist or the Synovus integration drags beyond current timelines, the upbeat Pinnacle Financial Partners narrative could weaken quickly.
Find out about the key risks to this Pinnacle Financial Partners narrative.
Another view on Pinnacle Financial Partners valuation
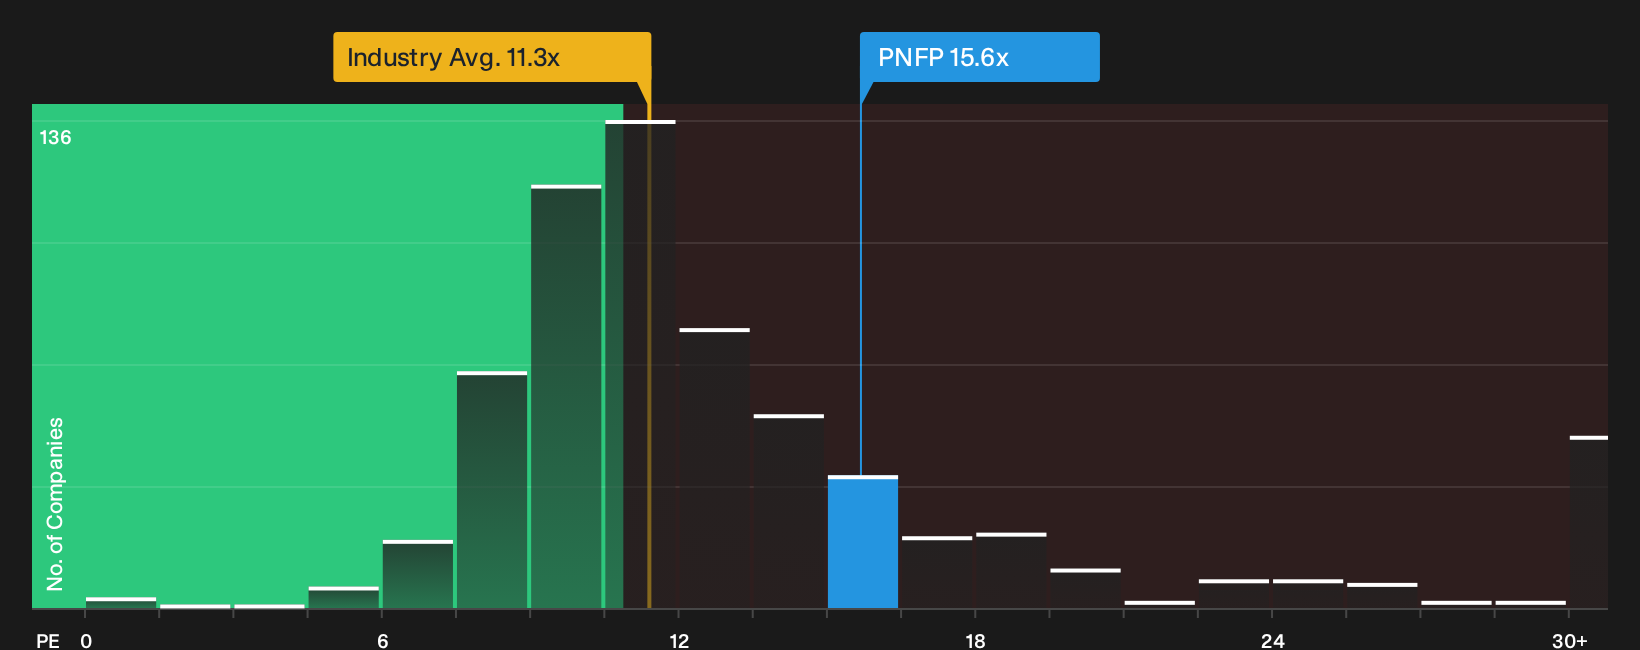
The earlier narrative leans on future earnings and a fair value of $120.32. Today Pinnacle Financial Partners trades on a P/E of 15.6x against an industry average of 11.4x and a fair ratio of 18.1x. That mix of premium to peers but discount to the fair ratio raises a simple question: Is this a quality premium that persists, or a pricing gap that can close in either direction?
To pressure test those questions against hard numbers, it helps to see what the valuation ratios are implying about risk and return for Pinnacle Financial Partners relative to similar banks, and where the fair ratio suggests the market could eventually settle, See what the numbers say about this price — find out in our valuation breakdown.
That context gets even clearer when you compare the current P/E for Pinnacle Financial Partners with the broader US Banks group visually through
Next Steps
Mixed signals so far, with Pinnacle Financial Partners showing both support and skepticism baked into recent numbers and sentiment, call for your own judgment. To weigh those cross currents quickly and form a clear view, go straight to the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Pinnacle Financial Partners?
If Pinnacle Financial Partners has sharpened your focus on quality and price, do not stop here. Widen your search and pressure test fresh opportunities.
- Target resilient compounding potential by scanning a curated set of 33 high quality undervalued stocks that pair quality fundamentals with prices that may not fully reflect them.
- Build a cash flow focused watchlist by reviewing a hand picked group of 5 dividend fortresses designed for investors who care about consistency as much as yield level.
- Prioritise sleep at night potential by screening for 29 resilient stocks with low risk scores that combine sturdier balance sheets with tighter risk profiles than the broader market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com