


Saia (SAIA) Could Be 18% Undervalued On Record Q3 Earnings And $250 Million Buyback
Saia (SAIA) just packed several events into one day, reporting record third quarter earnings, unveiling a new US$250 million share repurchase program and adding industry veteran Todd C. Fowler to its board.
Saia’s recent record quarter and fresh US$250 million buyback sit against a mixed price backdrop, with a 17.83% one year total shareholder return contrasting with a slightly weaker 3 month share price return. This suggests that earlier momentum has cooled, even as management signals confidence through capital returns and a refreshed board.
Compare Saia's record quarter and fresh buyback with other potential opportunities by scanning our hand picked 33 high quality undervalued stocks.
Bulls point to Saia’s record quarter, fresh buyback and new board expertise, while bears focus on a rich earnings multiple and cooling momentum. Which side do the valuation numbers lean toward next?
Most Popular Narrative: 18% Undervalued
Saia’s most followed valuation storyline pins fair value around $420 per share, which sits above the latest close of $344.66 and frames the new buyback against a stock that narrative followers still see as discounted.
The ongoing expansion and maturation of Saia's national terminal network, combined with densification of the 218 plus facilities added or upgraded since 2022, is still early in its ramp and is beginning to show operating ratio improvement at newer sites. This could support higher shipment volumes, revenue growth and better net margins as more terminals move from the low 90s operating ratio toward mature system levels.
See why 4 investors see Saia as 18% undervalued.
Result: Fair Value of $420 (UNDERVALUED)
Still, the story breaks if Saia’s higher wage, fuel and insurance costs continue to outpace pricing, or if freight demand softens enough to dilute operating leverage.
Find out about the key risks to this Saia narrative.
Another View: Saia Through A Cash Flow Lens
The story shifts when you look at Saia through the SWS DCF model. From this perspective, the shares at $344.66 sit well above an estimated future cash flow value of $150.13, which screens as overvalued rather than discounted. If earnings execution stumbles, this higher cash flow-based valuation could start to matter more than the popular $420 fair value line.
Look into how the SWS DCF model arrives at its fair value.
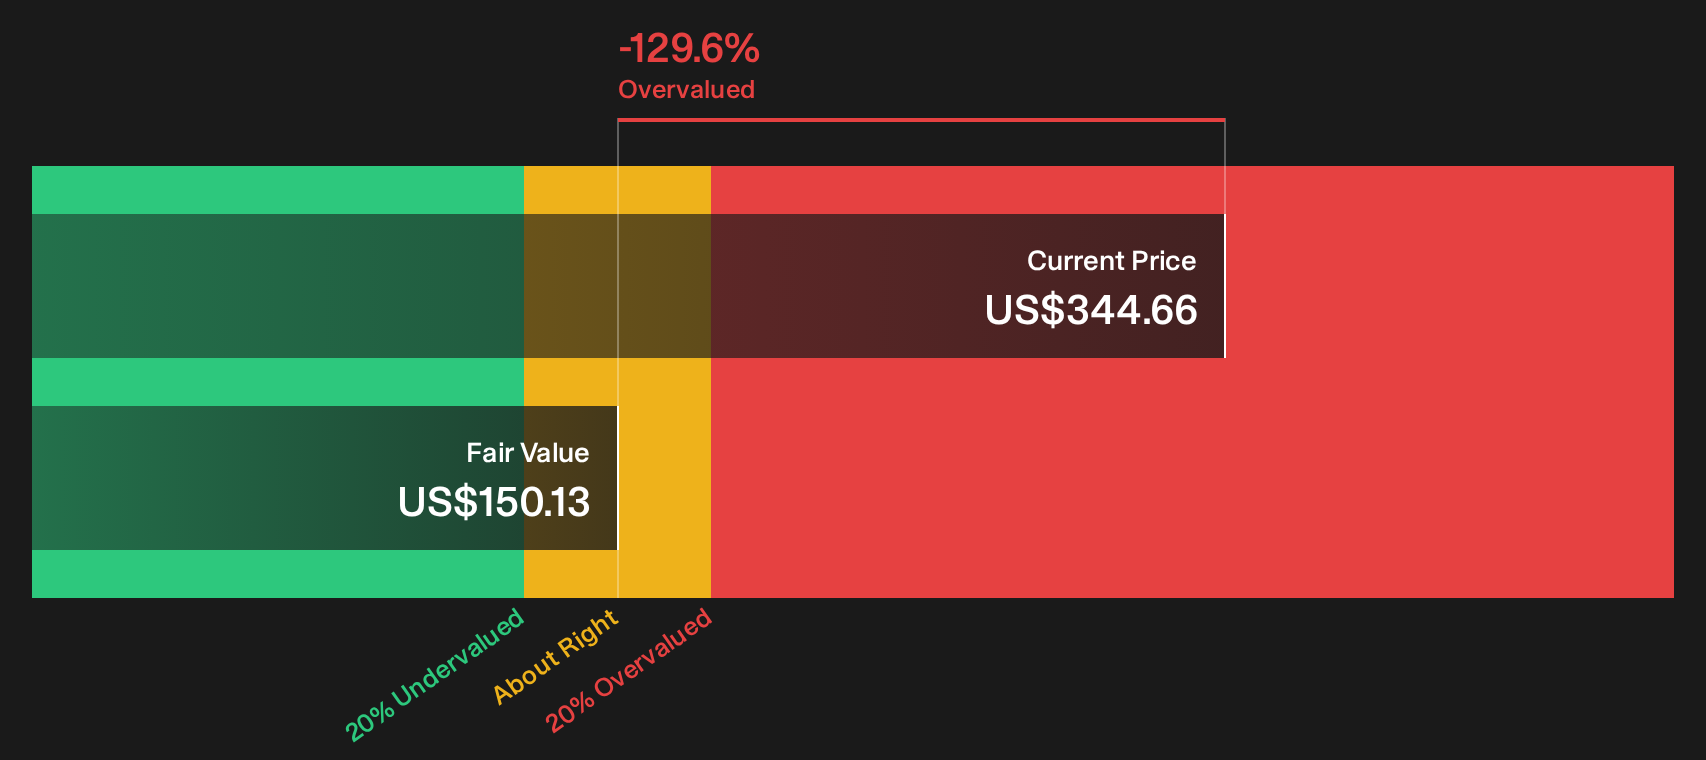
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Saia for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Saia can feel confusing, especially when strong narratives and cautionary flags sit side by side. Act quickly and stress test the upside case for yourself by reviewing the 2 key rewards.
Looking for more investment ideas beyond Saia?
Saia may be on your radar now, but your next strong idea could be sitting in plain sight if you widen the net across other well filtered opportunities.
- Target potential mispricings by scanning companies that screen as strong quality yet still trade on undemanding valuations through the 33 high quality undervalued stocks.
- Prioritize resilience and aim to sleep better at night by checking a list of solid balance sheet and fundamentals (24 results) that can handle shocks without stretching finances.
- Look for potential future market favorites early by reviewing a curated pool of 19 high quality undiscovered gems before attention and capital crowd in.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com