


Neogen (NEOG) ESOP Share Shelves Raise The Question Of Whether The Stock Is Fully Valued
Neogen (NEOG) has filed two shelf registrations for common stock tied to its employee stock ownership plan, covering up to 16,350,000 shares and approximately $190.2 million in potential equity issuance.
The recent ESOP related shelf registrations arrive after a softer patch in the chart, with the share price down 3.6% over the past day and 3.0% over the last week, yet still up 68.9% year to date and delivering a 91.6% total shareholder return over one year. That mix of short term weakness and strong recent gains suggests that investors are reassessing near term dilution risk while still pricing in a much better story than the 25.3% three year and 73.9% five year total shareholder return declines would imply.
Compare Neogen's ESOP driven volatility with other companies where balance sheet strength is front and center by scanning our curated list of solid balance sheet and fundamentals (24 results).
After that sharp year to date rebound and the fresh dilution overhang from the ESOP shelves, does Neogen still offer enough upside potential for the risk you are taking at today’s price?
Most Popular Narrative: 16% Undervalued
On the most followed narrative, Neogen screens as undervalued, with a fair value of $14 against the last close at $11.82. This puts the spotlight on whether the long term story can outweigh near term dilution concerns.
Operational improvements and automation at the new Petrifilm production facility, alongside targeted actions to reduce inefficiencies in sample collection and inventory management, are expected to drive gross margin and EBITDA margin improvements over the coming quarters as execution stabilizes and overhead absorption rates improve.
See why 5 investors see Neogen as 16% undervalued.
Result: Fair Value of $14 (UNDERVALUED)
Still, that narrative can unravel quickly if integration snags at the 3M Food Safety unit keep margins under pressure, or if Animal Safety weakness and tariff costs drag on cash generation.
Find out about the key risks to this Neogen narrative.
Another View: Neogen Looks Expensive On Sales
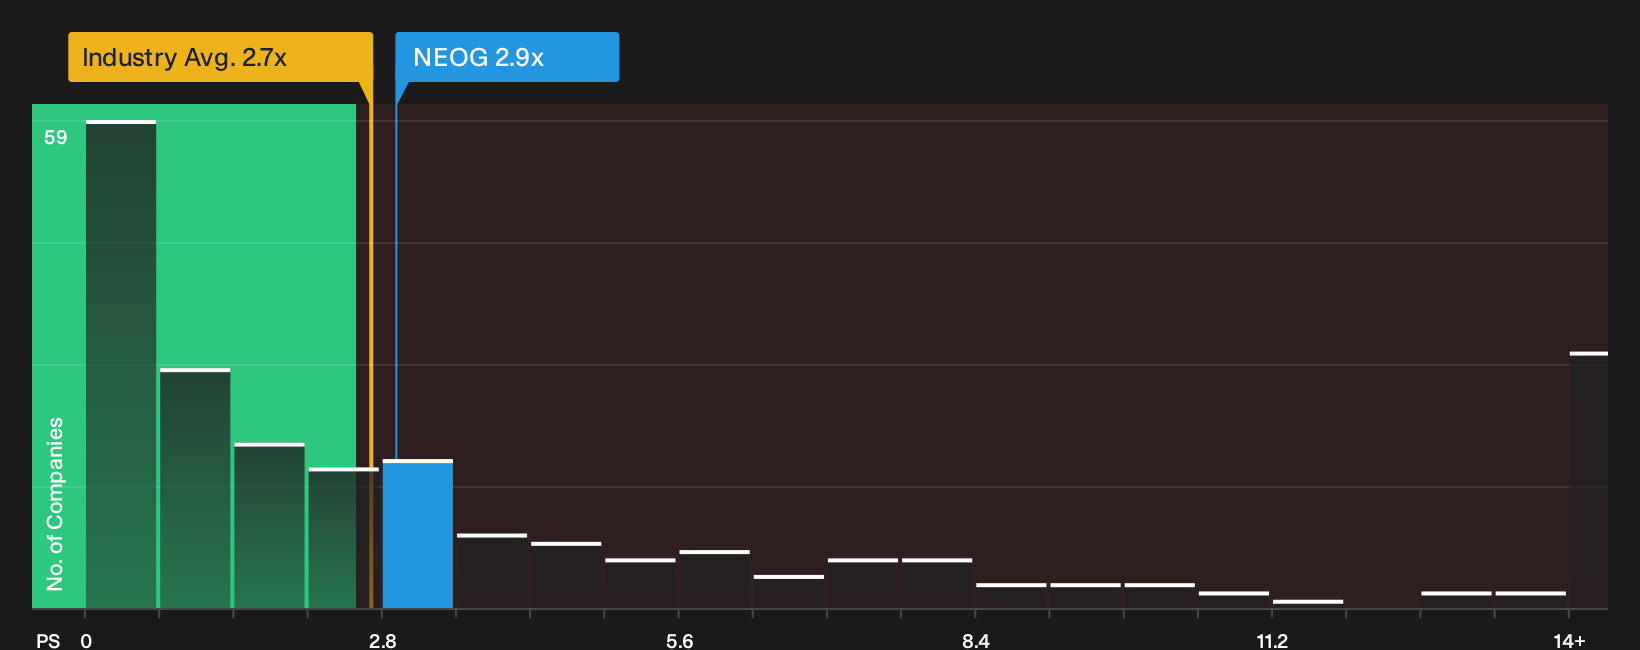
The popular Neogen narrative leans on a $14 fair value, yet the simple sales based yardstick tells a different story. The stock trades on a P/S of 2.9x, compared with 2.7x for the US Medical Equipment group and 1.9x for peers, while the fair ratio sits at just 1.1x. That wide gap points to meaningful valuation risk rather than a clear bargain. How comfortable are you paying a premium for a business that is still loss making?
For a closer look at how that pricing compares, including context on peers and the industry, check the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If that mix of optimism and valuation risk leaves you on the fence, move quickly to stress test Neogen against your own framework. Then weigh those findings against the 1 key reward
Looking for more Neogen sized investment ideas?
Do not stop your research with Neogen. Broaden your watchlist using focused stock shortlists that highlight different angles, risk levels, and income profiles across the market.
- Target potential mispricing and hunt for quality at a discount by running through our curated 33 high quality undervalued stocks.
- Strengthen your income stream and compare yield focused opportunities by reviewing the hand picked 5 dividend fortresses.
- Dial back portfolio shocks and concentrate on resilience by scanning the carefully filtered 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com