


Higher Rates Are Turning Cash Into a Profit Engine for Small US Bank Stocks
Higher-for-longer interest rates are quietly rewiring where cash flows in markets, turning once boring cash management and money-market services into potential profit centers. Investors who ignore where those dollars settle risk missing how this shift could reshape parts of the equity universe over the next few years. This article explains the backdrop in detail, then examines three stocks from our U.S. Short-Duration Cash & Money-Market Beneficiaries screener that appear well placed for this new cash-first world.
The stocks covered next are only a small sample of this theme, and the full screen surfaced 27 more U.S.-listed companies with cash-related storylines that match the same base filters but are not discussed here. To identify and analyze the highest conviction ideas for your watchlist, go straight to the US Short-Duration Cash & Money-Market Beneficiaries screener.
Forbright (FRBT)
Overview: Forbright is a U.S. bank holding company that collects consumer and business deposits, then lends and manages cash across specialized financing lines.
Market Cap: US$922 million
Forbright is closely tied to the higher-for-longer rate theme because its lending and cash products turn short-term deposits into yield on a national scale.
"Expansion of the proprietary digital deposit platform, including promotion tools and the upcoming digital checking product, is building a lower cost, granular funding base that can support asset growth and influence net interest margin and overall funding costs."
For investors, changes in a single key assumption about future funding costs and pricing power may be significant.
Those funding swings are exactly what the full narrative for Forbright unpacks, revealing how pricing power, deposit mix and growth ambitions could be quietly accelerating beneath the surface.

National Bank Holdings (NBHC)
Overview: National Bank Holdings runs a regional U.S. bank that provides deposits, lending, and cash-management services to commercial, business, and retail clients.
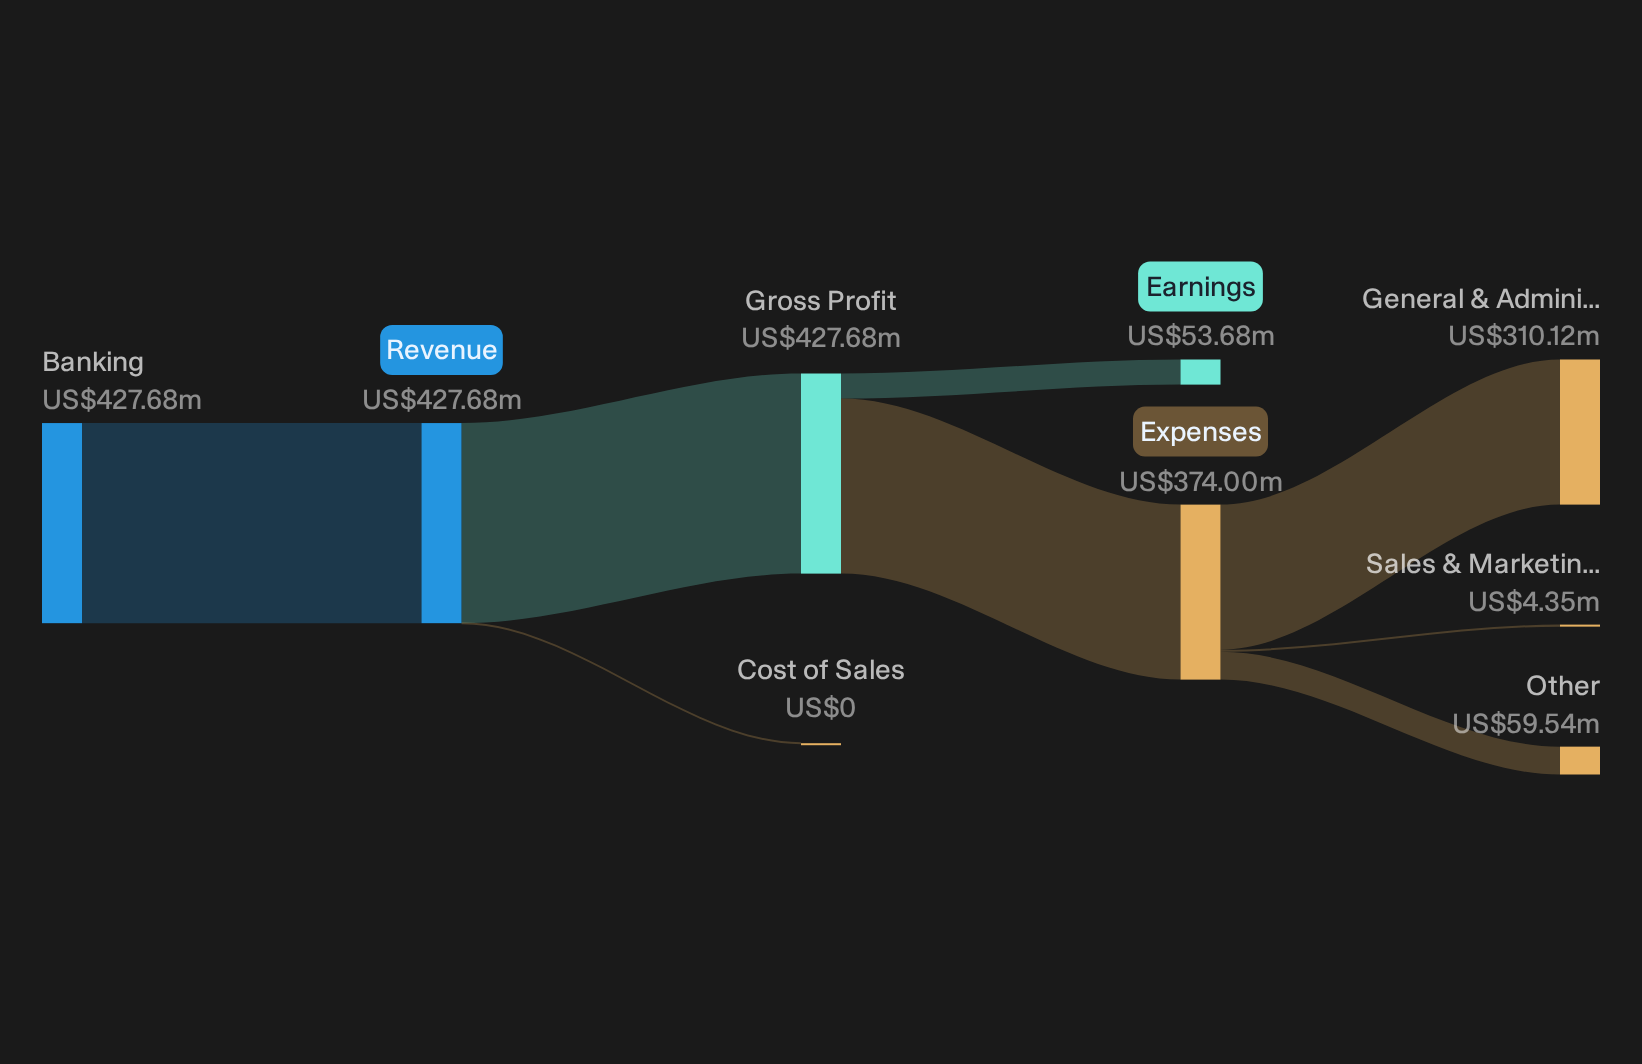
Operations: National Bank Holdings generates about US$428 million of revenue from banking activities across the United States, its sole reported market.
Market Cap: US$1.66 billion
For the higher-for-longer rates theme, National Bank Holdings matters because its treasury and cash-management franchise turns operating deposits into interest income and fee revenue for business customers that want their idle balances working harder.
"The 2UniFi small business platform is still in the investment phase, with expenses of about US$20 million to US$22 million in 2026 and guided revenue of US$2 million to US$4 million. Any improvement in credit conversion or monetisation could lift National Bank Holdings noninterest income and narrow the drag on earnings."
This raises a key question: what happens to National Bank Holdings margins if a relatively quiet shift in how small firms use those cash and credit tools goes differently than expected?
If that shift in small business behavior has your attention, go straight to the full narrative for National Bank Holdings to see how those cash flows could be quietly accelerating.
Live Oak Bancshares (LOB)
Overview: Live Oak Bancshares is a U.S. bank holding company focused on small business lending and deposits, including money market and cash management services.
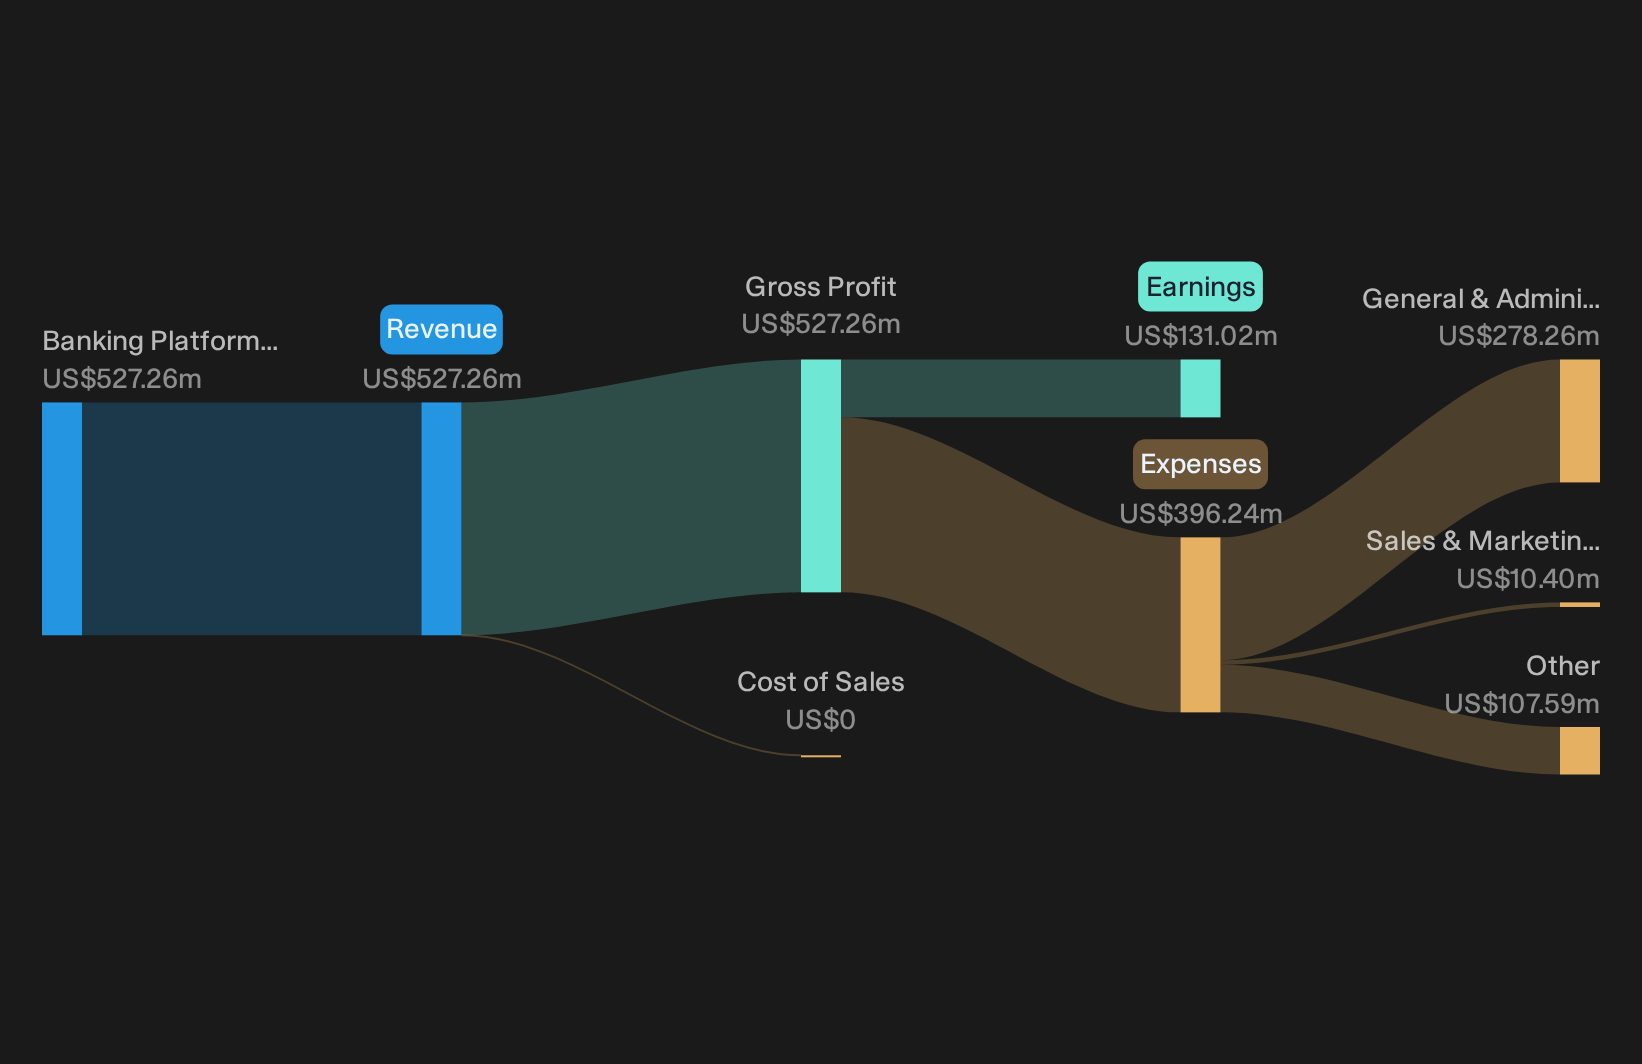
Operations: Live Oak Bancshares generates about US$527 million of revenue from its small business banking platform, entirely within the United States.
Market Cap: US$1.60 billion
Live Oak Bancshares fits the higher-for-longer cash theme because it leans into business deposits and short-duration lending where rate-sensitive cash balances really matter.
"The rapid scaling of Live Oak Express and newer business checking offerings from essentially zero in 2023 to record small-dollar 7(a) production of US$82 million in Q2 2026 and US$744 million of checking and other DDA balances is widening Live Oak Bancshares’ reach with digitally oriented small businesses and can support further revenue growth and a lower funding cost over time."
What happens to Live Oak Bancshares margins from here depends heavily on how one still-evolving piece of its small business engine behaves.
That still evolving engine is exactly what the full narrative for Live Oak Bancshares breaks down in full, highlighting where Live Oak Bancshares could be quietly accelerating and where cash economics might be masking risk.
Seeking Fresh Alternatives Before They Fly
Markets move fast and the next breakout list rarely stays quiet for long. Identify fresh momentum pockets while it matters, under the radar for now, and consider acting early if they fit your strategy.
- Focus on resilient cash generators with steady-looking balance sheets and use the list of solid balance sheet and fundamentals (24 results) to surface companies that keep funding strength front and center.
- Explore potential compounding income streams by scanning 5 dividend fortresses that aim to keep yields elevated even when prices are choppy or sentiment weakens.
- Monitor early leaders in automation by reviewing 95 robotics and automation stocks that may stand to benefit as capital targets efficiency gains and productivity improvements before they are widely recognized.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com