


Netflix (NFLX) Dismisses Film Chief Dan Lin
- Netflix (NasdaqGS:NFLX) has dismissed film chief Dan Lin as part of a continuing overhaul of its content leadership structure.
- The reshuffle follows the recent exit of chief content officer Bela Bajaria and layoffs that affect about 1,000 employees across the group.
- Management is reassessing the film division and broader content approach at a time of heightened focus on user engagement and capital allocation.
- The leadership shake up around Dan Lin and Bela Bajaria should matter, but it is only part of the Netflix investment story. We have also flagged 4 other big wins for Netflix.
Streaming is in flux and the changing content playbook at Netflix makes it worth comparing with the broader build out of digital infrastructure through 54 AI infrastructure stocks.
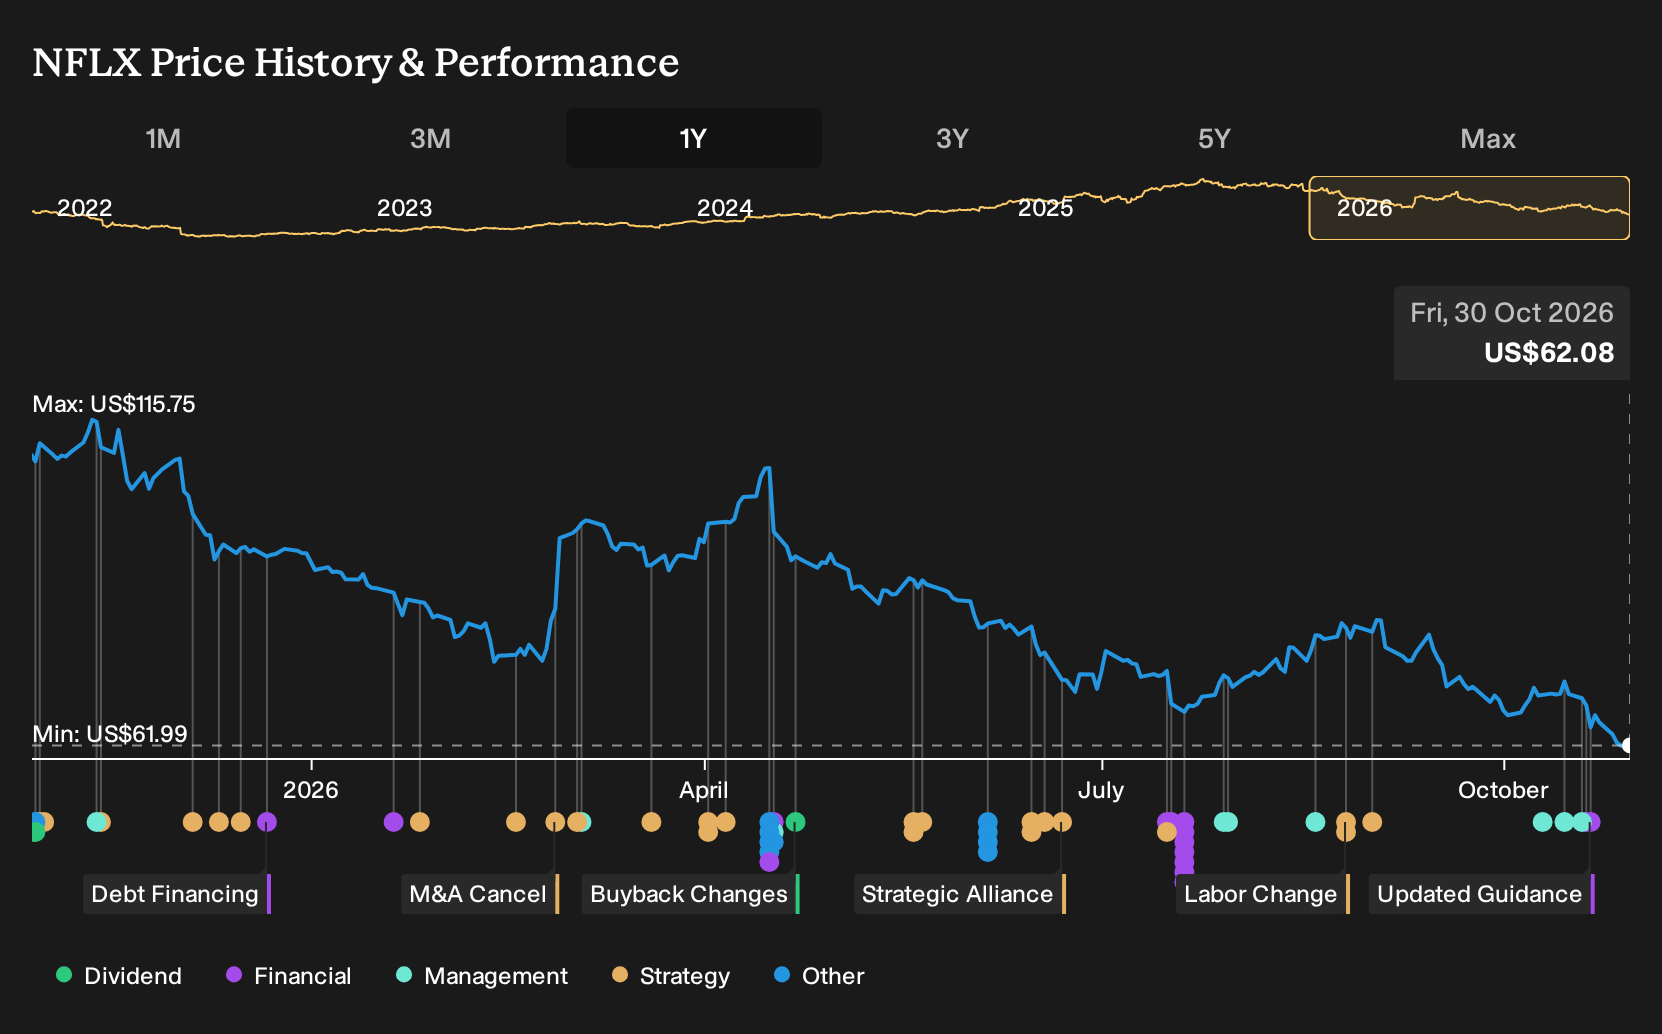
Netflix runs a global entertainment platform that depends heavily on a steady slate of films and series, so disruption in its content leadership affects how a US$254.8b streaming giant decides what shows up on screen and where those production dollars go.
Why does Dan Lin’s departure matter if Netflix just reported strong earnings?
Netflix reported Q3 2026 sales of about US$12.9b and net income of roughly US$3.7b, and it guided to Q4 revenue of US$13.4b with a 26% operating margin. Removing the film chief after that kind of financial update suggests the board is not satisfied with how content decisions line up with engagement trends and long term cash generation.
Does this leadership change shift the Netflix Narrative investors have been using?
The Narrative centers on Netflix using ads, live events and AI supported production to keep engagement high enough to support a targeted 31.5% operating margin in 2026. Replacing content leaders and cutting around 6% of roles fits directly into that story, since it tests whether cost discipline and a refreshed slate can address reported declines in viewing hours.
See how these catalysts shape Netflix's path to a $86.24 fair value.
What is the clearest early sign this reset is working for Netflix?
The clearest early indication will be whether engagement and revenue guidance start to align. Watch how reported viewing time, ad revenue guidance of about US$2.7b for 2026, and that 31.5% margin target evolve in the next few quarterly updates. Any sustained gap among those figures would suggest this leadership overhaul is not yet delivering.
Add Netflix to your Watchlist and get alerts as these catalysts play out.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com