


Raised 2026 Outlook Might Change The Case For Investing In Capgemini (ENXTPA:CAP)
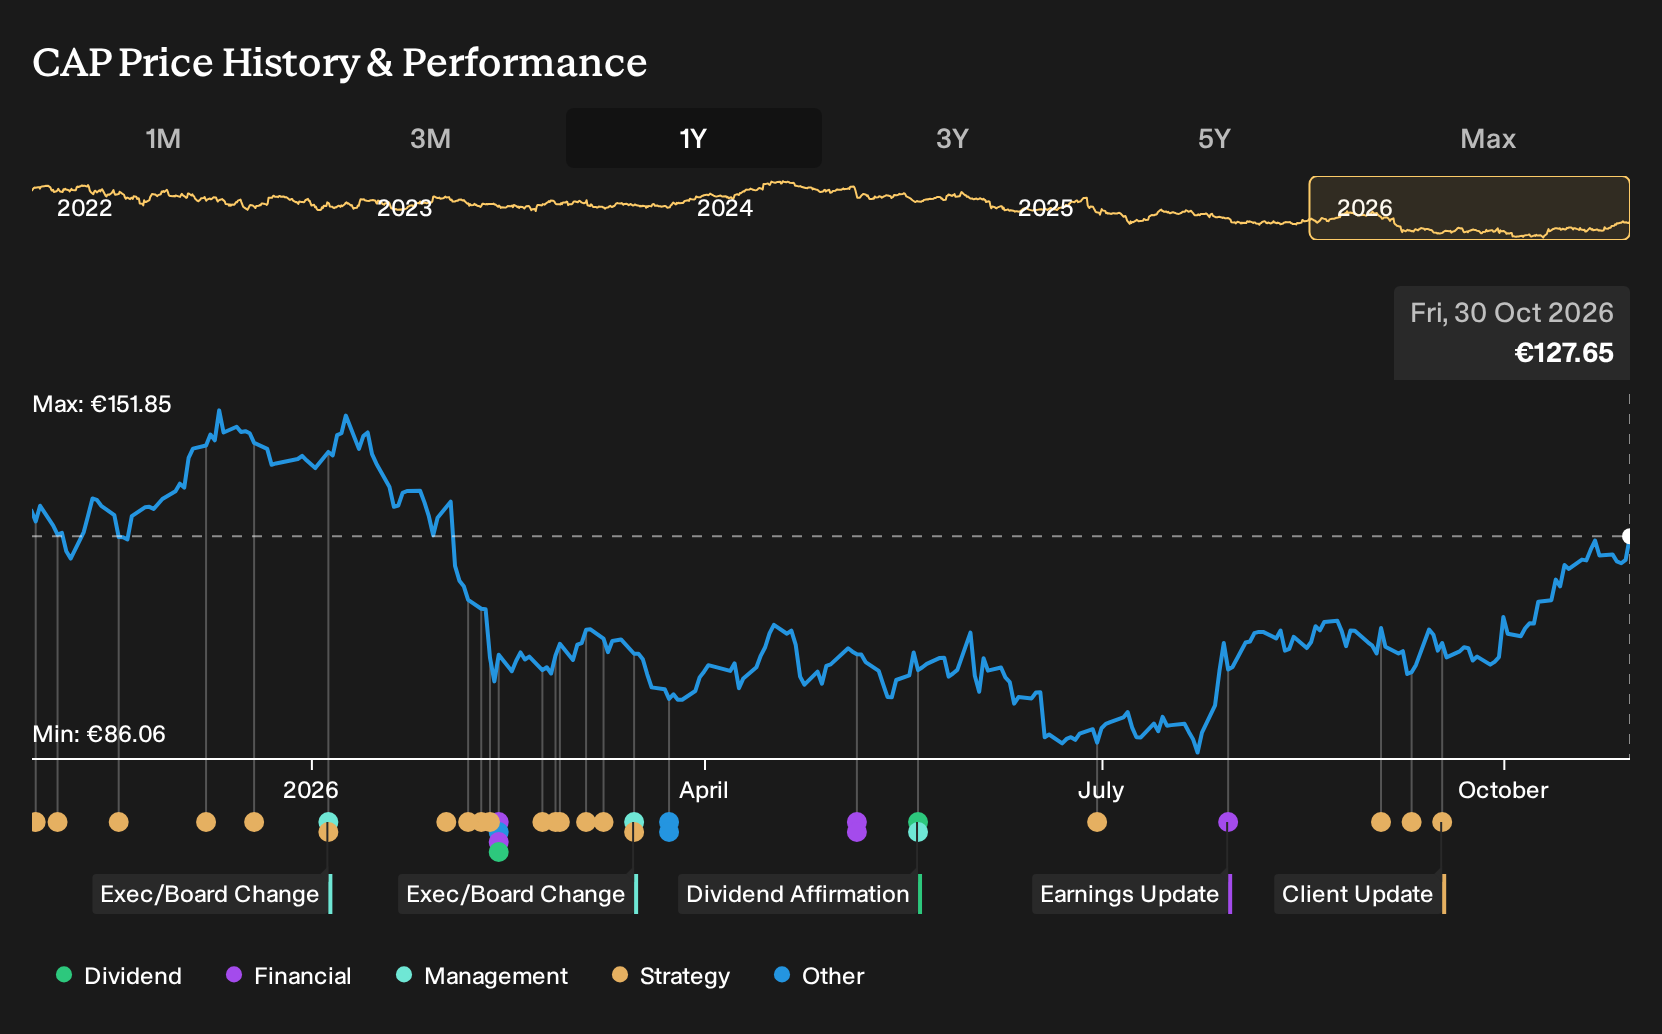
- Capgemini reported third quarter 2026 revenue of €6.07b at constant currency, supported by recent acquisitions, and raised its 2026 revenue growth target to 9.0% to 9.5% while keeping margin and cash flow goals unchanged.
- The group linked its upgraded outlook to strong demand for AI driven modernization, including an enterprise scale AI platform for a global asset and wealth manager that targets sizeable productivity gains and regulatory efficiencies.
- This article examines how Capgemini's investment narrative is affected by the higher 2026 revenue growth target linked to AI transformation demand.
Scan beyond Capgemini and spot other potential beneficiaries of the AI build out with our curated list of 54 AI infrastructure stocks.
Capgemini Investment Narrative Recap
To own Capgemini you need to believe that its shift toward AI, cloud and higher value services can offset heavier restructuring, higher debt and patchy country performance. The upgraded 2026 revenue growth target and solid Q3 bookings help the near term case that client demand is there. The key near term catalyst is execution on large AI and intelligent operations deals converting into cleaner earnings.
The biggest risk right now is that Fit for Growth and recent acquisitions drag on reported profit longer than expected, especially with €6.5b of net debt and higher interest costs already visible. Limited momentum in France and softer core applications growth also mean that any slowdown in AI transformation spending would quickly pressure the story.
Among recent announcements, the AI platform for the global asset and wealth manager is closest to the heart of the Capgemini narrative around enterprise scale AI. The project aims to cut manual governance workloads by 50% to 70% and accelerate workflows by 30% to 50%, with about US$20m of projected savings over three years for that client.
This kind of deal matters because it shows AI demand tied directly to cost, compliance and speed, which are the same themes behind the WNS based Intelligent Business Operations push. If Capgemini can replicate similar platforms across regulated financial services and then into other sectors, that would strengthen the case for its AI pipeline while also raising execution risk if delivery or outcomes disappoint.
Capgemini Consensus Growth and Valuation Setup
Capgemini's narrative projects €27.0b revenue and €2.1b earnings by 2029. This assumes 4.8% yearly revenue growth and an earnings increase of about €0.7b from €1.4b today.
Discover how Capgemini's fair value indicates a 10% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One bearish twist on the Capgemini story is the fear that AI projects eventually compress pricing instead of supporting richer contracts. The most cautious analysts were only pencilling in revenue of about €25.9b and earnings of roughly €2.0b by 2029 before this Q3 update. Their view is much more restrained. Use that gap as a prompt to compare several narratives and decide which assumptions feel realistic to you.
Explore 3 other Capgemini fair value estimates, including one that suggests as much as 13% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view.
- A great starting point for your Capgemini research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Capgemini. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Capgemini's overall financial health at a glance.
Looking For More Investment Ideas Beyond Capgemini?
Once you have a view on Capgemini, it often helps to widen the lens and line it up against other opportunities that share similar qualities or offer a very different risk profile. The Simply Wall St Screener can help you source a few focused shortlists instead of scrolling through hundreds of tickers.
- If capital preservation and a steadier ride matter most to you, start with a basket of 218 resilient stocks with low risk scores that score well on resilience and risk controls.
- For readers hunting for mispriced quality, scan through a curated set of 204 high quality undervalued stocks that combine solid fundamentals with more appealing valuations.
- If balance sheet strength is non negotiable in your process, shortlist companies from a list of solid balance sheet and fundamentals (199 results) to focus on businesses with robust financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com