


Macerich (MAC) Leans Into Destination Dining On An Undervalued Narrative
Macerich (MAC) just put restaurant leasing at the center of its story, rolling out first to market dining concepts and high profile food brands across Class A malls in several major U.S. markets.
Macerich’s latest push into destination dining comes after a mixed stretch on the market, with the share price up 31.43% year to date but down 5.91% over the past 90 days, while total shareholder return over three years is 144.26%.
Scan other retail REITs building experience led destinations by reviewing our curated list of 19 high quality undiscovered gems alongside Macerich’s restaurant heavy mall transformation story.
After a 31% year to date climb and a 6% pullback over 90 days, Macerich now trades between a discounted intrinsic estimate and a more modest analyst target. Which reference point best reflects fair value?
Most Popular Narrative: 8% Undervalued
Macerich’s most followed valuation story pegs fair value close to the current price, with a modest discount to the $24.34 last close that hinges on how well its mall transformation converts into earnings over time.
The focus on experiential and destination-oriented retail is now reinforced by all 30 previously vacant anchor boxes being committed to tenants such as Dick’s House of Sport, Dave & Buster’s and Level99. Management expects this to drive around US$750 million of tenant sales and to support percentage rent and operating margins as traffic lifts across surrounding inline shops.
See why 1 investors see Macerich as 8% undervalued.
Result: Fair Value of $26.56 (UNDERVALUED)
Still, the Macerich narrative could weaken if high leverage and refinancing pressures persist or if experiential tenants do not sufficiently offset pressure on more traditional retailers.
Find out about the key risks to this Macerich narrative.
Another View: Macerich Looks Expensive On Sales
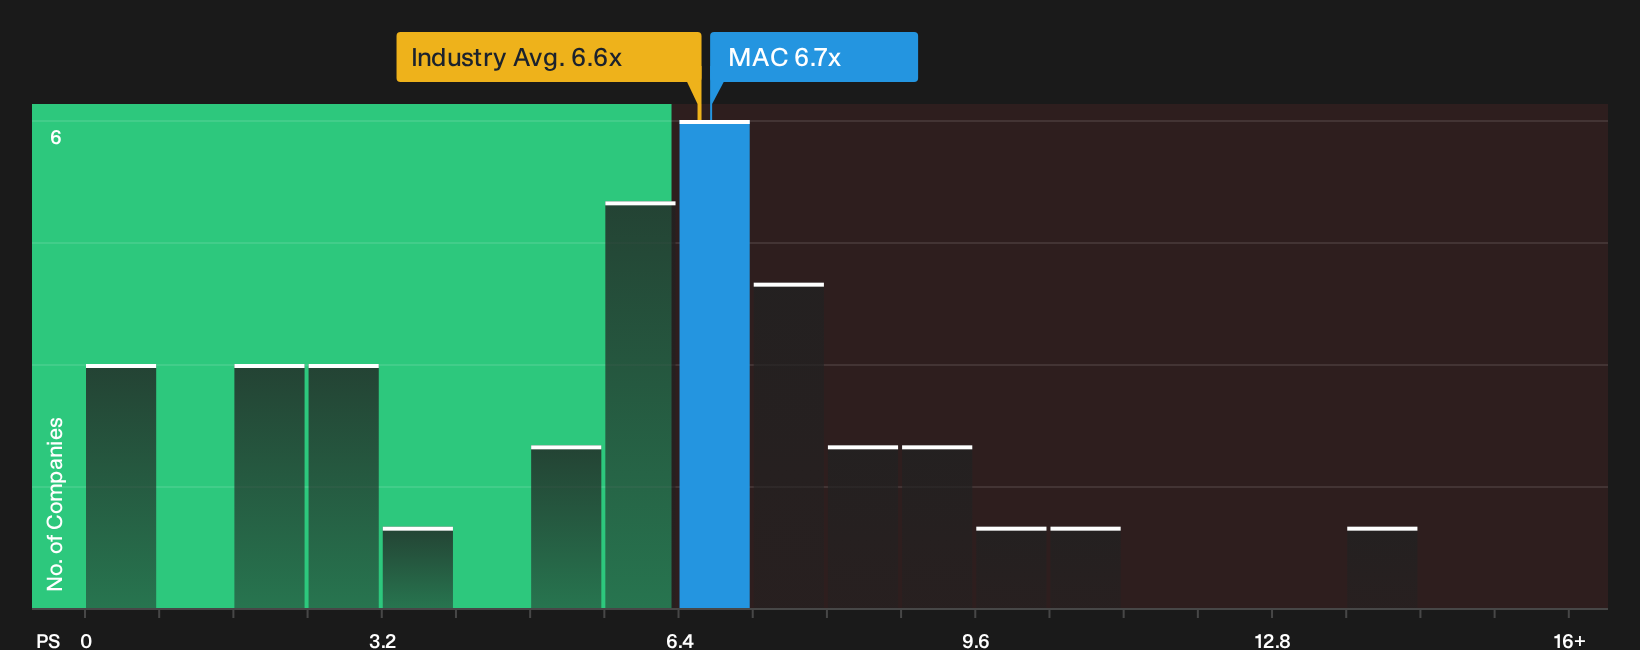
On a simple sales based lens, Macerich screens less generous. The stock trades on a P/S of 6.7x, slightly above the US Retail REITs average of 6.6x, and well above an estimated fair ratio of 4.2x. That gap points to less room for error on future performance. Where does that leave investors who want a margin of safety?
For a closer look at how the numbers line up against this sales based view, including where the market could shift toward that fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Macerich so far, or a balanced setup that needs your own judgment. Weigh the upside against the concerns and run your own checks with 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Macerich?
If Macerich has your attention, do not stop there. Use the same structured lens across other opportunities and give yourself more than one way to win.
Put surplus cash to work in compact opportunities by scanning 8 elite penny stocks with strong financials that already back their stories with solid financials and cleaner balance sheets.
Stack the odds toward value by reviewing 33 high quality undervalued stocks that combine quality fundamentals with pricing that still leaves room for upside if the thesis plays out.
Prioritise resilience in choppy conditions and review 29 resilient stocks with low risk scores so you are not relying on a single high beta idea to carry your portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com