


Cipher Digital (CIFR) Faces A Valuation Test After Its $850 Million Notes Offering
Cipher Digital (CIFR) hit investors with an $850 million zero coupon convertible notes announcement, shifting the focus squarely onto its rising debt load and the looming third quarter earnings update on November 2.
Cipher Digital’s share price has fallen 10.0% in the last session and is down 53.6% over 30 days and 69.8% over 90 days, while the 1 year total shareholder return is down 60.9% but the 3 year total shareholder return remains positive at 77.8%. This indicates that momentum has clearly faded following an earlier strong run.
Stress test your portfolio against this kind of high-debt, high-capex story by scanning our hand picked 29 resilient stocks with low risk scores that prioritize balance sheet strength over aggressive leverage.
The question now is whether Cipher Digital’s steep slide reflects cracks in the underlying business or a sharp reset in sentiment. To frame that properly, it helps to pin down what the current valuation implies.
Most Popular Narrative: 75.2% Undervalued
Against a last close of $7.29, the most followed narrative for Cipher Digital pins fair value at $29.36. The market is therefore pricing in heavy doubt around the long term build out and lease up of its data center pipeline.
The rapid expansion and optimization of production capacity has shifted from adding Bitcoin hash rate to delivering hyperscale AI and high performance computing campuses such as Barber Lake, Black Pearl and Stingray. Signed leases and active construction are expected to convert gigawatt scale power into contracted rent streams that drive future revenue and net operating income.
See why 102 investors see Cipher Digital as 75% undervalued.
Result: Fair Value of $29.36 (UNDERVALUED)
Still, the Cipher Digital story depends on heavy borrowing and complex ERCOT approvals, so tighter credit or power delays could quickly challenge that undervalued narrative.
Find out about the key risks to this Cipher Digital narrative.
Another Look At Cipher Digital’s Rich Sales Multiple
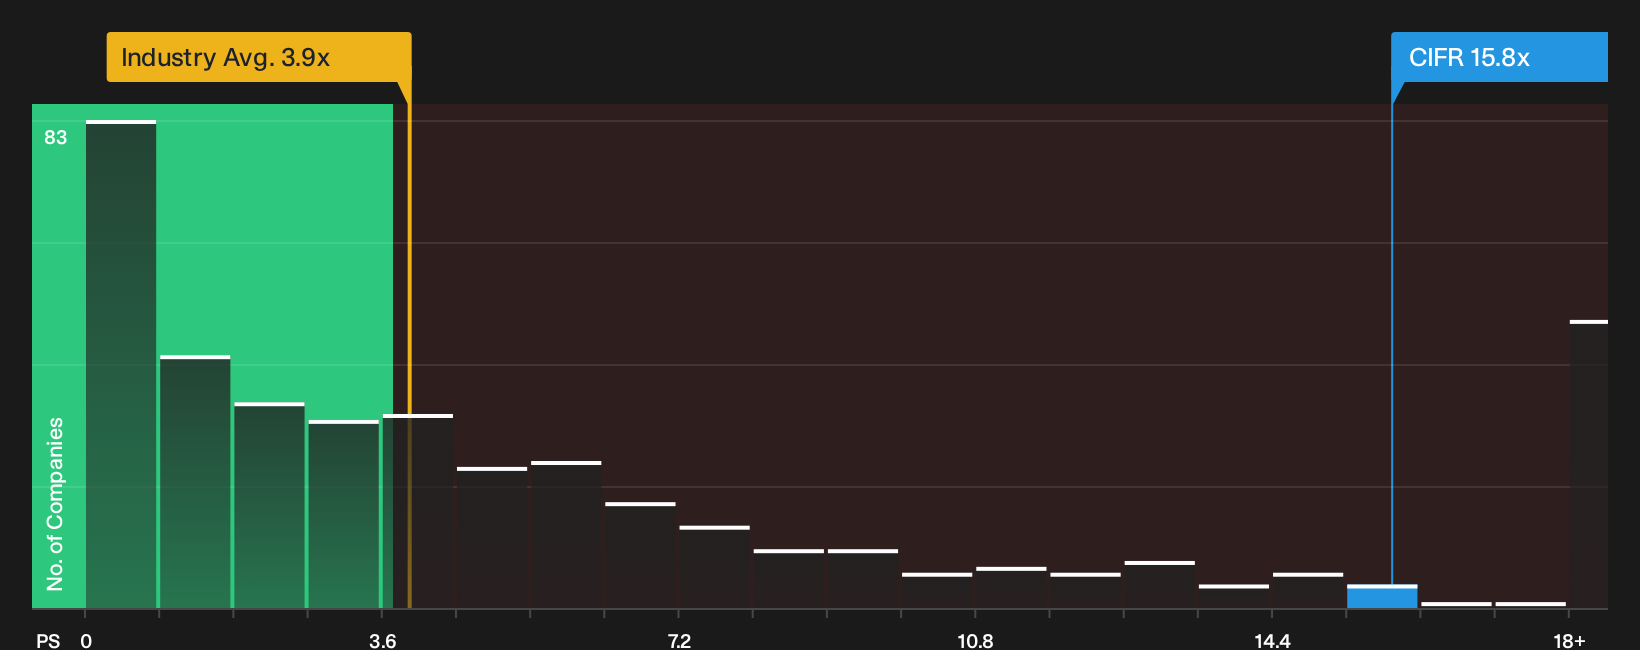
The story around Cipher Digital’s fair value leans heavily on future contracts and growth, yet today the stock changes hands at a P/S of 15.8x. That is far above the US Software peer average of 3.9x and the fair ratio of 2.6x, which points to meaningful valuation risk if sentiment cools further. How comfortable are you paying this kind of premium for a business that is still loss making?
Before leaning too hard on any single price target, it helps to see what the numbers are implying about this premium and how it could compress or hold over time. This is unpacked in more detail in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If sentiment around Cipher Digital now feels stretched in either direction, check the data for yourself, weigh both sides, then review the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Cipher Digital?
If Cipher Digital has your attention but you want backup options, broaden your watchlist with targeted ideas that match your risk appetite and income goals.
- Target potential value opportunities by scanning a curated 33 high quality undervalued stocks that focus on quality fundamentals at prices the market may be discounting.
- Lock in potential income streams by reviewing a hand picked 5 dividend fortresses built around higher yields and balance sheet support.
- Limit unwanted shocks by filtering for a list of solid balance sheet and fundamentals (24 results) so you can focus on companies with sturdier financial foundations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com