


Entegris (ENTG) Lifts Fourth Quarter Outlook As Valuation Debate Heats Up
Entegris (ENTG) has just paired a strong third quarter update with fresh fourth quarter guidance, giving investors a clearer view of how current semiconductor demand is feeding through to sales, profit and cash generation.
Despite a 1-day share price decline of 3.51% to US$154.39 after the update, Entegris has a 7-day share price return of 14.77% and a year-to-date share price return of 72.39%, while the 1-year total shareholder return of 69.12% points to strong momentum built over a longer period.
Scan beyond Entegris and review other semiconductor suppliers benefiting from similar demand trends with our curated list of 54 AI infrastructure stocks in the current chip buildout.
Entegris now trades well above where it started the year after that sharp recent rise. The real decision is whether to lean in at this level or wait for a cooler entry as the valuation picture comes into focus.
Most Popular Narrative: 18% Undervalued
Entegris is currently trading at $154.39 compared with a most followed narrative fair value of $189.07, so the story hinges on whether that gap is justified by future growth and margins built into that model.
Operational optimization, including the ramp of the KSP Taiwan filtration facility toward breakeven, closures of dilutive sites and a more than 20% increase in factory direct labor to tap existing capacity, is already lifting gross margin and can further support net margin and free cash flow as fixed costs are spread over higher volumes.
See why 13 investors see Entegris as 18% undervalued.
Result: Fair Value of $189.07 (UNDERVALUED)
Still, if Entegris’ revenue trend continues to be described as flat and the valuation keeps screening as rich with insider selling, the bullish narrative could quickly lose traction.
Find out about the key risks to this Entegris narrative.
Another View: Entegris Looks Expensive On Earnings
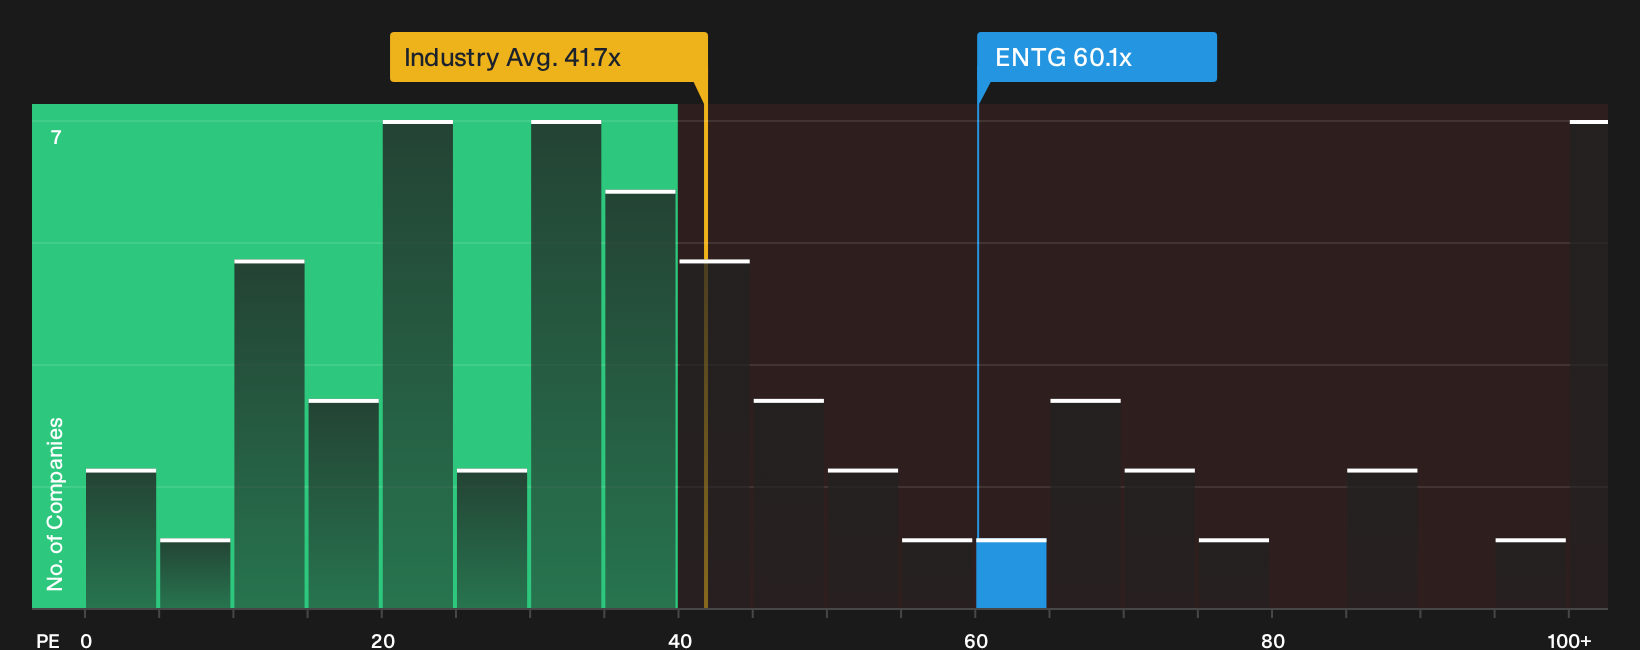
That fair value narrative points to Entegris as undervalued, yet the earnings multiple paints a tougher picture. The stock trades on a P/E of 60.1x, compared with about 41.7x for the US Semiconductor group and 29.9x for direct peers, while the fair ratio sits at 32.2x.
Put simply, the current tag is almost double that fair ratio. This suggests that even solid execution could be met with P/E compression rather than a smooth ride higher. If sentiment cools or growth expectations are revised, how much downside are you really comfortable underwriting at this entry point?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of excitement and caution feels familiar, take a moment to move beyond the headline metrics and weigh both sides for yourself. To see the full balance of concerns and potential upside, start with the 2 key rewards and 2 important warning signs.
Looking for more Entegris investment ideas?
If you are serious about putting Entegris in context, do not stop here. Use the Simply Wall Street Screener to quickly surface fresh opportunities that match how you like to invest, so you are not relying on one stock to carry your whole plan.
- Target potential mispricings by scanning a curated 33 high quality undervalued stocks that combine quality fundamentals with pricing that still looks reasonable on the numbers.
- Build a sturdier foundation by focusing on companies in the list of solid balance sheet and fundamentals (24 results) so your portfolio leans on healthier finances rather than hope.
- Get in early on promising stories using the 19 high quality undiscovered gems before broader attention and heavy flows crowd the opportunity set.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com