


Metro (HMSE:B4B0), What Is Driving The Attention Around It?
Metro (HMSE:B4B0) has drawn attention after recent trading left the share price at €7.26. The wholesale-focused group has shown modest single digit moves over the past week, month and past 3 months.
What really matters for Metro is the bigger arc. The year-to-date share price return of 26.92% and 1-year total shareholder return of 30.58% point to steady positive momentum rather than a quick trade, with recent moves at €7.26 reflecting a market that is gradually reassessing both its risk profile and potential.
Compare Metro's recent re-rating with other wholesalers and retailers on the move by scanning our curated list of 204 high quality undervalued stocks.
The latest shift in Metro's share price can be read as a vote on the wholesale engine behind the group, or as a swing in sentiment. The valuation now needs to separate those two stories.
Preferred Price-to-Sales of 0.1x: Is It Justified?
On simple sales-based metrics, Metro looks heavily marked down. The stock closed at €7.26 while the group generated €33,139.0m in revenue, which leaves the market valuing the wholesale operator at a P/S of roughly 0.1x, well below typical retail and distribution peers.
The P/S ratio compares the value the market places on the equity to the turnover the business produces. For a food wholesaler like Metro, where earnings can be volatile due to thin margins and cost swings, investors often fall back on sales as a cleaner reference point. A very low P/S can signal skepticism about future profitability, concerns over balance sheet risk, or simply a lack of interest in the story.
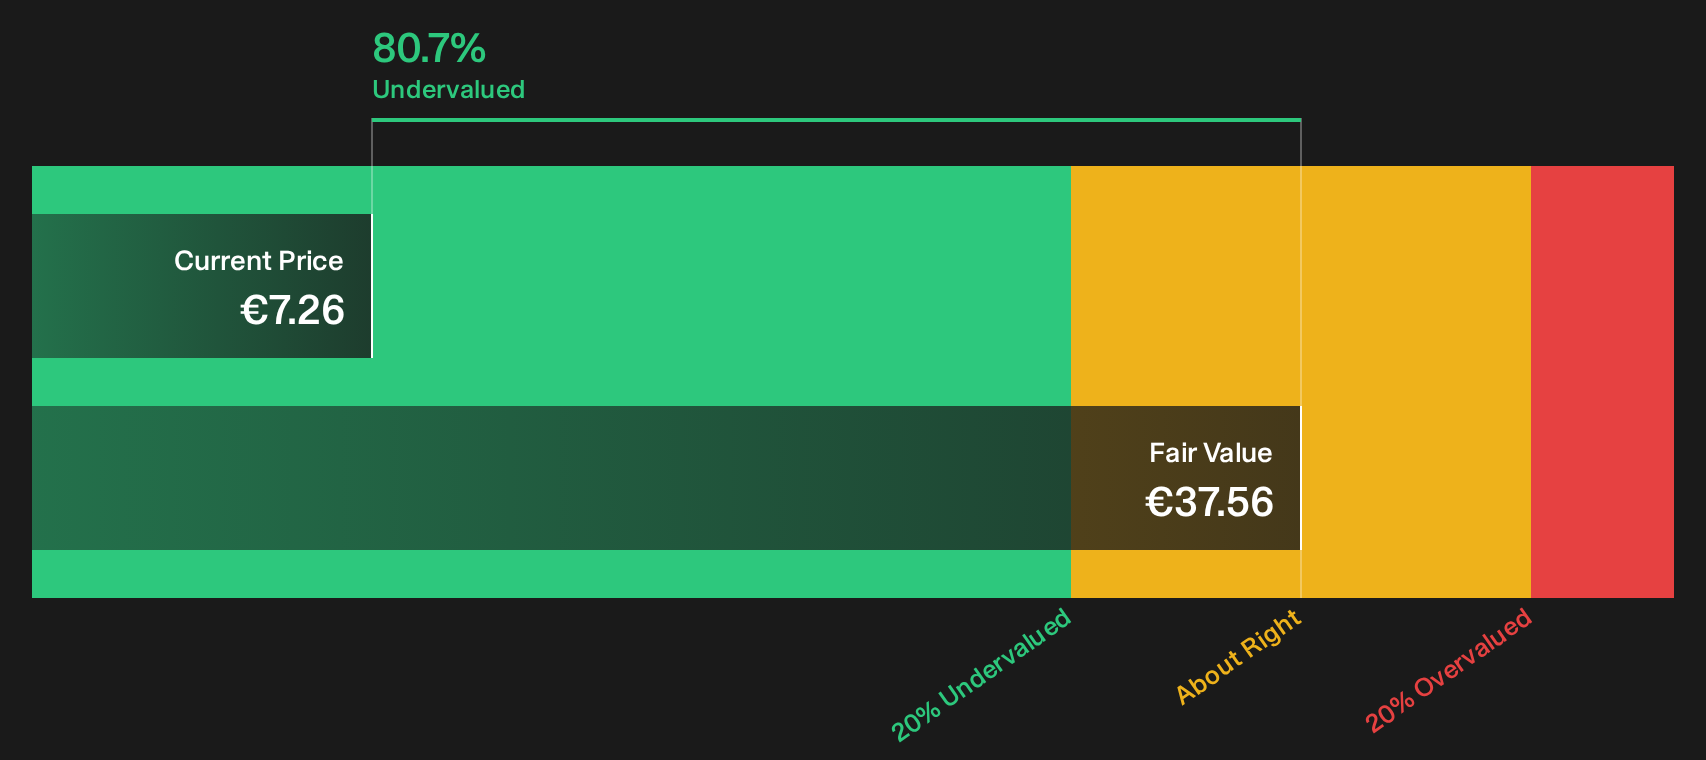
Metro is currently unprofitable, with a net loss of €264.0m and a declining earnings profile over the past 5 years, so the discounted P/S multiple is consistent with the loss-making status. At the same time, Simply Wall St’s DCF work suggests the shares are trading at a steep 80.7% discount to its estimate of fair value. The SWS DCF model values the future cash flow stream at €37.56 per share compared with today’s €7.26. The market is pricing in a lot of caution on earnings quality and funding risk, while the model implies much stronger long term cash generation than the headline loss might suggest.
On pure peer comparison, the gap is wide. Metro’s 0.1x P/S is described as good value versus both the European Consumer Retailing industry average of 0.4x and the peer group average of 0.2x. That is a deep discount on sales, which indicates investors are assigning materially lower expectations to this wholesaler than to other retailers with similar turnover profiles.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Sales of 0.1x (UNDERVALUED)
Still, the net loss of €264.0m and Metro’s reliance on thin-margin wholesale volumes could quickly challenge that low P/S story if funding costs or customer demand shift.
Find out about the key risks to this Metro narrative.
Another View: Metro Through a Cash Flow Lens
Metro looks cheap on sales, yet the SWS DCF model goes even further. That framework values the projected cash flows at €37.56 per share, which is far above the current €7.26 price and flags the stock as heavily undervalued on this measure.
The big question is why the market is this cautious on an unprofitable wholesaler when the cash flow model points to such a wide gap. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Metro for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 204 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split between caution and optimism around Metro feels sharp, that is the point, and the reason to move quickly and review the details yourself. To see how the concerns stack up against the potential upside, take a look at the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Metro?
If Metro has caught your eye, do not stop there. Broader context helps you avoid blind spots and spot opportunities you might otherwise overlook.
Use the Simply Wall St Screener today to pressure test your thinking against other potential ideas before the market moves without you.
- Target underappreciated quality by scanning companies flagged as high potential on valuation and fundamentals via the 614 high quality undiscovered gems.
- Prioritise resilience first and returns second by reviewing a 218 resilient stocks with low risk scores that can help anchor a more defensive corner of your portfolio.
- Hunt for stronger balance sheets by focusing on businesses in the list of solid balance sheet and fundamentals (199 results) that combine financial strength with consistent fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com