


How Investors May Respond To Align Technology (ALGN) Cautious Outlook And CEO Change
- Align Technology reported Q3 2026 results with US$1,014.76 million in sales and US$135.04 million in net income, issued cautious Q4 and full year 2026 guidance, and confirmed a CEO transition to Jennifer L. Davis after Joseph M. Hogan retires.
- The combination of higher year on year earnings, a conservative revenue outlook linked to consumer and macro pressures, and the appointment of a healthcare veteran from Procter & Gamble is putting both Align Technology’s execution discipline and long term strategic direction under closer investor scrutiny.
- The focus now shifts to how Align Technology’s investment narrative around margins and clear aligner penetration aligns with the cautious revenue guidance.
Scan how Align Technology’s cautious guidance and CEO transition compare with other dental and healthcare stocks by reviewing our curated 34 healthcare AI stocks that could be setting up their next move.
Align Technology Investment Narrative Recap
To own Align Technology, you need to believe in clear aligners gaining more share globally and the firm turning that demand into steadier profitability. The Q4 and 2026 guidance of roughly US$1.0b in quarterly sales and about US$4.1b for the year, with operating margins in the high teens, keeps the focus on execution rather than acceleration.
The near term swing factor remains how consumer reticence affects North America volumes versus healthier international and DSO channels. The main risk is that a mix shift toward lower priced scanner models and any added regulatory costs in Europe or the U.K. could cap margin progress even if case volumes hold up.
The CEO transition to Jennifer L. Davis is the announcement that matters most for this catalyst story. Her background running Procter & Gamble’s global healthcare unit, including oral health brands, is directly relevant to Align Technology’s push to deepen doctor engagement and sell more digitally enabled treatments worldwide.
Execution around this handover will be closely watched. Investors will track whether margin targets, scanner adoption models and new products such as the sports mouthguard line are delivered consistently through and after 2026, without disruption from governance changes, legal processes or the shift in leadership responsibilities.
Align Technology Consensus Assumptions And Valuation Setup
Analyst models around Align Technology sketch out a fairly specific destination for the next few years, even if the road to get there looks bumpy after the latest guidance and CEO change. Forecasts point to mid single digit annual revenue expansion, thicker margins and higher earnings by the end of the decade, which is what underpins the current set of price targets you see quoted today.
Align Technology's narrative projects US$4.7b revenue and US$750.6m earnings by 2029. This is based on analysts penciling in 4.5% yearly revenue growth and an earnings increase of about US$337m from US$413.6m today.
Those consensus numbers matter because they anchor how much execution room the new leadership team has. Analysts are baking in revenue growth of about 4.5% a year for the next three years, an uplift in profit margins from 10.0% today to 15.9% around 2029 and earnings reaching roughly US$750.6m in that same year compared with US$413.6m at present.
The same set of assumptions implies that for the current analyst price target to make sense, Align Technology would be trading on a P/E ratio of 21.6x those 2029 earnings. That is below the 26.1x multiple applied to the stock today and also under the 26.9x level quoted for the wider US medical equipment peer group, which hints that the market is already factoring in some uncertainty around the path to those higher profits.
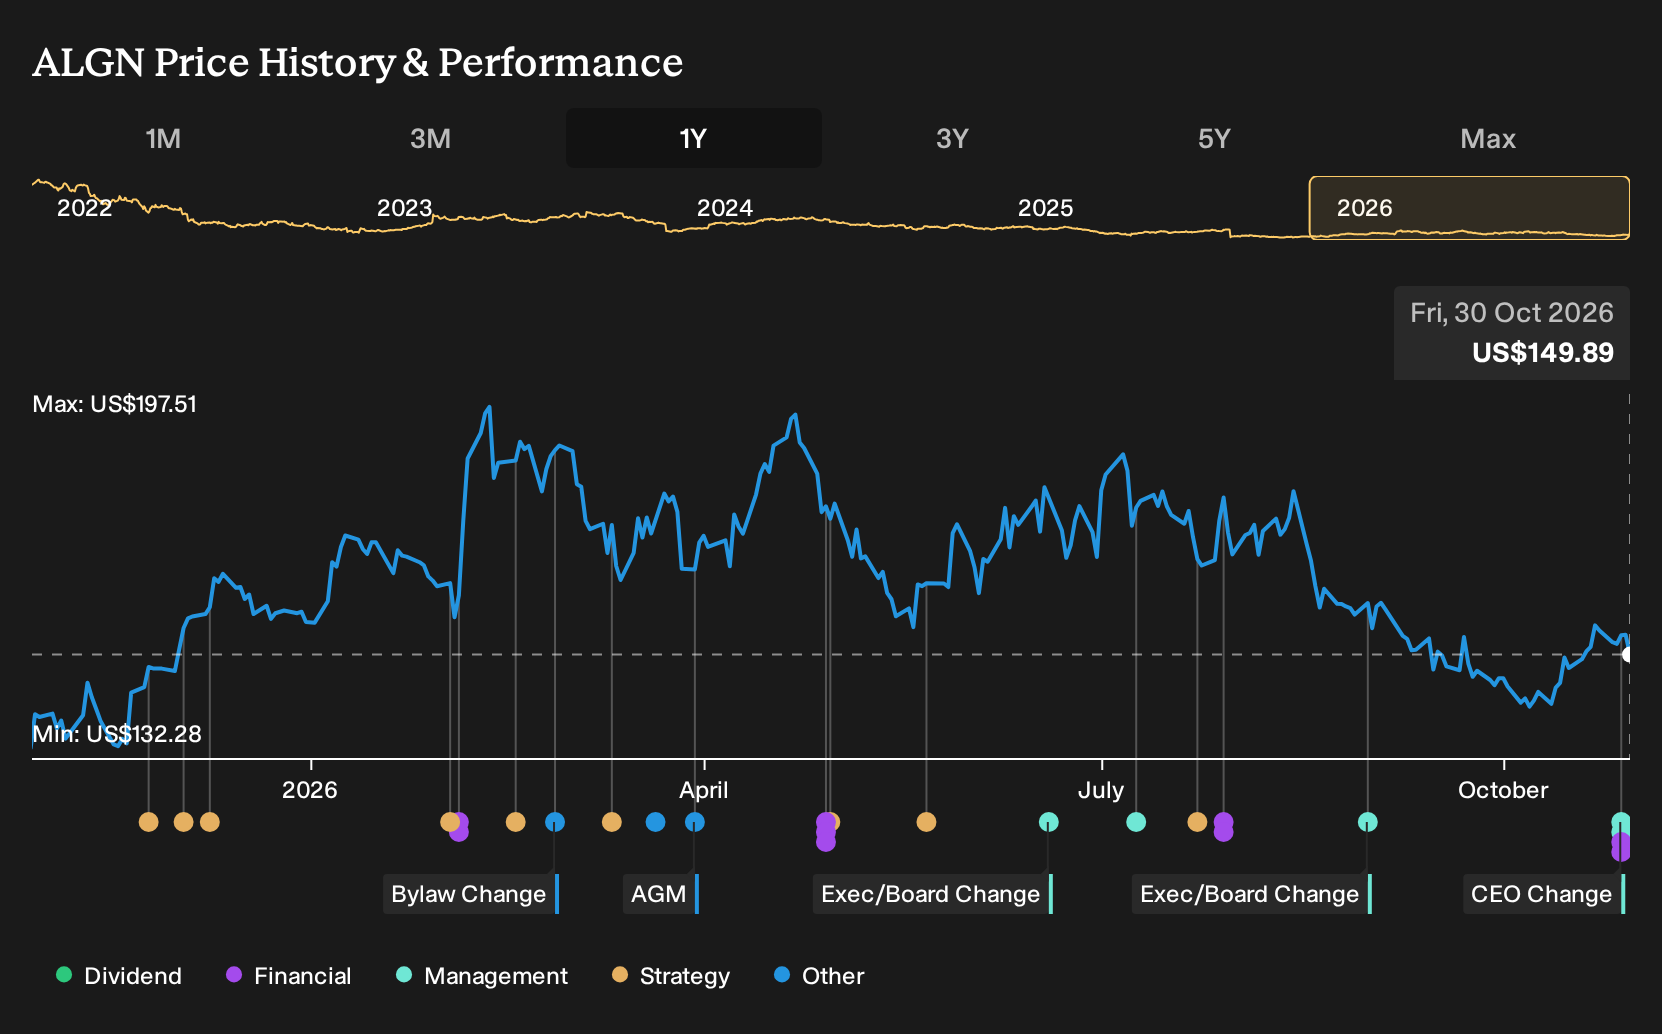
On the valuation side, the consensus framework effectively says this: by 2029, Align Technology would be generating about US$4.7b of revenue and US$750.6m of earnings, with investors willing to pay 21.6x for those profits at a discount rate close to 7.5%. The gap between the recent share price of US$151.95 and the average analyst target of US$188.86 is framed against that earnings and multiple setup, while the spread between the most bullish and most cautious targets, US$215.00 and US$155.00, flags real disagreement on how reliably the business can deliver those outcomes.
For you as an investor, the key question is not whether the consensus numbers are precise. The real test is whether Align Technology under a new CEO can sustain mid single digit top line growth, lift margins toward the high teens and manage regulatory and product mix pressures in scanners, all while shrinking its share count modestly by just under 1% per year as analysts assume. Your own view on those moving parts will drive whether the current valuation feels too stretched, too pessimistic or somewhere in between.
Uncover why Align Technology's fair value indicates a 26% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
For a sharper contrast, focus on the risk that Align Technology’s international opportunity underdelivers. The most cautious analysts were only assuming about US$4.4b of revenue and US$701.7m of earnings by 2029 before this guidance and CEO news. That is a much cooler outlook. Use it as a prompt to explore several competing narratives yourself.
Explore 5 other Align Technology fair value estimates, including one that suggests it could be worth just $154.62.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Align Technology research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Align Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Align Technology's overall financial health at a glance.
Looking for more investment ideas beyond Align Technology?
If Align Technology has sharpened your thinking about risk, reward and execution, it can help to line it up against other opportunities and see what really earns a place on your watchlist.
- For investors who want potential value upside with balance sheet support, scan a 33 high quality undervalued stocks that already meet strict quality and valuation filters.
- If capital preservation is your first filter, focus on 29 resilient stocks with low risk scores that score well on stability and financial resilience.
- When you want fresh ideas beyond the usual tickers, widen your net with a 19 high quality undiscovered gems that pair solid fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com