


Raised 2026 Guidance Could Be A Big Deal For Ipsen Stock (ENXTPA:IPN)
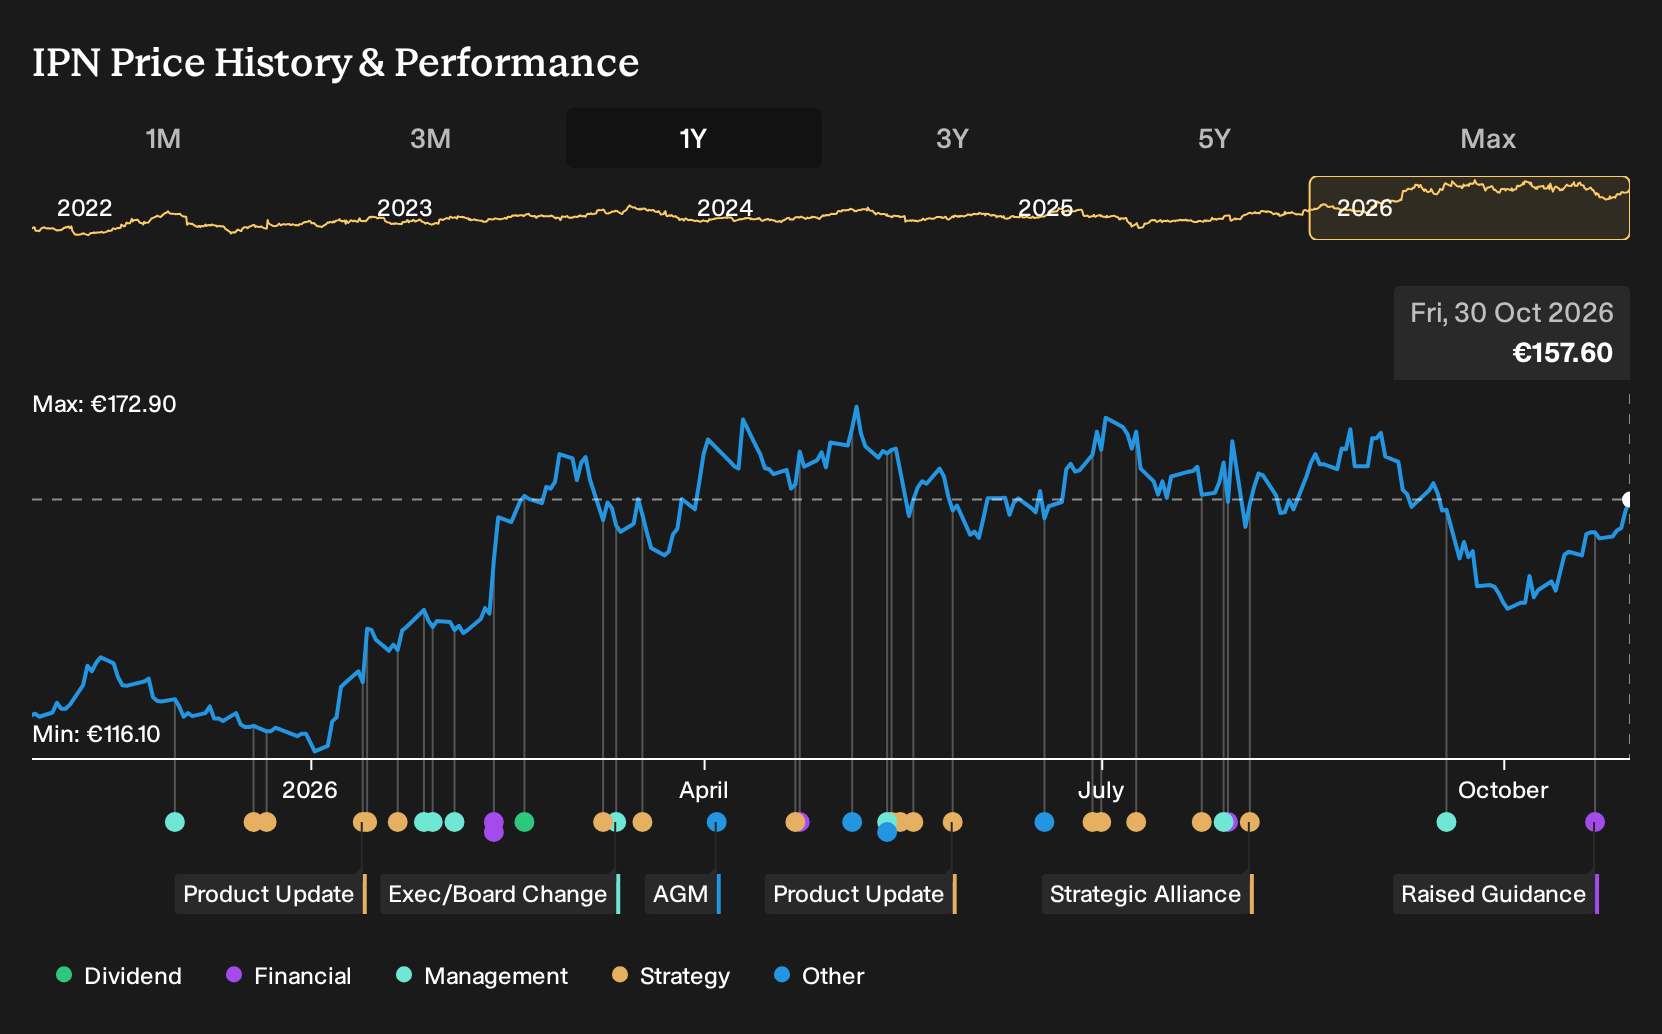
- In October 2026, Ipsen raised its full-year 2026 guidance, now targeting around 23.0% total sales growth at constant exchange rates and a core operating margin around 39.0% of total sales, while flagging an expected 0.5% currency drag.
- The upgrade hinges on strong double-digit sales from Ipsen's core portfolio and continued Somatuline contribution even with assumed generic lanreotide entry in the fourth quarter, which highlights management's confidence in defending a key product franchise under competitive pressure.
- We will now explore how Ipsen's higher 2026 margin and sales guidance could reshape the existing investment narrative around portfolio concentration.
Ipsen Investment Narrative Recap
To own Ipsen, you need to accept a concentrated portfolio in oncology, rare disease and neuroscience, and trust that newer drugs can gradually rebalance reliance on Somatuline. The raised 2026 guidance points to a business currently absorbing launch costs and pricing pressure while still targeting higher profitability.
The key short term swing factor remains how resilient Somatuline is once generic lanreotide arrives in the fourth quarter. Management is including ongoing Somatuline growth and strong double digit gains in the core portfolio in its outlook, so any sharper than implied generic impact or slower uptake of new launches would be the biggest near term risk.
The fresh guidance upgrade is itself the most important recent announcement for this story because it directly addresses two long running questions. First, whether Ipsen can support mid to high single digit growth assumptions with concentrated revenue streams. Second, whether higher R&D and commercial spend to build out Iqirvo, Bylvay and other assets is compressing margins.
Management now aims for around 23.0% sales growth at constant exchange rates in 2026 and a core operating margin around 39.0% of sales, while acknowledging a 0.5% currency drag. For you, that puts execution on the core portfolio and Somatuline pricing at the center of the catalyst map, with risks tied to generics, payer pressure and any bumpier than planned ramp of the late stage pipeline.
Ipsen's current analyst narrative points to revenues of €5.0 billion and earnings of €981.1 million by 2029. That profile assumes forecast revenue growth of 5.1% per year and an earnings increase of about €468.5 million from earnings today of €512.6 million.
Uncover why Ipsen's fair value points to a 3% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternate view puts Ipsen’s late stage pipeline front and center as a potential positive surprise. Before this guidance lift, the most optimistic analysts were already penciling in about €5.4b of revenue and €1.2b of earnings by 2029. You can see how this raised outlook might push that bullish camp even further, while others stay closer to the €981.1m consensus and await more evidence. That spread shows how sharply opinions can differ, so it is worth exploring several angles before you decide how this guidance change fits your own Ipsen thesis.
Explore another Ipsen fair value estimate, including one that suggests as much as 88% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ipsen research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ipsen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ipsen's overall financial health at a glance.
Looking for more investment ideas beyond Ipsen?
If the Ipsen story has sharpened your thinking about risk, concentration, and guidance, it can be useful to line it up against a wider watchlist built from other clear, data driven filters.
- If you want potential mispricing with quality in focus, start with a curated set of 204 high quality undervalued stocks that pair fundamentals with attractive pricing signals.
- For investors who care most about resilience and capital protection, scan a 218 resilient stocks with low risk scores to see which businesses score well on stability and balance sheet strength.
- If you are hunting for underfollowed opportunities, broaden your radar with a 614 high quality undiscovered gems that combines strong financial profiles with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com