


How Investors May Respond To ITT (ITT) Connector Orders Surge
- ITT Inc.'s Connect and Control Technologies segment reported 17.3% organic revenue growth and a 59% surge in organic orders in Q2 2026, supported by stronger connector demand and aerospace and defense activity.
- The recent kSARIA acquisition plugs ITT directly into higher visibility defense fiber interconnect projects and points to a deeper, more specialized role in critical military programs.
- We will look at how ITT's investment narrative is shaped by this sharp order growth in Connect and Control Technologies.
Scan other defense and connector plays moving on similar trends to ITT with our hand picked 41 power grid technology and infrastructure stocks for potential ideas related to mission critical infrastructure exposure.
ITT Investment Narrative Recap
An investor in ITT needs to believe the company can turn its strong order book in areas like connectors and aerospace and defense into steadier revenue, better margins and healthier cash generation over time. The recent 17.3% organic revenue growth and 59% order jump in Connect and Control Technologies support that demand picture, although the impact is still concentrated in one segment.
In the near term, the key swing factor is whether ITT can convert this higher visibility backlog into earnings without further pressure on profit margins or cash flow. Reliance on large projects and acquisitions like kSARIA keeps integration and timing risk in focus, especially after margins already moved lower versus last year.
The kSARIA acquisition looks most relevant here. It ties ITT more closely to defense fiber interconnect work, which complements the strong order intake in Connect and Control Technologies and fits with the push toward long cycle, higher visibility programs that analysts highlight as a key driver for the business.
For you, the interest is whether kSARIA helps offset some of the biggest current issues, such as thinner margins, debt that is not yet well covered by operating cash flow and the initial dilution from recent deals. Execution on integration, cost efficiencies and program delivery will likely decide how much of the current order strength turns into durable earnings and steadier cash generation.
ITT's narrative projects US$6.5b revenue and US$802.9m earnings by 2029. This assumes 11.3% yearly revenue growth and roughly a 90% earnings increase from US$421.6m today.
Uncover why ITT's fair value indicates a 30% potential upside to its current price that may not last much longer.
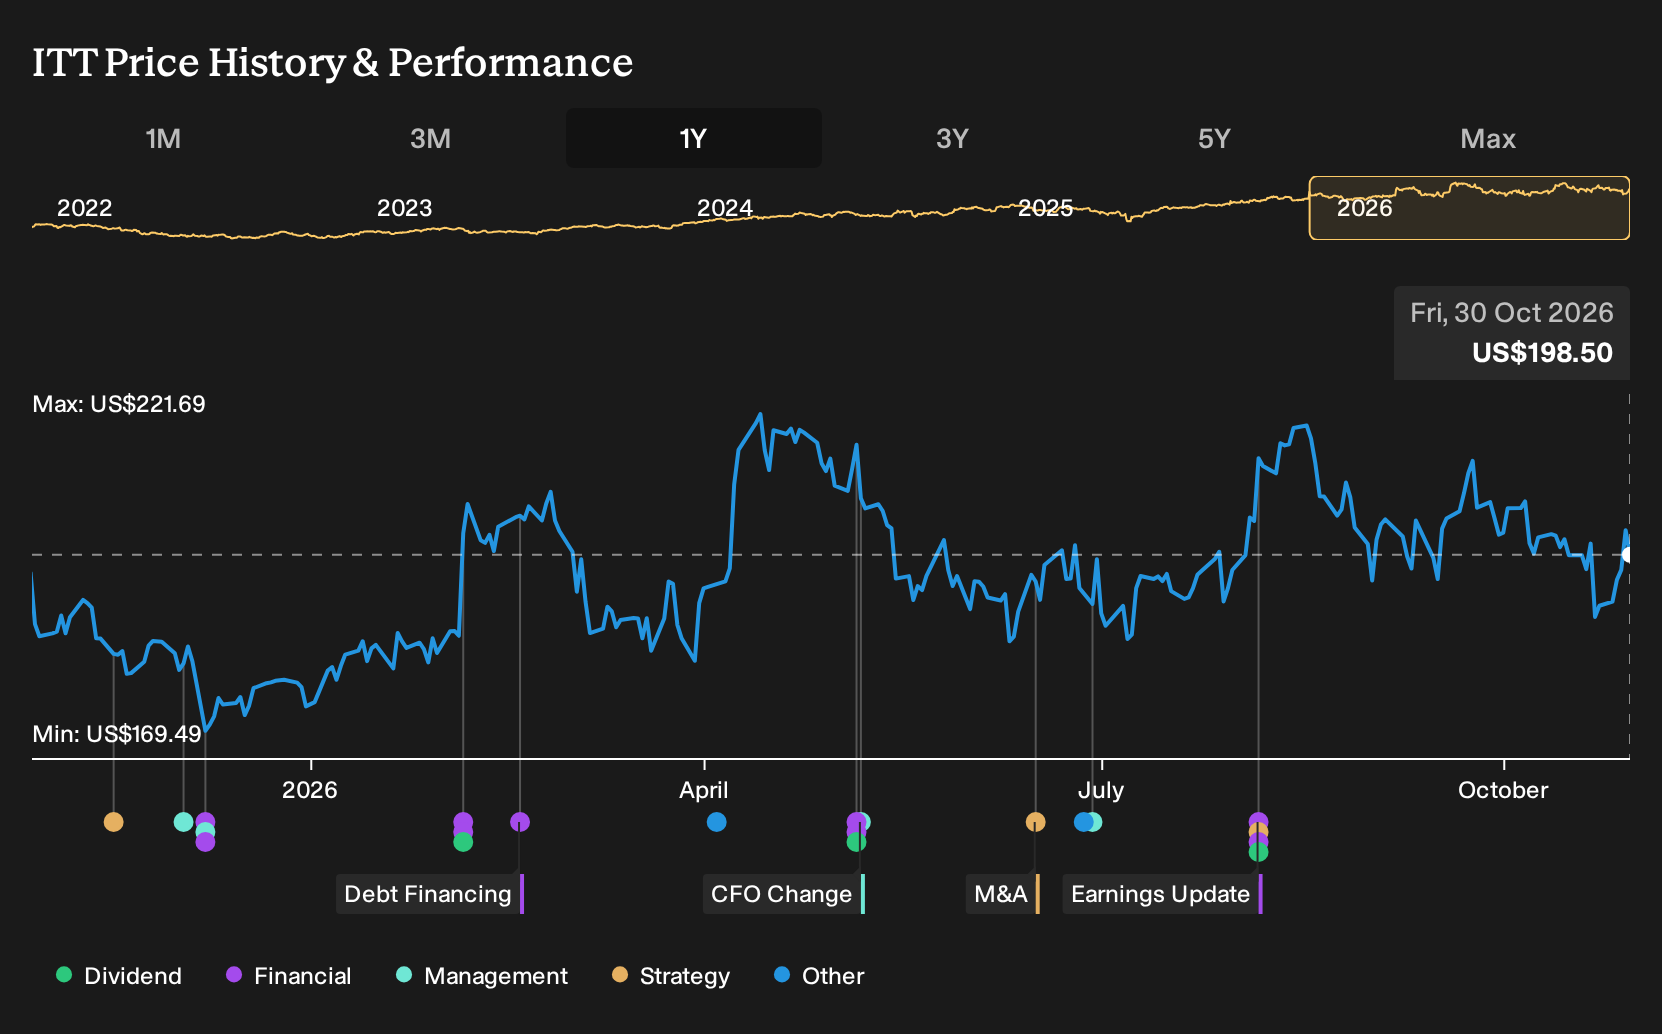
Exploring Other Perspectives
One wrinkle the more cautious analysts keep flagging is tax. Before this latest ITT Connect and Control update, the lowest forecasts were built on a higher 24.9% tax rate that, in their view, would cap earnings at about US$653.5m on US$6.7b revenue by 2029. That is a much more restrained story than the consensus. It shows how sharply opinions can diverge. You can use this fresh CCT order news as a reason to compare those older revenue and earnings paths and decide which version of ITT’s future feels more realistic to you.
Explore another ITT fair value estimate, including one that suggests it could be worth just $247.01!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ITT research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ITT. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ITT's overall financial health at a glance.
Looking For More Investment Ideas Beyond ITT?
If the ITT story has you thinking about how to round out your watchlist, it can help to line it up against other companies with different strengths and risk profiles using the Simply Wall St Screener.
- For investors focused on quality at a reasonable price, compare ITT against a 33 high quality undervalued stocks that may offer stronger fundamentals at current valuations.
- If resilience matters most to you, weigh ITT alongside a 29 resilient stocks with low risk scores that screens for businesses with steadier risk profiles.
- For those who care most about balance sheet strength, set ITT next to a list of solid balance sheet and fundamentals (24 results) to see which companies pair financial resilience with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com