


Does Earnings Beat Change The Bull Case For WTW Stock?
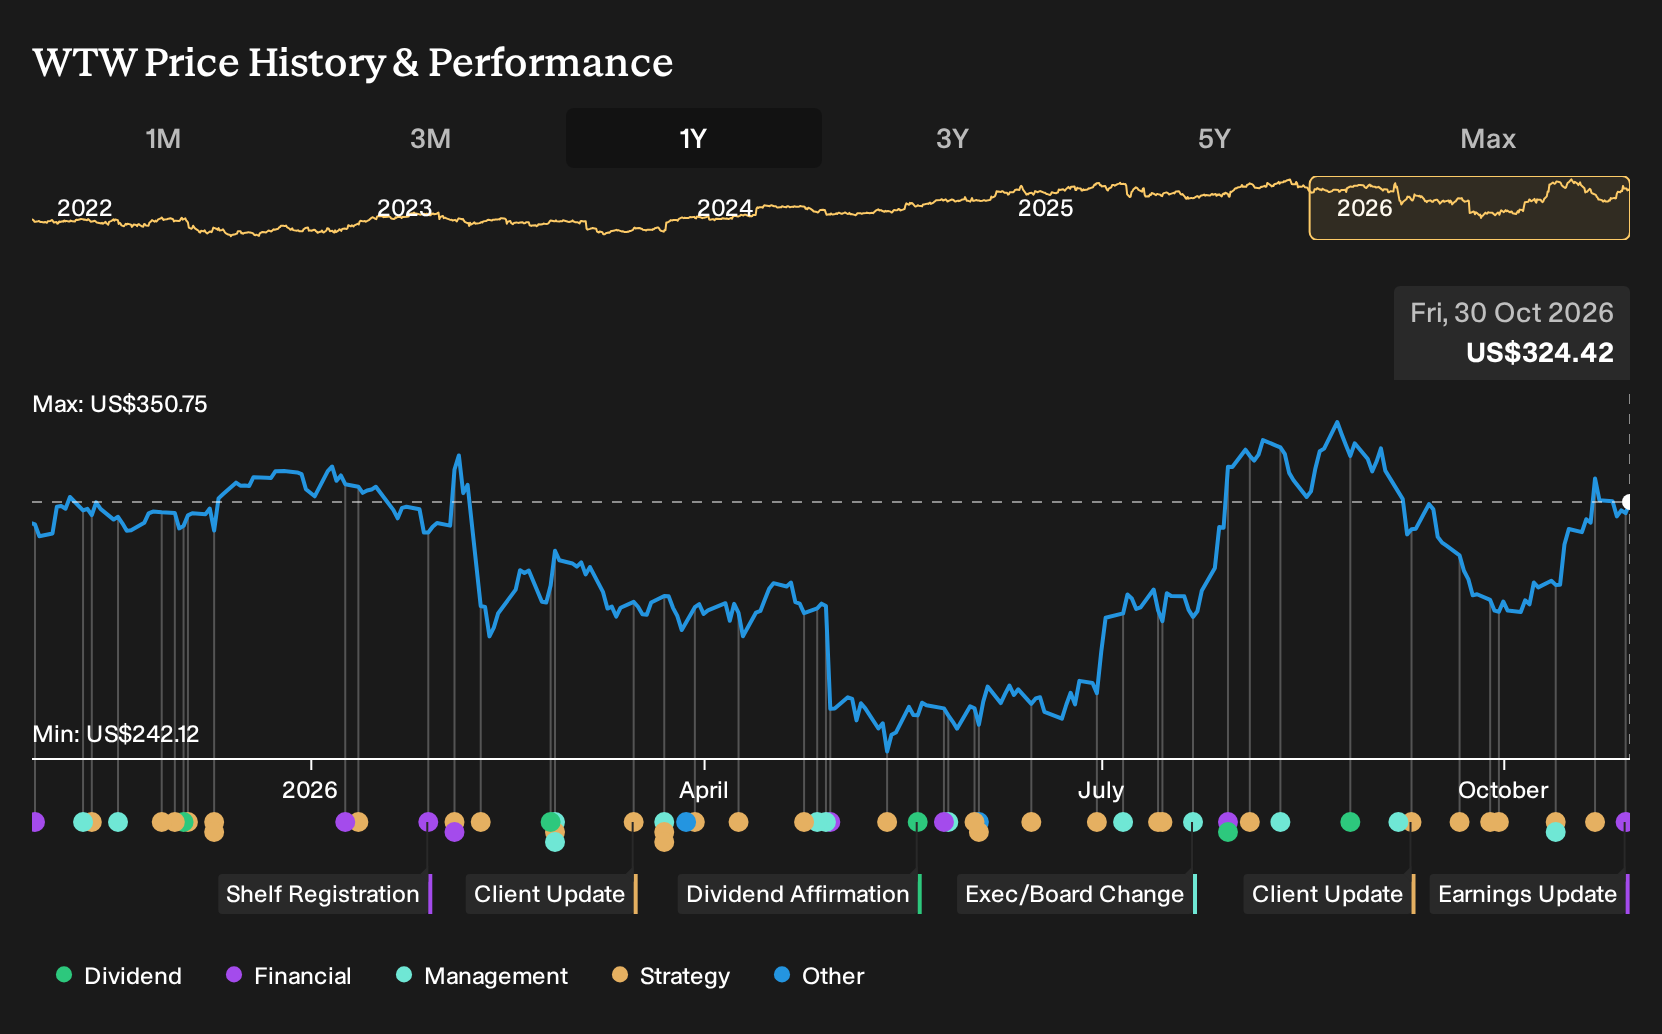
- Willis Towers Watson reported third quarter 2026 revenue of US$2.46b and net income of US$303m, with adjusted earnings and margins supported by organic growth, acquisitions and its Propel AI Acceleration Plan.
- The newly launched global Defense and Security initiative links risk advisory, broking and analytics for defense clients. This points to a focused push into complex, higher value sector work that leans on the firm’s specialty expertise and data tools.
- We will now look at how Willis Towers Watson's stronger margins tied to the Propel AI program could shape its investment narrative.
Willis Towers Watson Investment Narrative Recap
The core belief for a shareholder in Willis Towers Watson is pretty simple. You need to think this advisory and broking platform can convert the Propel AI Acceleration Plan and specialty focus into structurally higher margins without eroding the value of its advice. The latest quarter helps that case, with adjusted earnings per share at US$3.63 and adjusted operating margin at 21.9% showing early operating leverage.
The key near term swing factor is whether AI driven productivity and cost control keep offsetting softer commercial insurance pricing. The biggest risk right now sits on the other side of that bet. Accelerated adoption of automation across the sector could compress fees and make some services feel more commoditized, especially if competitors undercut pricing while WTW carries a relatively high level of debt.
The recent launch of the global Defense and Security initiative is tightly linked to that thesis. It plugs Willis Towers Watson’s risk advisory, broking and analytics into a single, sector led platform tailored to defense and security organizations that are dealing with complex, interconnected exposures across cyber, supply chain, regulatory and operational assurance.
For you as an investor, this matters because it leans into specialty work where standardized AI tools are less likely to flatten pricing quickly. Execution risk is real. The firm still has to show that these complex mandates produce durable fee pools and support margin progress while insurance pricing softens and talent competition stays intense.
Willis Towers Watson's current analyst narrative centers on revenues of US$11.9b and earnings of US$2.0b by 2029. This assumes revenue expanding at 5.8% per year and earnings rising by about US$400m from US$1.6b today to the US$2.0b consensus level in that forecast year.
Uncover why Willis Towers Watson's fair value indicates a 14% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$370 and US$473 per share, so some retail analysts see Willis Towers Watson as materially mispriced in both directions. You now have fresh Q3 earnings and the new Defense and Security initiative to weigh against those pre news models. Use that contrast to test your own view and explore how far opinions can stretch.
Explore 2 other Willis Towers Watson fair value estimates, including one that suggests as much as 46% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Willis Towers Watson research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Willis Towers Watson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Willis Towers Watson's overall financial health at a glance.
Looking for more investment ideas beyond Willis Towers Watson?
Once you have a view on Willis Towers Watson, it can help to line it up against a wider set of opportunities that share some of the qualities you care about. The Simply Wall St Screener is an easy way to do that without getting buried in raw data.
- If you want potential upside with a margin of safety, compare Willis Towers Watson against a curated 33 high quality undervalued stocks that already combine solid fundamentals with discounted valuations.
- For a focus on resilience before return, widen your search to 29 resilient stocks with low risk scores that pair sturdier balance sheets with lower overall risk scores.
- When you care most about financial strength and consistency, benchmark this stock against a list of solid balance sheet and fundamentals (24 results) to see which businesses clear a higher quality bar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com