


Could First National Bank Alaska (FBAK) Be 27% Undervalued On Its Double Dividend News?
First National Bank Alaska (FBAK) has put income front and center, with its board declaring both a regular and a special cash dividend of $4.00 per share, payable in December 2026.
Recent trading has been quietly positive, with First National Bank Alaska’s share price at $334.00 and a 30-day share price return of 3.73% adding to a 13.61% year-to-date share price gain. The 1-year total shareholder return of 27.23% and 3-year total shareholder return of 110.59% point to momentum that has been building over time as investors factor in income distributions and reassess the bank’s risk and reward profile.
Compare First National Bank Alaska’s dividend move with other income focused opportunities by scanning our hand picked 5 dividend fortresses for potential ideas.
After a double dividend announcement and a share price above $330, income looks generous but capital has already moved. Does the risk reward on First National Bank Alaska still lean toward new buyers, or more toward holders?
Price-to-Earnings of 12.7x: Is it justified?
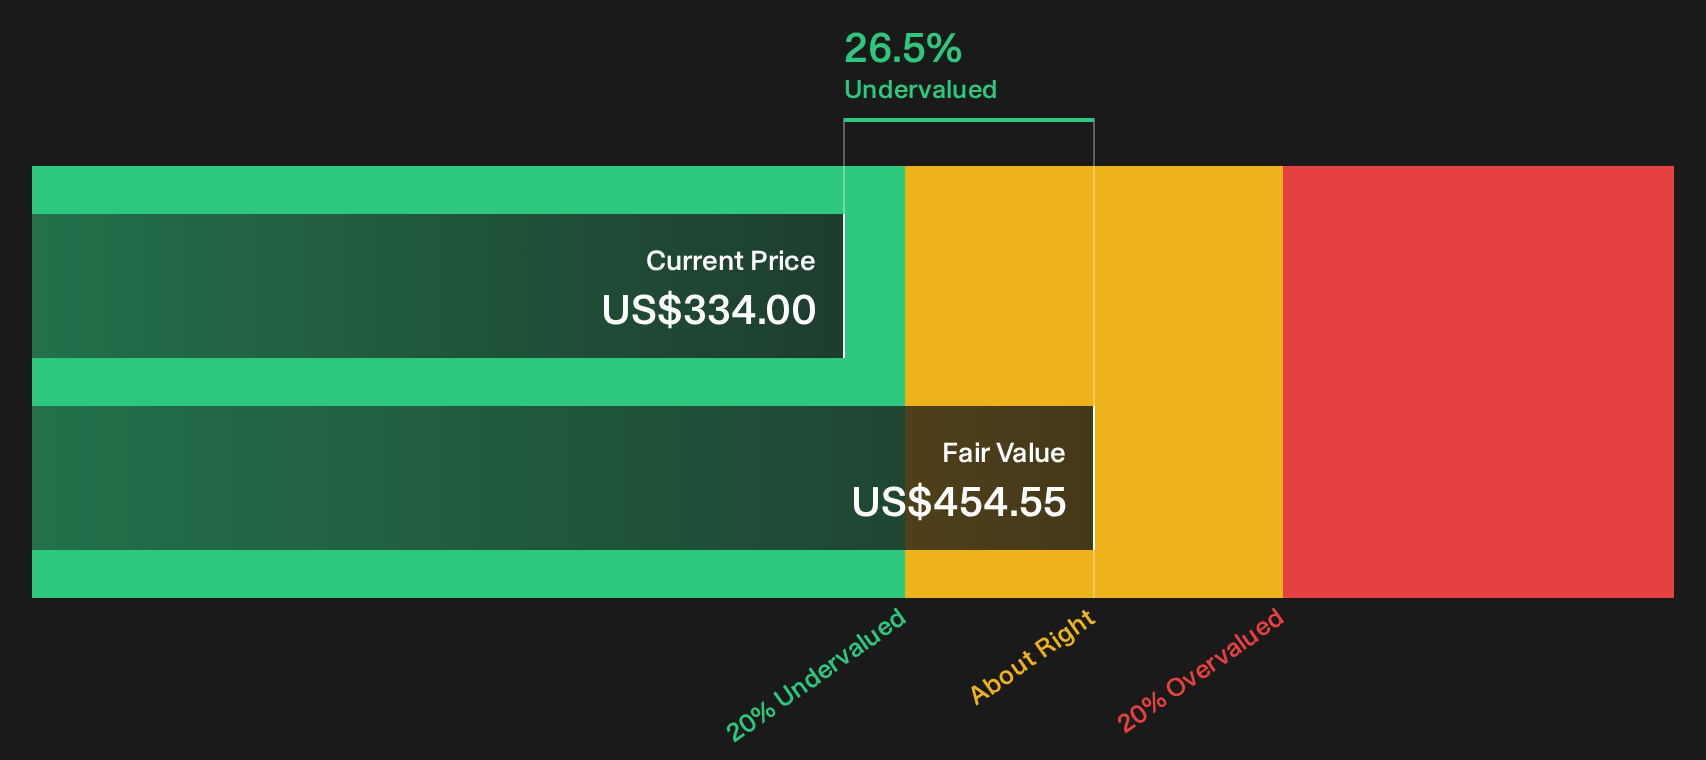
On valuation, First National Bank Alaska trades on a P/E of 12.7x, which sits above both its US Banks industry average of 11.4x and a peer group closer to 10.7x. The stock also changes hands at $334.00, while Simply Wall St's DCF estimate for future cash flows implies a value of $454.55, so the multiple is not the only lens that matters here.
The P/E ratio compares what you pay per share to the bank's earnings per share. For a lender like First National Bank Alaska, that measure often reflects how the market views the predictability of profit, the quality of the loan book, and the stability of earnings through the cycle.
Here, earnings quality is flagged as high, net profit margins are reported at 37.1% versus 36.2% a year earlier, and profit growth of 12.7% over the last year sits ahead of the 8% per year pace over five years. A richer P/E than peers suggests investors are willing to pay more for each dollar of earnings, potentially because they view this profit profile as relatively resilient, even if the 14.3% return on equity is described as low against a 20% benchmark.
Compared directly, that 12.7x P/E looks expensive versus both the broader US Banks industry at 11.4x and the closer peer group at 10.7x. The market is assigning First National Bank Alaska a premium tag on earnings, while the SWS DCF model points to the shares trading 26.5% below an assessed future cash flow value of $454.55, which sends a more supportive valuation message.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 12.7x (OVERVALUED) compared to peers.
Still, First National Bank Alaska faces potential pressure if credit conditions tighten or local economic activity in Alaska softens and weighs on loan performance and fee income.
Find out about the key risks to this First National Bank Alaska narrative.
Another View on First National Bank Alaska’s Value
Price-based ratios indicate that First National Bank Alaska appears expensive compared with U.S. bank peers, yet the SWS DCF model suggests a different view. With an estimated future cash flow value of $454.55 against a share price of $334.00, that framework presents the stock as undervalued. Which lens do you rely on more for your next decision?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out First National Bank Alaska for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty of signals around First National Bank Alaska point both ways, so do not wait too long to check the full balance of 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond First National Bank Alaska?
If First National Bank Alaska has your attention, do not stop here. Use the broader toolset to pressure test ideas and widen your opportunity set.
- Target potential value opportunities before the crowd by scanning our hand picked 33 high quality undervalued stocks to filter for quality fundamentals with prices that look out of line.
- Prioritise resilience in tougher conditions by using the 29 resilient stocks with low risk scores to focus on businesses with stronger risk profiles and steadier financials.
- Spot fresh opportunities early by running the 19 high quality undiscovered gems to highlight quality companies the wider market may not be paying close attention to yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com