


CStone Pharmaceuticals (SEHK:2616) Wins Fresh CS2009 Attention, Is The Valuation Already Priced In?
CStone Pharmaceuticals (SEHK:2616) has returned to focus after presenting extensive CS2009 data at the ESMO 2026 Congress, where the trispecific antibody reached proof of mechanism, safety, and concept across multiple solid tumors.
That ESMO update landed alongside a sharp move in the ticker, with the 1-day share price return of 4.33% and a 90-day share price gain of 14.35% contrasting with a 30-day share price decline of 16.27% and a 1-year total shareholder return down 21.09%. As a result, CStone Pharmaceuticals currently shows improving medium term momentum but a mixed long run record.
Scan beyond CStone Pharmaceuticals and explore other oncology focused biotechs that exhibit sharp valuation gaps with our curated 204 high quality undervalued stocks.
CStone Pharmaceuticals now has a headline asset attracting fresh attention and a share price that has already reacted. The real test is whether that renewed belief is already in the valuation or not.
Preferred Price-to-Sales Ratio of 15.7x: Is it justified?
CStone Pharmaceuticals closed at HK$4.94, and the current valuation story revolves around a P/S ratio of 15.7x that sends mixed signals when compared with both peers and a fair-value benchmark.
The P/S multiple compares the market value of CStone Pharmaceuticals to its annual revenue of HK$425.231m. For a biopharma group that is still loss making, this metric often becomes a shorthand for how much investors are willing to pay today for every HK$1 of current sales and, indirectly, their expectations for future commercial traction from assets like CEJEMLY and CS2009.
Relative pricing tells two different stories. Against its direct peer set, a 15.7x P/S is lower than the peer average of 18.3x, which suggests investors are assigning a lower revenue multiple than comparable biotechs and that some investors may view the stock as more restrainedly priced within that narrower group. Compared with the wider Hong Kong Biotechs industry though, where the average P/S is 7.7x, the same 15.7x ratio looks materially richer, and the estimated fair P/S of 5.2x is well below where the market is currently trading. This is a level the valuation could move toward if sentiment cools.
Explore the SWS fair ratio for CStone Pharmaceuticals.
Result: Price-to-Sales of 15.7x (OVERVALUED)
Still, the reliance on a small oncology portfolio and a reported net loss of CN¥419.104m leave CStone Pharmaceuticals exposed if product momentum or partnerships disappoint.
Find out about the key risks to this CStone Pharmaceuticals narrative.
Another view on CStone Pharmaceuticals using our DCF model
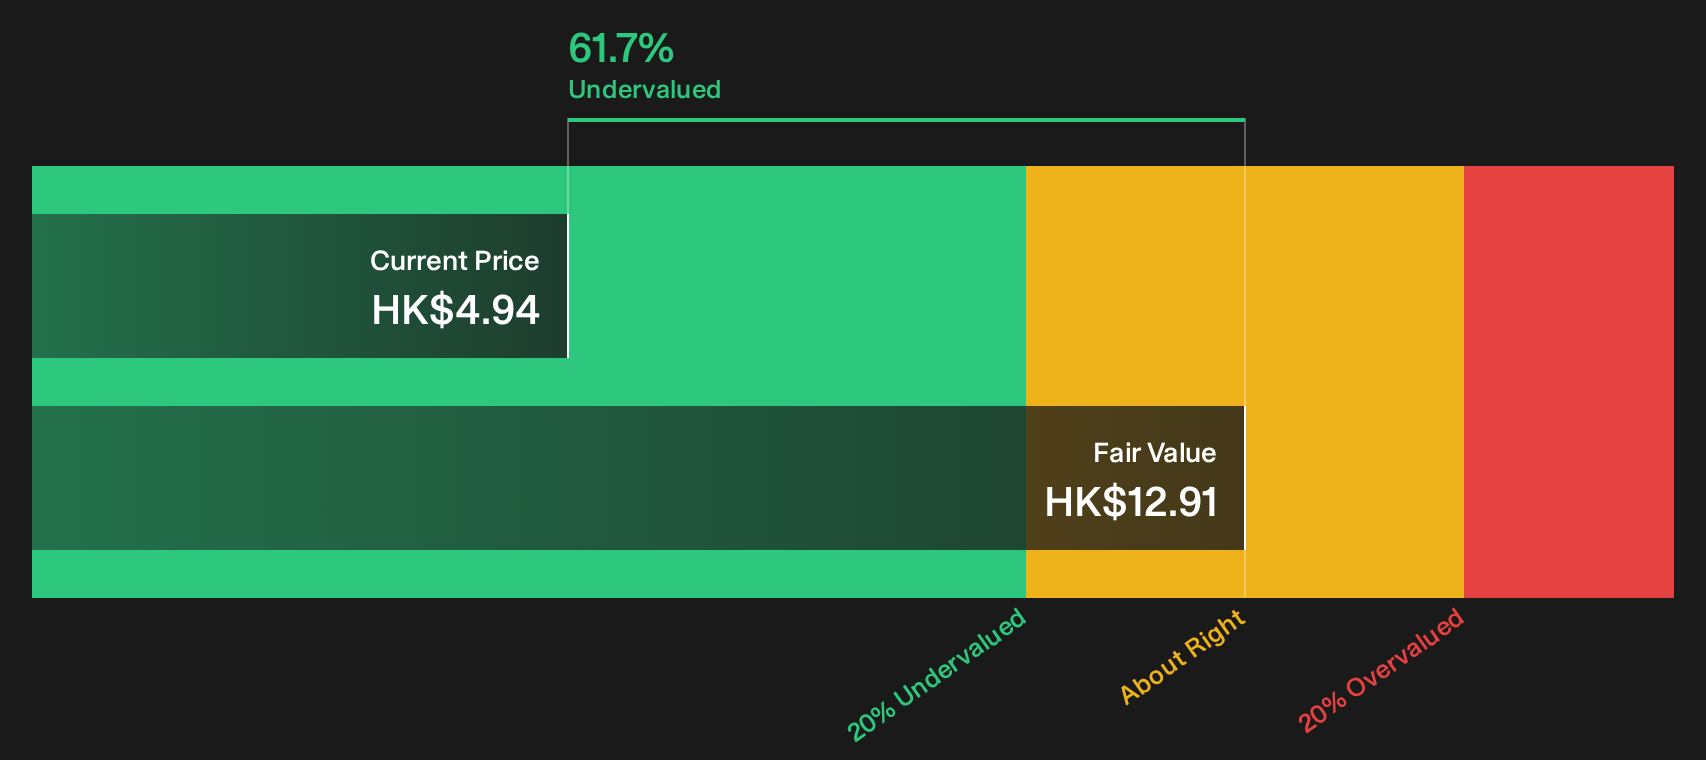
The picture shifts once you switch to our DCF model. On that framework, CStone Pharmaceuticals at HK$4.94 is compared with an estimated future cash flow value of HK$12.91. This comparison indicates that the share price is trading well below that reference point.
This contrasts with the richer P/S ratio and highlights a wide gap between what the market currently pays for each HK$ of reported sales and what the SWS DCF model suggests based on projected cash flows. The question for you is which set of assumptions feels more realistic.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CStone Pharmaceuticals for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 204 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around CStone Pharmaceuticals often come down to how you weigh its risks against its potential rewards, so reviewing the data yourself and deciding quickly can be useful before sentiment shifts. Tools like 2 key rewards and 1 important warning sign can help you see both sides in one place.
Looking for more investment ideas beyond CStone Pharmaceuticals?
If CStone Pharmaceuticals has sharpened your focus, you can use that momentum to broaden your watchlist with a few targeted stock ideas that fit different styles.
- Target potential value plays by scanning companies that currently screen as 204 high quality undervalued stocks and might warrant a closer look on your shortlist.
- Balance growth considerations with resilience by reviewing a list of solid balance sheet and fundamentals (199 results) so you can spot businesses with stronger financial foundations.
- Look for less crowded opportunities by sifting through 614 high quality undiscovered gems before other investors start paying attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com