


Learn Why The Bull Case For Barratt Redrow Stock Could Change Following Trading Updates
- Barratt Redrow recently drew investor focus after confirming upcoming trading updates and its Annual General Meeting, events that typically surface fresh detail on sales trends, build costs and cash use.
- The real interest is how management will use these updates to outline progress on multi brand sites, cost synergies and capital returns that are central to Barratt Redrow’s longer term story.
- We will now look at how Barratt Redrow's investment narrative could be influenced by the upcoming trading updates and AGM focus.
Scan how Barratt Redrow’s upcoming updates compare with peers by reviewing hand picked housing and construction stocks in the list of solid balance sheet and fundamentals (10 results).
Barratt Redrow Investment Narrative Recap
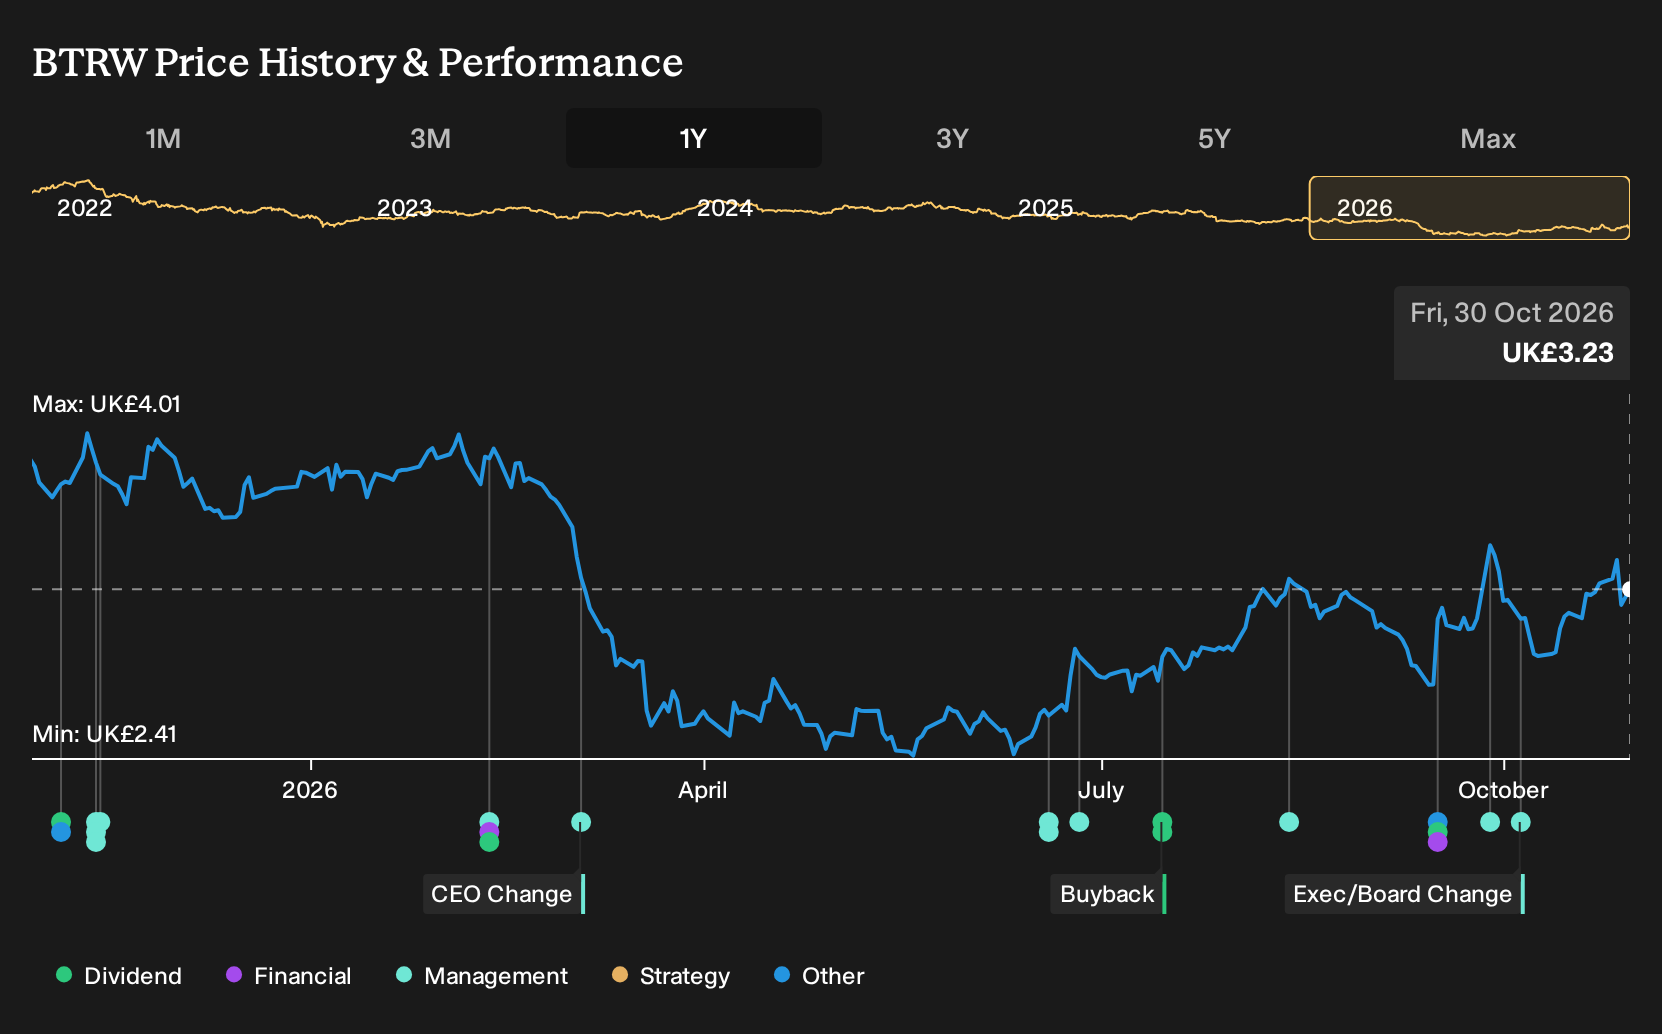
To own Barratt Redrow, you need to believe the combined housebuilder can keep turning multi brand sites, cost synergies and tighter land spending into resilient earnings, even with a mixed share price record over 1, 3 and 5 years. The upcoming trading updates and AGM mainly matter as a check on that operational story rather than a clear turning point.
The near term catalyst is evidence that more of the targeted £100m of annual synergies is flowing into margins while build cost inflation, guided at 3% to 4% in FY27, stays manageable. The biggest risk is that weaker selling prices and incentives further compress the land bank margin, making it harder to offset rising input costs and large remediation cash outflows.
The AGM and trading updates in the coming week look most relevant to the existing £400m capital return plan for FY27, largely through £386m of buybacks and a 1p dividend. Investors will likely focus on whether current trading, order book quality and cash generation still support that framework without stretching the balance sheet.
Those disclosures also sit alongside the enlarged £900m revolving credit facility and the goal of £400m to £500m net cash by FY27 year end. Together, these give context for how Barratt Redrow can fund build volumes and remediation outflows while pursuing growth in the number of multi branded outlets. This remains a key operational lever for future earnings power.
Barratt Redrow's narrative references analyst expectations for £6.9b in revenue and £408.6m in earnings by 2029, based on 4.2% yearly top line growth and an earnings increase of about £165m from £243.2m today.
Uncover why Barratt Redrow's fair value indicates a 4% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternative angle on Barratt Redrow focuses on the potential impact of its multi branded outlets as a bullish catalyst. Before this week’s AGM and trading updates, the most optimistic analysts were forecasting about £7.3b of revenue and £563.5m of earnings by 2029, compared with the consensus of £6.9b of revenue and £408.6m of earnings. Use those gaps to assess how your own view might change once fresh numbers are released.
Explore 3 other Barratt Redrow fair value estimates, including one that suggests it could be worth as much as £3.36.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Barratt Redrow research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Barratt Redrow. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Barratt Redrow's overall financial health at a glance.
Looking For More Investment Ideas Beyond Barratt Redrow?
If Barratt Redrow has sharpened your view on what you want from a housing stock, use that criteria to broaden your watchlist with other candidates that fit your risk and income preferences through the Simply Wall St Screener.
- For investors who care most about financial resilience and low leverage, start with a list of solid balance sheet and fundamentals (10 results) that can help you pinpoint businesses with stronger foundations.
- If value is your priority and you want companies that trade below their estimated worth, scan a 14 high quality undervalued stocks tailored to highlight opportunities where fundamentals and price are out of sync.
- For readers who want income to do more of the heavy lifting in returns, focus on a 5 dividend fortresses and zero in on higher yielding payers with the cash flows to support distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com